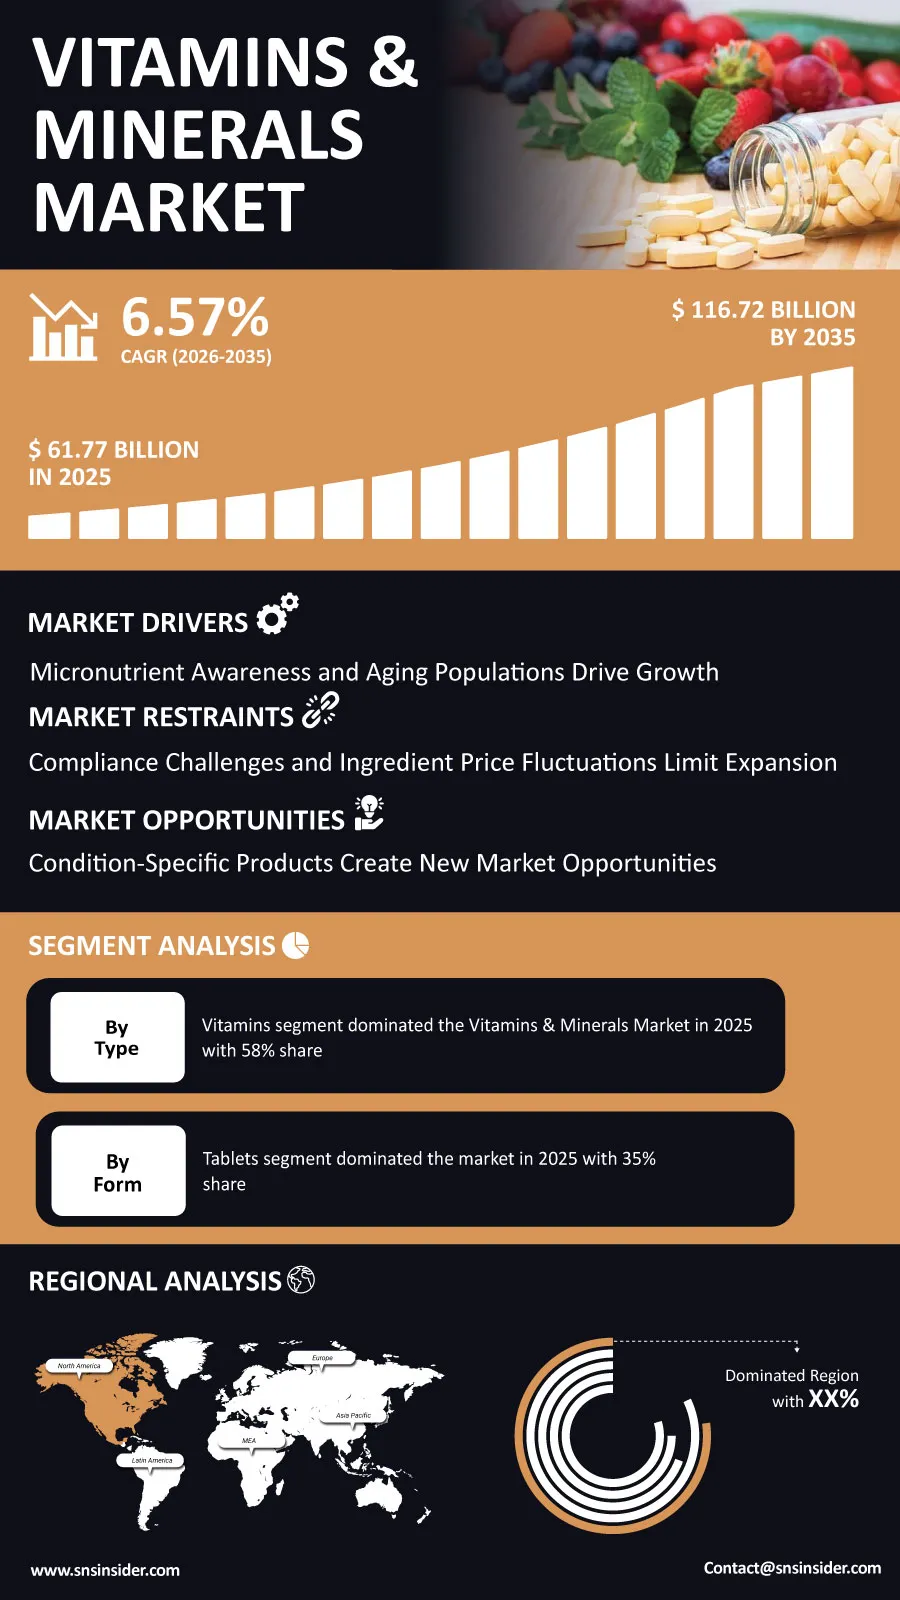
The global Vitamins & Minerals Market is on a steady growth path through 2035, as micronutrient deficiency awareness and format innovation continue reshaping how consumers approach daily supplementation. “According to a recent study by SNS Insider, the global Vitamins & Minerals Market size valued at USD 61.77 billion in 2025, is anticipated to grow to USD 116.72 billion by 2035, registering a CAGR of 6.57% over the 2026-2035 forecast period.”
Vitamins and minerals rarely get the spotlight in wellness media the way adaptogens or nootropics do, but they remain the category's steady financial core, the products people actually take every single day rather than experiment with for a few weeks and abandon. That consistency is exactly what makes the category valuable to manufacturers, even as flashier ingredient trends come and go around it.
Format is where most of the real competitive activity is happening right now, as brands race to make daily supplementation easier and more appealing for consumers who have historically found pill-swallowing enough of a barrier to skip the habit altogether.
To Get Detailed Insights on the Vitamins & Minerals Market – Request a Sample Report
Format Innovation Widens the Consumer Base
Gummies have done more than almost any other single innovation to expand who actually supplements consistently, turning a segment of the population that avoided pills entirely into regular buyers.This shift is reshaping manufacturing investment priorities across the industry, as companies weigh the higher production costs of gummies and other novel formats against the larger addressable market those formats unlock.
Some established players are exiting or restructuring their format portfolios as the competitive landscape shifts, reflecting how quickly format preference can reshape category economics.
Key Market Findings Highlight High-Growth Segments
Vitamins held the largest share of the Vitamins & Minerals Market in 2025, at 58%, reflecting decades of consumer familiarity and public health messaging around vitamin D, B-complex, and vitamin C. Minerals are the fastest-growing type, expanding at a 7.80% CAGR, pulled forward by magnesium's rapid rise as a sleep and stress-support ingredient.
By form, tablets led with 35% share in 2025, while gummies are growing fastest, at a 9.20% CAGR, as manufacturers target consumers who find pill-swallowing unpleasant. Adults remained the dominant end-user segment at 78.20% share, but geriatric consumers are climbing fastest, at an 8.60% CAGR, driven by rising demand for condition-specific formulations among aging populations.
Clinical Credibility and Format Appeal Anchor Competitive Positioning
Brands are being assessed for clinical integrity and format attractiveness at once, which was previously seen as two independent criteria when it came to consumer purchase decision-making. It is now becoming increasingly clear that investment in trending and clinically-supported ingredients such as magnesium in addition to attractive formats is a competitive advantage, whereas brands using generic formulas in the form of tablets compete on prices only.
This process is set to grow even faster, as innovations in formats broaden the consumer base of the category.
North America Leads as Asia Pacific Grows Fastest
North America holds the largest share of global market revenue, underpinned by decades of established supplement retail infrastructure and consumer habits that treat daily vitamin intake as routine. Asia Pacific, meanwhile, is growing fastest, propelled by rising health awareness and rapid delivery-system innovation across China, India, and Southeast Asia.
Europe holds a meaningful, mature share as well, shaped heavily by the region's strict regulatory frameworks, which have reinforced strong consumer trust in supplement safety even as they slow new product launches.
Leading Companies Drive Innovation and Competition
Competition in this market is playing out across format innovation, clinical substantiation, and distribution reach nearly as much as on traditional brand marketing, with several established players restructuring their portfolios in response to shifting format preferences.
Some of the major companies that operate in the global vitamins & minerals market are Amway Corporation, Herbalife Nutrition Ltd., Bayer AG, Pfizer Inc., Abbott Laboratories, Glanbia plc, Nestlé Health Science, Pharmavite LLC.
An SNS Insider Analyst Parry Kardani commented, “Vitamins and minerals remain the steady core of the broader supplement industry, but the companies winning share right now are the ones treating format, not just ingredient, as a genuine point of differentiation. As the format shift toward gummies and other more palatable delivery systems continues, manufacturers that can combine that appeal with credible clinical backing are best positioned to capture the fastest-growing parts of this market.”
About the Author

Get in touch