
Heat Stabilizers Market Report Scope & Overview:
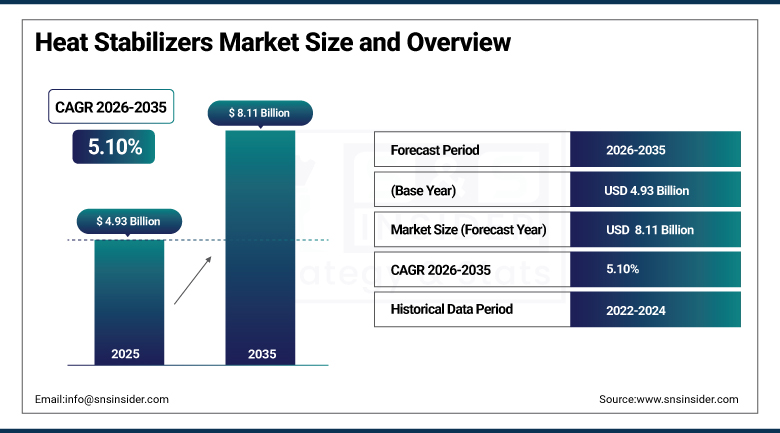
The Heat Stabilizers Market was valued at USD 4.93 Billion in 2025 and is expected to reach USD 8.11 Billion by 2035, growing at a CAGR of 5.10% from 2026-2035.
Heat Stabilizers Market growth is driven by the increased requirement for robust and heat-resistant plastics in the construction, automotive, electrical, electronics, and packaging sectors. With an increasing usage of PVC pipes, fittings, profiles, tubes, wires, and cables, there is a steady demand for stabilizers to inhibit any thermal decomposition during processing and increase the life of the material. Moreover, urbanization and development of infrastructure are adding to the demand for PVC materials for water distribution, sewage management, and construction purposes. Furthermore, the automotive sector’s increased use of plastics is fueling market growth. There have been advancements in calcium-zinc, organotin, and mixed metal-based stabilizers as well.
On February 29, 2024, Galata Chemicals launched Mark 2921, a next-generation tin-based heat stabilizer designed specifically for large-diameter PVC pipe extrusion applications. The company stated the product addresses growing demand for high-performance stabilization technology supporting expanding water infrastructure and irrigation projects worldwide.
To Get more information On Heat Stabilizers Market - Request Free Sample Report
Heat Stabilizers Market Trends
-
Growing transition from lead-based systems toward calcium-zinc and mixed-metal stabilizer formulations.
-
Rising manufacturer investment in tin-free stabilizer systems for medical-grade PVC applications.
-
Expanding regional capacity builds shortening lead times for processors across Asia and the Middle East.
-
Increasing demand for low-VOC stabilizer blends meeting stricter cabin air-quality regulations.
-
Rising adoption of customized stabilizer one-packs supporting long-term processor technical partnerships.
-
Growing focus on non-toxic, sustainable formulations amid tightening environmental regulations.
U.S. Heat Stabilizers Market Overview
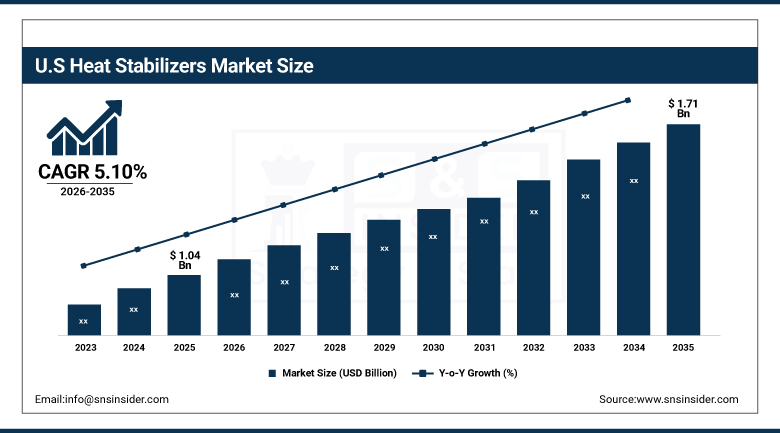
The U.S. Heat Stabilizers Market was valued at USD 1.04 Billion in 2025 and is expected to reach USD 1.71 Billion by 2035, growing at a CAGR of 5.10% from 2026-2035.
Growth in the U.S. Heat Stabilizers Market is driven by high demand for PVC-based materials in various industries such as construction, electricity, automobiles, and infrastructure applications. Construction activity is boosting the demand for PVC pipes, fittings, tubing, wires, and cables, which need to be thermally stabilized during the manufacturing process. Moreover, the upgrading of infrastructures and replacement of outdated utility systems will help in driving the demand for PVC. Increased usage of plastics in the automobile industry is contributing to the consumption of heat stabilizers for special applications. Lead-free, tin-free, and calcium-zinc based systems have become popular among manufacturers in order to meet the growing needs of the market.
In July 2025, Addivant, part of SI Group, expanded its production of non-lead heat stabilizers at its Texas facility to meet rising demand from PVC pipe, wire and cable, and packaging customers. The company stated the upgrade supports the broader U.S. market's continued shift toward environmentally safer stabilizer formulations.
Heat Stabilizers Market Segment Analysis
-
By Type, the Metal Soaps segment dominated the market with a 41.90% share in 2025, while the Mixed Metal Stabilizers segment is the fastest growing with a CAGR of 7.90% during 2026-2035.
-
By Form, the Liquid segment dominated the market with a 52.40% share in 2025, while the Solid segment is the fastest growing with a CAGR of 6.80% during 2026-2035.
-
By Application, the Pipes & Fittings segment dominated the market with a 38.60% share in 2025, while the Wires & Cables segment is the fastest growing with a CAGR of 6.90% during 2026-2035.
By Type, Metal Soaps Dominates the Market and Mixed Metal Stabilizers Grows Fastest
Metal Soaps dominated the market in 2025, a position built on their versatile performance across general-purpose polymer applications and well-established production infrastructure spanning decades of commercial use. Processors favour this stabilizer type precisely because it delivers dependable thermal protection at competitive cost across the widest range of PVC processing applications, a combination that continues to make metal soaps the default specification across pipe, profile, and general-purpose molding applications worldwide, even as newer stabilizer categories continue to expand around it.
Mixed Metal Stabilizers are projected to be the fastest-growing type category over the forecast period. Rising regulatory pressure to phase out organotin and lead-based systems continues to expand the addressable application base for this stabilizer type as processors increasingly seek calcium-zinc and barium-zinc alternatives offering comparable thermal performance without the environmental and health concerns associated with legacy formulations. As manufacturers continue refining mixed-metal formulation technology to match the processing characteristics of conventional systems, this segment continues to close the gap with metal soaps in overall market demand.
By Form, Liquid Dominates the Market and Solid Grows Fastest
Liquid segment dominated the market in 2025. This form continues to offer superior dispersion and processing consistency across a broad range of PVC compounding applications, particularly in flexible PVC formulations where precise dosing and rapid incorporation into the polymer matrix remain essential to achieving uniform thermal protection. This processing advantage continues to sustain liquid systems as the dominant form category across the broader stabilizer market.
Solid segment are expected to be the fastest-growing form category over the forecast period. Rising demand for precise dosing formats continues to expand the addressable application base for this form category across rigid PVC applications including pipes, profiles, and other extrusion-based products where solid one-pack systems offer handling and storage advantages relative to liquid alternatives. As processors increasingly value the reduced handling complexity solid formulations provide, this segment continues to close the gap with liquid stabilizers in overall market demand.
By Application, Pipes & Fittings Dominates the Market and Wires & Cables Grows Fastest
Pipes & Fittings applications dominated the market in 2025. Rapid urbanization and infrastructure development, with construction accounting for nearly 80% of overall stabilizer demand, continue to represent the single largest driver of overall heat stabilizer consumption worldwide, as PVC pipe extrusion requires substantial stabilizer loading to withstand processing temperatures and long-term service conditions. This foundational infrastructure role continues to sustain pipes and fittings as the largest application category by a clear margin across the broader market.
Wires & Cables applications are projected to expand fastest over the forecast period. Rising global investment in electrical grid infrastructure and telecommunications network expansion continues to drive PVC cable jacketing demand requiring specialized stabilizer formulations capable of meeting fire safety and long-term insulation performance requirements. As electrification programs continue expanding across both developed and emerging markets, wires and cables applications continue closing the gap with pipes and fittings in overall market demand.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 |
|
Asia Pacific |
China |
41.80% |
|
North America |
United States |
78.60% |
|
Europe |
Germany |
32.60% |
|
Latin America |
Brazil |
44.60% |
|
Middle East & Africa |
United Arab Emirates |
30.80% |
North America Heat Stabilizers Market Insights
North America represents a significant regional market for heat stabilizers, anchored by the United States' strong chemical manufacturing infrastructure and rising regulatory emphasis on non-lead stabilizer formulations. The United States accounts for the substantial majority of regional demand, reflecting both its PVC processing scale and its concentration of leading stabilizer manufacturers expanding domestic production capacity.
Canada contributes additional regional demand through its participation in North American construction and infrastructure investment. Continued domestic investment in non-lead and tin-free stabilizer technology is expected to support steady regional market development even as growth in percentage terms trails faster-scaling Asia Pacific markets building out PVC processing capacity from a considerably smaller existing base.
Europe Heat Stabilizers Market Insights
Europe holds a meaningful share of the global market, underpinned by a dense concentration of established stabilizer manufacturers and continued advancement in low-VOC and non-toxic formulation technology developed for automotive and construction applications. Germany's substantial chemical manufacturing base anchors regional demand, supported by a well-developed regulatory framework that continues to favour early adoption of environmentally compliant stabilizer technology across the country and neighbouring markets.
The United Kingdom, France, and other major European markets contribute consistent demand as regional processors continue extending non-toxic stabilizer technology into routine manufacturing practice. Continued European Union regulatory emphasis on eliminating hazardous stabilizer compounds supports steady regional demand for advanced, compliant formulations.
Asia Pacific Heat Stabilizers Market Insights
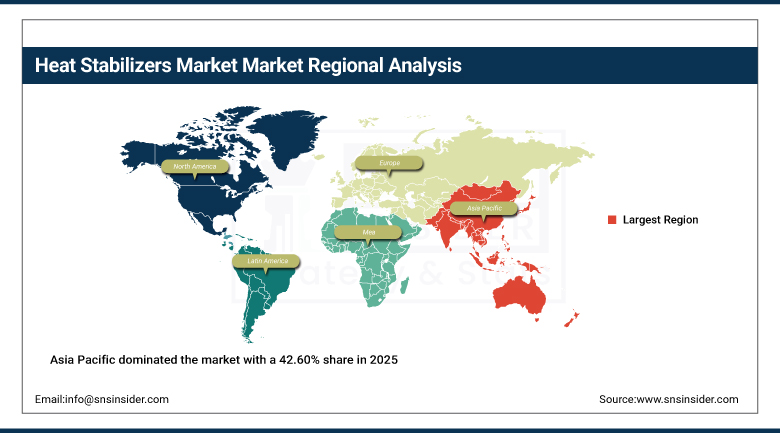
Asia Pacific dominated the market with a 42.60% share in 2025 and is also projected to expand at the fastest pace during the 2026-2035 forecast period, supported by rapid infrastructure development and expanding PVC pipe manufacturing capacity across the region. China continues to anchor regional demand as domestic stabilizer producers expand capacity to serve rising construction and infrastructure investment across both established coastal manufacturing hubs and rapidly developing inland provinces.
India's expanding construction sector and rising irrigation and water-management infrastructure investment continue adding meaningful regional growth as domestic PVC pipe production capacity expands. Regional capacity builds, including new calcium-based production capacity in China, continue providing regional supply security and shortening lead times for Asian processors managing compressed compliance deadlines, positioning the wider region to sustain both the largest revenue base and the fastest percentage growth of any global market through 2035.
Get Customized Report as per Your Business Requirement - Enquiry Now
MEA & Latin America Heat Stabilizers Market Insights
The Middle East & Africa market is supported by growing construction investment across the United Arab Emirates and Saudi Arabia, where extensive infrastructure development continues to lift demand for PVC pipe and profile stabilizer formulations across both public and private construction projects. Distribution partnerships extending local warehousing across Gulf Cooperation Council markets continue shortening lead times for regional processors in tender-driven construction markets.
Latin America's market is anchored by Brazil, where a sizeable domestic construction and PVC processing sector sustains steady stabilizer demand across both pipe and profile applications. Mexico contributes further incremental growth as construction activity continues expanding across the broader region, though adoption of the most advanced non-lead formulations across Latin America as a whole still lags meaningfully behind more established markets in North America and Europe.
Growth Drivers: Infrastructure Development and Regulatory-Driven Reformulation
Urbanization and infrastructure developments drive the main growth engine since the cost-effective and durable nature of PVC along with its high resistance to chemicals continues to make it a popular thermoplastic in various industries such as construction, agriculture, electronics, automotive, and packaging that necessitate a large use of stabilizers. This trend is supported by increasing demands for alternative stabilizer systems amid efforts to phase out lead and organotin stabilizer systems due to growing regulatory pressures.
Another important factor driving market growth is infrastructure investment in irrigation and water management projects, especially in emerging economies where PVC pipe production increases and calls for stabilizers. Increased global demand for electrical grid and telecom infrastructure installations drives growth in the market as well since wire and cable products require special stabilizers.
Restraints: Raw Material Price Volatility and Regulatory Transition Costs
The issue of price volatility in the cost of raw materials continues to be a real constraint in terms of market growth, considering the fact that prices of metal, phosphite, and specialty chemicals used in the manufacture of stabilizers keep on changing according to commodity market conditions, thus leaving formulators with narrow margins of profit. In most cases, the cost fluctuations affect small regional producers because the ability to transfer the costs to consumers is less than that of large multinationals.
Another important factor that acts as a constraint is the cost associated with regulatory changeovers. Since the phase out of lead and organotin stabilizers continues, there is need for continuous reforms so that performance of processing continues despite the changes in health and environmental standards.
Opportunities: Non-Toxic Formulation Innovation and Regional Capacity Expansion
There are opportunities in innovations in development of non-toxic and sustainable formulations of heat stabilizers. With increasing demands from the PVC processors for more environmentally friendly additives, there is an opportunity to manufacture calcium-zinc, organic and other alternative forms of stabilizers that can ensure the thermal stability, processing ease and good performance. Environmental awareness has also created an impetus for the manufacturers to include safer additive systems in pipes, profiles, cables and other PVC products.
One of the most promising growth opportunities is the regional expansion of production facilities, especially in proximity of large centers for PVC processing and manufacturing. Setting up local production, storage, technical service and distribution networks can help minimize transportation distance and delivery time and enhance reliability of the supply chain. The ability to meet regional formulation needs through local production can be a useful competitive advantage.
Recent Developments
-
2024: Songwon Industrial introduced a new series of liquid HPT coating stabilizers at ACS 2024, alongside its established SONGSORB UV absorber and SONGNOX antioxidant product lines.
-
2025: Baerlocher launched its Tin Replacement initiative, featuring calcium-zinc technologies designed for regulated PVC applications previously dependent on organotin stabilizer systems.
-
2025: PMC Group launched a new series of calcium-zinc heat stabilizers engineered for high-performance rigid PVC applications, with early trials showing improved thermal stability in building and construction materials.
-
2025: Kaneka Corporation collaborated with material science institutes to develop hybrid stabilizer systems combining organic and inorganic chemistries, with early results showing enhanced heat resistance and lower migration.
Heat Stabilizers Companies are:
-
BASF SE
-
Baerlocher GmbH
-
Akdeniz Kimya A.S.
-
Galata Chemicals LLC
-
PMC Group, Inc.
-
Sun Ace Kakoh (Pte) Ltd.
-
Songwon Industrial Co., Ltd.
-
Adeka Corporation
-
Valtris Specialty Chemicals
-
Kaneka Corporation
-
Chemson Polymer-Additive AG
-
Nan Ya Plastics Corporation
-
Clariant AG
-
Dow Inc.
-
Addivant (SI Group)
-
Sakai Chemical Industry Co., Ltd.
-
Kisuma Chemicals
-
Vikas Ecotech Ltd.
Heat Stabilizers Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 4.93 Billion |
| Market Size by 2035 | USD 8.11 Billion |
| CAGR | CAGR of 5.10% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Metal Soaps, Mixed Metal Stabilizers, Organotin, Liquid Phosphite, Others) • By Form (Liquid, Solid) • By Application (Pipes & Fittings, Profiles & Tubing, Wires & Cables, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | BASF SE, Baerlocher GmbH, Akdeniz Kimya A.S., Galata Chemicals LLC, Reagens S.p.A., PMC Group, Inc., Sun Ace Kakoh (Pte) Ltd., Songwon Industrial Co., Ltd., Adeka Corporation, Valtris Specialty Chemicals, Kaneka Corporation, Chemson Polymer-Additive AG, Nan Ya Plastics Corporation, Lanxess AG, Clariant AG, Dow Inc., Addivant (SI Group), Sakai Chemical Industry Co., Ltd., Kisuma Chemicals, Vikas Ecotech Ltd. |

Frequently Asked Questions
Key players include BASF SE, Baerlocher, Akdeniz Kimya, Galata Chemicals, Reagens, PMC Group, Sun Ace Kakoh, Songwon Industrial, others.
Non-toxic stabilizer innovation and regional production expansion offer significant opportunities through sustainability, regulatory compliance, supply security, and localized customer support.
Growth is primarily driven by rapid urbanization and infrastructure development, combined with mounting regulatory pressure to replace lead-based and organotin stabilizer systems.
By Application, Pipes & Fittings dominated the market in 2025, reflecting sustained infrastructure development driving PVC pipe extrusion demand.
Asia Pacific dominated the market with a 42.60% share in 2025, supported by rapid infrastructure development and expanding PVC pipe manufacturing capacity, led by China.
