
Malic Acid Market Report Scope & Overview:
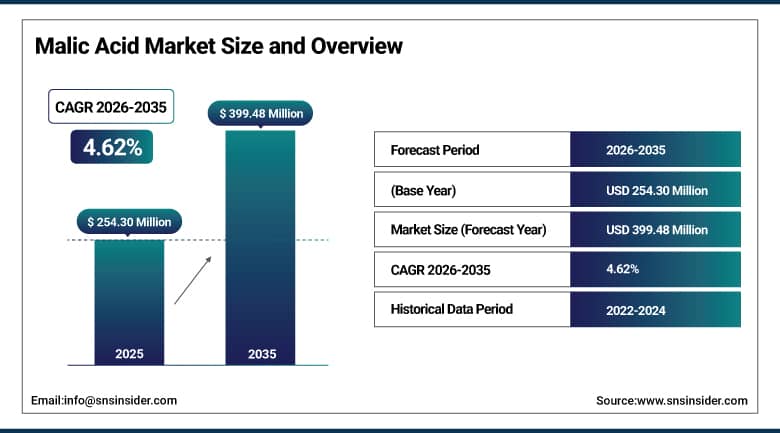
The Malic Acid Market size was valued at USD 254.30 Million in 2025 and is expected to reach USD 266.05 Million in 2026, rising to USD 399.48 Million by 2035. The market is forecast to grow at a CAGR of 4.62% during 2026–2035. Malic acid is an organic acid found naturally in fruit, and it gives food and drinks a sharp, lasting sour taste. It is made by synthesis from maleic anhydride, which yields the DL form, or by fermentation and enzymatic routes, which yield the L form. It serves as an acidulant, flavor enhancer and ingredient in cosmetics, pharmaceuticals and feed.
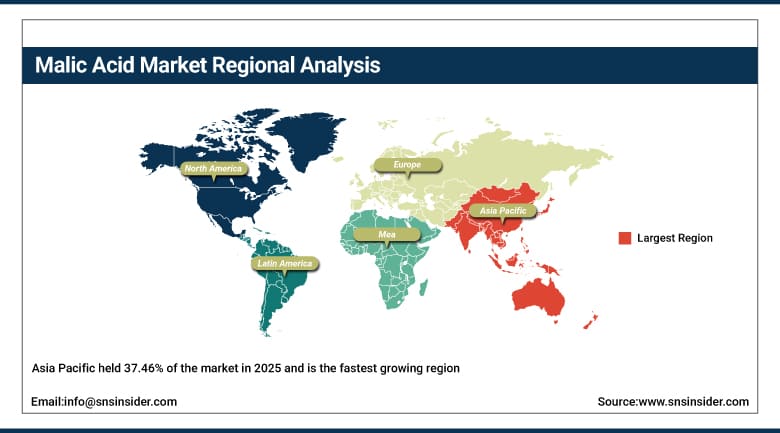
Asia Pacific accounted for the largest share of the market, at 37.46% in 2025, because China hosts most synthetic DL-malic acid capacity and the region has large beverage, confectionery and personal care industries. Europe follows, supported by established producers and demand for natural flavors, while North America is growing as new local plants lower dependence on imports. Asia Pacific is also the fastest growing region, as India, China and Southeast Asia expand packaged food and drink output and as local producers add capacity for higher purity grades. Latin America and Middle East & Africa remain smaller but are growing steadily.
To Get More Information On Malic Acid Market - Request Free Sample Report
Key Report Takeaways
-
By product type, DL-malic acid held 55.74% in 2025, while L-malic acid is the fastest growing.
-
By application, food and beverages held 50.64% in 2025, while personal care and cosmetics is the fastest growing.
-
By form, powder and granules held 61.38% in 2025, while liquid is the fastest growing.
-
By grade, food grade held 63.18% in 2025, while pharmaceutical grade is the fastest growing.
-
By region, Asia Pacific held 37.46% in 2025 and is also the fastest growing.
Market Trends and Insights
Food makers are asking for acidulants with a natural image, which is lifting interest in L-malic acid made by fermentation and in mixes of acids that give a longer lasting sour note in sour candy, sports drinks and sugar-reduced products. Producers are also introducing low-dust granules, coated grades and high-purity versions for pharmaceutical and nutraceutical use.
Capacity is moving closer to customers, with new plants in North America and ongoing additions in Asia, and ownership is consolidating as larger ingredient groups buy specialist makers. Suppliers are also working on bio-based routes to lower energy use and reduce reliance on petrochemical feedstock.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Rising use as an acidulant in beverages, sour confectionery and snacks |
+1.98% |
Global |
Medium term (2 to 4 years) |
|
Clean-label and natural ingredient preference |
+1.46% |
Europe and North America |
Long term (4 years or more) |
|
Growth of personal care, pharmaceutical and nutraceutical uses |
+1.04% |
Asia Pacific and North America |
Medium term (2 to 4 years) |
|
Capacity additions in North America and Asia |
+0.78% |
North America and Asia Pacific |
Short term (2 years or less) |
|
Wider industrial and feed applications |
+0.56% |
Global |
Medium term (2 to 4 years) |
Rising Use as an Acidulant in Beverages, Sour Confectionery and Snacks
Food and drink makers use malic acid to give a smooth, long-lasting sourness that differs from the sharper taste of citric acid, and it is common in sour candy, fruit drinks, sports drinks, gum and coated snacks. Product launches in sour and tangy flavors are increasing in Asia, Europe and North America, and sugar-reduced formulas use acids to restore taste balance. This steady need places malic acid among the most widely used food acids. Producers also see year-round demand from bottlers and candy makers.
Clean-Label and Natural Ingredient Preference
Shoppers favor short ingredient lists and natural origin, and food brands respond by choosing acids that can be labeled as fermentation derived or naturally occurring in fruit. L-malic acid made by fermentation fits this need and often sells at a premium to synthetic grades. Retail and brand sourcing standards in Europe and North America are encouraging manufacturers to expand fermentation and enzymatic routes, which widens the market for higher value grades. Premium positioning also lets suppliers earn stronger margins than on bulk synthetic grades.
Growth of Personal Care, Pharmaceutical and Nutraceutical Uses
Malic acid is used in skin care and hair care products as a mild alpha hydroxy acid that adjusts pH and gently exfoliates, and in pharmaceuticals as an excipient, buffer and flavor masker in tablets, syrups and effervescent products. Dietary supplements for energy and muscle support also use the acid and its salts. These applications require higher purity and bring better margins than bulk food uses. Growing consumer interest in beauty, wellness and supplements across Asia and North America is expected to keep adding new product launches over time.
Capacity Additions in North America and Asia
Producers are building plants near major customers to cut freight costs and reduce supply risk. New facilities in North America are aimed at reducing dependence on imports, while Asian producers keep adding synthetic and fermentation capacity. Greater local supply improves availability, shortens lead times and allows suppliers to offer more grades, which encourages buyers to adopt malic acid in new formulations. Long-term supply agreements with large beverage and confectionery makers underpin these investments, and ownership changes among producers are bringing new capital into the industry.
Wider Industrial and Feed Applications
Beyond food and personal care, malic acid serves as a chelating agent in metal cleaning and finishing, an additive in cleaning products, a component of some textile treatments and an acidifier in animal feed. These outlets are smaller but steady, and they add demand for technical grades. Industrial users value the acid for being biodegradable and less hazardous than some mineral acids, which suits tightening workplace and environmental rules. Steady demand from these smaller outlets cushions suppliers when food demand softens in some periods.
Restraints Impact Analysis
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Volatile prices of maleic anhydride, benzene and energy |
-0.52% |
Global |
Short term (2 years or less) |
|
Competition from citric acid and other acidulants |
-0.34% |
Global |
Long term (4 years or more) |
|
Low-cost imports and trade barriers |
-0.20% |
North America and Europe |
Medium term (2 to 4 years) |
|
Cost and yield limits of fermentation routes |
-0.14% |
Global |
Medium term (2 to 4 years) |
Volatile Prices of Maleic Anhydride, Benzene and Energy
Synthetic malic acid is made from maleic anhydride, which is itself derived from benzene or butane, so its cost follows petrochemical prices and energy costs. When crude oil, natural gas or power prices spike, producers face margin pressure that they cannot always pass to food customers on fixed-price contracts. Smaller plants without integrated maleic anhydride supply are most exposed to such swings in input costs. Integrated producers with their own maleic anhydride units enjoy more stable costs, which widens the gap with non-integrated plants.
Competition from Citric Acid and Other Acidulants
Citric acid is far cheaper and produced at much larger scale, and it can replace malic acid in many drinks and foods when cost matters more than taste profile. Lactic, fumaric, tartaric and phosphoric acids also compete in specific uses. Buyers often limit malic acid to products where its flavor adds clear value, which caps growth in price-sensitive categories and in developing markets. Producers therefore stress the premium taste of malic acid and work with brand owners to build products around it.
Low-Cost Imports and Trade Barriers
Lower-priced material from Asia puts pressure on producers in North America and Europe, and trade remedies or tariff changes can disrupt supply chains and pricing with little notice. Buyers must keep several sources to manage risk, which complicates long-term planning for both suppliers and customers. Governments in some regions have applied anti-dumping duties or tariffs on certain organic acids, and the resulting shifts in trade flows can raise costs for downstream food and beverage makers, who must qualify new suppliers and test new lots before shifting volumes.
Cost and Yield Limits of Fermentation Routes
Producing L-malic acid by fermentation or enzymatic conversion needs careful process control and large fermenters, and yields and purification costs keep the price above that of synthetic DL-malic acid. Only a few firms have mastered the process at scale. Until yields improve and costs fall, the share of natural grades will remain limited to premium products. Any major plant outage or quality issue can tighten supply of natural grades, since few alternative sources exist. Capital cost per ton of fermentation capacity is also higher than for synthetic plants.
Malic Acid Market Segment Analysis
By Product Type, DL-Malic Acid Dominates Malic Acid Market; L-Malic Acid to Register Fastest Growth.
DL-malic acid accounts for 55.74% of the market in 2025 because it is made in large quantities from maleic anhydride at low cost and meets most food, beverage and industrial needs. China, Italy, Japan and other producers run large plants that supply confectionery, soft drink and cleaning product makers around the world. Its stable quality, lower price and long shelf life keep it the first choice for cost-conscious buyers. Large buyers also value the wide global network of suppliers.
L-malic acid is projected to grow at a CAGR of 6.21% during 2026–2035. It is the natural form found in fruit and is produced by fermentation or enzymatic conversion, which allows a natural label and use in infant, nutraceutical and premium food products. Safety and regulatory preference for the L form in some uses, along with new plants in Asia and North America, supports faster growth. Producers invest in new plants to meet rising orders from premium brands.
By Application, Food and Beverages Dominate Malic Acid Market; Personal Care and Cosmetics to Register Fastest Growth.
Food and beverages hold a 50.64% share in 2025 because malic acid is a core acidulant in sour candy, soft drinks, juices, jams, gum, bakery fillings and snack coatings. The long lasting tart taste differs from citric acid and is valued by product developers. Global demand for packaged and flavored products, along with sugar reduction efforts, keeps this segment the largest consumer of the acid. Large soft drink and candy brands buy through annual contracts with global suppliers.
Personal care and cosmetics are expected to expand at a CAGR of 5.93% from 2026 to 2035. Malic acid is used in skin care, hair care and exfoliating products as a mild alpha hydroxy acid and pH adjuster, and demand grows as brands look for fruit-derived ingredients. Clean beauty trends, rising sales in Asia and new product lines for sensitive skin support growth. Dermatology brands and spa product makers also use it in peels and masks, which adds premium demand.
By Form, Powder and Granules Dominate Malic Acid Market; Liquid to Register Fastest Growth.
Powder and granules account for 61.38% of the market in 2025 because the crystalline acid is easy to store, weigh and ship, and it dissolves quickly in dry mixes, coatings and beverage powders. Food makers use it in bags and bulk sacks with a long shelf life. Low-dust and coated granules are also gaining use in sour sanding for candy and snacks, which supports demand for solid forms. Long storage life also lowers waste and cost for buyers.
Liquid malic acid is projected to grow at a CAGR of 5.47% during 2026–2035. Solutions of 50.00% strength are used in beverage syrups, cleaning products and cosmetic formulations because they dose accurately and reduce dust. Bottlers and personal care makers with automated lines prefer liquid for ease of handling, and more suppliers are offering tanker and intermediate bulk container delivery in several regions. Contract fillers in Europe and Asia are also adopting liquid acids for their beverage lines.
By Grade, Food Grade Dominates Malic Acid Market; Pharmaceutical Grade to Register Fastest Growth.
Food grade holds a 63.18% share in 2025 because most malic acid is sold for confectionery, beverages and other foods, where it must meet purity and safety standards set by food regulators. Suppliers hold food safety certificates such as ISO 22000 and FSSC 22000, and large brand owners audit their plants regularly. This steady volume gives food grade the largest share of sales. Independent audits and quality records help suppliers keep long supply contracts with large global brands.
Pharmaceutical grade is expected to grow at a CAGR of 6.09% from 2026 to 2035. It meets pharmacopoeia limits for purity and is used as an excipient, buffer and taste masker in tablets, syrups and effervescent products, and as an ingredient in nutraceuticals. Drug makers pay more for traceable lots, and suppliers are adding capacity for ultra-pure grades to meet this demand. Contract manufacturers and supplement brands in the United States and Europe are among the most active buyers.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
83.09% |
|
Europe |
Germany |
24.57% |
|
Asia Pacific |
China |
53.62% |
|
Middle East & Africa |
South Africa |
34.28% |
|
Latin America |
Brazil |
48.76% |
Asia Pacific Malic Acid Market
Asia Pacific held 37.46% of the market in 2025 and is the fastest growing region, with a projected CAGR of 5.94% during 2026–2035. China leads the region, with several producers of DL-malic acid and growing fermentation capacity, and the country supplies buyers across the world. Large beverage, candy and personal care industries in the region add strong local demand for the acid. Government support for specialty chemical clusters and export zones lowers costs for new fermentation units and attracts foreign investors.
Japan is home to Fuso Chemical, a long-standing supplier of high-purity grades, and South Korea has producers serving electronics and food customers. India is growing quickly with packaged food, soft drink and cosmetics output, and Southeast Asian nations add demand from beverage and snack makers. Rising incomes and urban diets keep the region ahead of others. Chinese exporters supply many buyers abroad, and the shift toward higher purity and fermentation-based products is expected to lift unit prices over time, while competition among local producers keeps pricing keen.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Malic Acid Market
North America held 25.48% of the market in 2025, led by the United States. The U.S. market was valued at USD 53.84 Million in 2025 and is expected to register a CAGR of 4.11% during 2026–2035. Demand comes from sour candy, beverages, snacks and dietary supplements, and new plants are being built to lower dependence on imported malic and fumaric acid. Large soft drink and candy makers prefer suppliers that can deliver quickly and meet strict food safety audits each year.
Canada adds supply and demand through producers in Ontario and a food and beverage industry that exports to the United States. Mexico is counted in Latin America, although its candy and beverage factories tie it closely to North American supply chains. Buyers in the region increasingly value local supply for reliability. Ingredient distributors in the country stock both synthetic and fermentation-based grades, and supplement and cosmetic brands increasingly ask suppliers for documented origin and certification such as Non-GMO and kosher labels.
Europe Malic Acid Market
Europe accounted for 27.12% of the market in 2025, with Germany as the leading country. The region has long-established confectionery, beverage and personal care industries, and Italy hosts a major synthetic producer. Demand for natural-origin ingredients and strong food safety rules favor suppliers with traceable, high-quality material. Germany, France and the United Kingdom host large food groups with long-standing supplier relationships, and quality audits by retailers keep standards high. Regulations from the European Food Safety Authority set purity and use limits for acids in foods.
The United Kingdom, France, Italy, Spain and Poland are other important markets, with strong demand for sour confectionery and flavored drinks. Producers in the region invest in energy efficiency and higher purity grades to defend their position against imports, while brand owners seek fermentation-derived options for clean-label products. Mid-sized processors in Poland, Hungary and Spain are adding sour candy and beverage lines for export, and distributors in the region stock several grades to serve small and medium buyers with short lead times.
Latin America Malic Acid Market
Latin America accounted for 5.74% of the market in 2025, with Brazil as the leading country. The region has large beverage, juice and confectionery sectors, and Brazil is a major consumer of acidulants in soft drinks and processed fruit. Mexico is the second major market, supported by a strong candy industry and export-oriented food production. Soft drink bottlers in Brazil and Mexico are the largest buyers, and processors of tropical fruit use acids to balance flavor in juices and pulps, which supports steady regional consumption.
Argentina, Colombia and Chile add demand from fruit processing, beverages and personal care. Most malic acid is imported from Asia, Europe and North America, so distributor networks play a big role, and local mixing and repacking of imported acids is growing as regional food companies expand. Regional trade agreements ease cross-border flows, and growing local food companies are starting to qualify more than one supplier to reduce risk from shipping delays and currency swings. Brazil leads purchasing within the region through large consumer brands.
Middle East & Africa Malic Acid Market
Middle East & Africa held 4.20% of the market in 2025. South Africa leads the region and hosts a local producer, Isegen South Africa, that supplies food and beverage customers. Bottlers and confectionery makers across the region use malic acid in fruit drinks, sweets and powdered mixes. Bottlers serving the Southern African market also rely on local technical support, and regional distributors in Johannesburg and Durban stock several grades for smaller food makers. Strong growth in soft drink consumption among young populations adds further volume over time.
Egypt, Saudi Arabia, the United Arab Emirates, Turkey and Nigeria add demand from growing packaged food and beverage industries. The region relies mostly on imports, which creates openings for suppliers from Asia and Europe, and population growth and rising urbanization support steady expansion in demand. Government programs to expand local food processing are encouraging investment in packaging and ingredient supply chains, and trade shows in Dubai help suppliers meet regional buyers. Supply remains tied to shipping routes through the Suez Canal and Gulf ports, so inventory planning matters.
Competitive Landscape
The Malic Acid Market is moderately consolidated. A small group of global producers, including Italian, Japanese, Canadian, Indian and Chinese firms, supply a large part of world output, while many regional makers and traders serve local customers. Competition rests on cost, purity, certification, supply security and the ability to offer both DL and L grades.
Companies are expanding capacity near end markets, forming ownership ties with larger ingredient groups and developing fermentation-based and high-purity grades. Input cost changes and trade measures influence pricing across the group.
Malic Acid Market Industry Leaders
1. Polynt: Italian chemical group producing maleic anhydride and malic acid.
2. Fuso Chemical: Japanese maker of high-purity malic acid and other specialty chemicals.
3. Bartek Ingredients: Canadian producer of food-grade malic and fumaric acid, now part of ICL Group.
4. Thirumalai Chemicals: Indian chemical company with a new plant for maleic anhydride, malic acid and fumaric acid in the United States.
5. Changmao Biochemical Engineering: Chinese producer of DL-malic acid and related organic acids.
Companies Covered in this Report
-
Polynt
-
Fuso Chemical
-
Bartek Ingredients
-
Thirumalai Chemicals
-
Changmao Biochemical Engineering
-
Yongsan Chemicals
-
Anhui Sealong Biotechnology
-
Isegen South Africa
-
The Chemical Company
-
Miles Chemical Company
-
Mubychem Group
Recent Industry Developments
-
September 2023: Bartek Ingredients confirmed that construction of its malic and fumaric acid facility in Ontario, which began in January 2023, was progressing on schedule.
-
December 2025: ICL Group announced a definitive agreement to acquire Bartek Ingredients in two phases, starting with about USD 90.00 Million in cash for roughly 50.00% of the company.
-
December 2025: Thirumalai Chemicals moved its West Virginia facility into pre-commissioning and startup, including a food ingredients plant with capacity above 30,000 tons per year for malic and fumaric acid.
Scope and Research Methodology
This study estimates the Malic Acid Market for 2025 as the base year and forecasts it through 2035. The scope covers DL-malic, L-malic and D-malic acid produced by chemical synthesis, fermentation and enzymatic routes, supplied for food and beverage, personal care, pharmaceutical, feed and industrial uses. Values are reported in USD at the producer selling price and are segmented by product type, application, form, grade and region. Fumaric acid, citric acid and other organic acids are excluded from the scope, and the study period for historical data runs from 2021 to 2025. Reported values exclude taxes, freight and distributor margins, and all figures are converted to USD at fixed annual rates.
Secondary research included company annual reports, investor presentations, regulatory filings, customs and trade statistics, pharmacopoeia and food additive standards, association publications and peer-reviewed literature. Primary research consisted of structured interviews and surveys with plant managers, procurement heads, formulators and distributors in major producing and consuming regions. Expert opinions were weighed against published data to correct for bias, and responses were screened for relevance and consistency across regions. Interviews were held with participants from large producers and smaller regional firms to capture the full range of pricing and demand patterns. Findings from these inputs were compared across sources to check for gaps before the model was built.
Market size was built from the bottom up using plant capacity, utilization and selling prices, and was cross-checked from the top down against consumption in confectionery, beverages and personal care. Triangulation across these views fixed the base year value. Forecasts consider input costs, trade measures, regulation and demand growth, and segment and regional shares were assigned from production and consumption patterns. Currency effects were removed by holding exchange rates constant throughout the forecast period, and key assumptions were reviewed with industry experts. Growth rates were tested under conservative and optimistic cases.
Malic Acid Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 254.30 Million |
| Market Size by 2035 | USD 399.48 Million |
| CAGR | CAGR of 4.62% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (DL-Malic Acid, L-Malic Acid, and D-Malic Acid) • By Application (Food and Beverages, Personal Care and Cosmetics, Pharmaceuticals, and Others) • By Form (Powder and Granules and Liquid) • By Grade (Food Grade, Pharmaceutical Grade, and Industrial Grade) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Polynt, Fuso Chemical, Bartek Ingredients, Thirumalai Chemicals, Changmao Biochemical Engineering, Yongsan Chemicals, Anhui Sealong Biotechnology, Isegen South Africa, The Chemical Company, Miles Chemical Company, Mubychem Group |

Frequently Asked Questions
The market was valued at USD 254.30 Million in 2025 and is projected to reach USD 399.48 Million by 2035, growing at a CAGR of 4.62% during 2026–2035.
Asia Pacific leads, with a 37.46% share in 2025, and it is also expected to grow fastest, at a CAGR of 5.94% during 2026–2035.
DL-malic acid, food and beverages, powder and granules and food grade lead, while L-malic acid, personal care and cosmetics, liquid and pharmaceutical grade grow fastest.
Use as an acidulant, clean-label preference, personal care and pharmaceutical uses, new capacity and wider industrial applications drive demand.
Polynt, Fuso Chemical, Bartek Ingredients, Thirumalai Chemicals and Changmao Biochemical Engineering lead, along with Yongsan Chemicals, Anhui Sealong Biotechnology and Isegen South Africa.
