
Mononucleosis Diagnostic Market Report Scope & Overview:
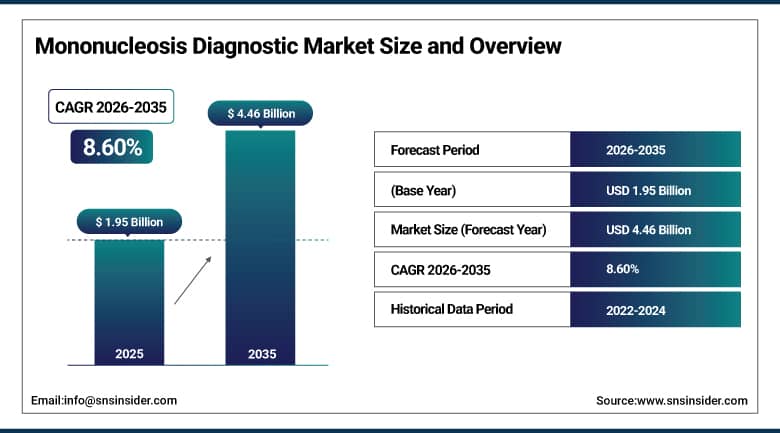
The Mononucleosis Diagnostic Market was valued at USD 1.95 Billion in 2025 and is expected to reach USD 4.46 Billion by 2035, growing at a CAGR of 8.60% from 2026 to 2035.
Technological advancements in the field of diagnostics are continuously increasing the efficiency of mononucleosis testing through improved accuracy and speed of test execution, while the increasing awareness about mononucleosis among medical practitioners and the general population is continuously boosting the demand for such diagnostics due to their high efficiency and speed of execution.
In 2025, Abbott got approval from Health Canada for its newest mononucleosis diagnostic test, allowing the product to be launched commercially in Canadian healthcare institutions, thus indicating the continuous efforts of the diagnostics industry to improve the quality of testing platforms through the creation of next generation mononucleosis diagnostic devices that go through simplified regulatory processes.
Market Size and Forecast:
-
Market Size in 2026E: USD 2.12 Billion
-
Market Size by 2035: USD 4.46 Billion
-
CAGR: 8.60% from 2026 to 2035
-
Fastest Growing Region: Asia Pacific
-
Largest Region: North America
To Get More Information On Mononucleosis Diagnostic Market - Request Free Sample Report
Mononucleosis Diagnostic Market Trends:
-
Growing development of rapid point-of-care testing kits is enabling faster mononucleosis diagnosis outside traditional laboratory settings.
-
Rising integration of AI for diagnostic accuracy is improving result interpretation and reducing operator-dependent variability across testing platforms.
-
Expanding multiplex lateral flow platforms are enabling simultaneous detection of heterophile antibodies alongside markers of concurrent bacterial infection.
-
Increasing expansion of telehealth services is supporting remote consultation and diagnostic follow-up for suspected mononucleosis cases.
-
Growing streamlined regulatory approval pathways are enabling manufacturers to more rapidly commercialize next-generation diagnostic platforms.
U.S. Mononucleosis Diagnostic Market Outlook:
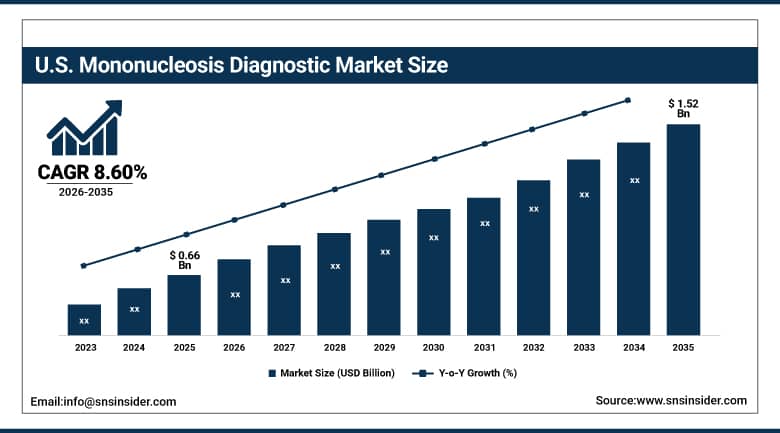
The U.S. Mononucleosis Diagnostic Market was valued at USD 0.66 Billion in 2025 and is projected to reach USD 1.52 Billion by 2035, growing at a CAGR of 8.60% during 2026-2035.
The presence of highly advanced healthcare facilities with highly sophisticated diagnostic labs and hospitals, equipped with advanced technologies for testing, continues to enable the quick acceptance of the latest methods of diagnosis in the country. The FDA is continuing to streamline the process of clearing the latest generation of mononucleosis diagnostic devices, which helps manufacturers in quickly making the products available in the market. Favorable reimbursement policies along with high infection rates of infectious mononucleosis continue to sustain the diagnostic testing demand in the country.
BD (Becton, Dickinson and Company) obtained clearance from the FDA in 2024 for a rapid test for diagnosing mononucleosis, which further supports the trend of U.S. regulatory clearances for the commercialization of next-generation mononucleosis diagnostic platforms in America.
Mononucleosis Diagnostic Market Segment Analysis:
-
By Test Type, EBV Antibody Test led the Mononucleosis Diagnostic Market with a 38.60% share in 2025, while Monospot Test is the fastest-growing test type segment with a CAGR of 9.80% from 2026-2035.
-
By Technology, Serological/Immunoassay led the Mononucleosis Diagnostic Market with a 54.60% share in 2025, while Point-of-Care Testing is the fastest-growing technology segment with a CAGR of 11.40% from 2026-2035.
-
By End User, Hospitals led the Mononucleosis Diagnostic Market with a 42.60% share in 2025, while Home Care/POC is the fastest-growing end user segment with a CAGR of 12.20% from 2026-2035.
By Test Type, EBV Antibody Test Dominated the Market While Monospot Test Is the Fastest-Growing Segment
EBV Antibody Test held the largest share of Mononucleosis Diagnostic Market at 38.60%, owing to its better accuracy of diagnosis due to sensitivity and specificity of the test being significantly better than conventional heterophile antibody tests. EBV serology helps distinguish between acute infection, previous infection, and immunity by detecting the presence of virus-specific IgM and IgG antibodies, thus making it the most suitable confirmatory test for diagnosing mononucleosis.
Monospot Test is expected to hold the highest CAGR of 9.80% during the forecast period from 2026 to 2035 due to the development of Monospot platforms along with automated lateral flow readers, which increase the precision of diagnosis while reducing operator-to-operator variability. Companies are increasing their Monospot product range by developing multiplex lateral flow platforms that detect heterophile antibodies, along with the markers of bacterial infections occurring along with the former.
By Technology, Serological/Immunoassay Dominated the Market While Point-of-Care Testing Is the Fastest-Growing Segment
The Serological/Immunoassay category dominated the Mononucleosis Diagnostic Market in 2025 with a revenue share of 54.60%, owing to the clinical standards of antibody testing techniques for diagnosis of mononucleosis. The serology test is known for its characterized performance and wide availability within laboratory structures, helping it maintain the dominant position in most parts of the world's mononucleosis testing market.
The Point-of-Care Testing category is anticipated to exhibit the highest CAGR of 11.40% during the forecast period 2026-2035 due to rising needs for rapid diagnostic testing techniques that provide instant results within minutes instead of hours. The advancements in the field of developing rapid kits for point-of-care testing along with cloud-based integration of results will further help in maintaining above average growth of this category compared to other types of laboratory tests.
By End User, Hospitals Dominated the Market While Home Care/POC Is the Fastest-Growing Segment
The Hospitals segment led the Mononucleosis Diagnostic Market with a revenue share of 42.60% in 2025, reflecting hospitals' role as the primary setting for definitive mononucleosis diagnosis, particularly for cases presenting with complications or requiring differentiation from other serious infectious conditions. Hospitals maintain comprehensive laboratory infrastructure capable of performing both rapid screening and confirmatory serological testing, sustaining this channel's dominant position across the broader mononucleosis diagnostic market.
The Home Care/POC segment is expected to register the fastest CAGR of 12.20% during the forecast period 2026-2035, driven by expanding telehealth services supporting remote consultation and diagnostic follow-up alongside growing consumer comfort with at-home and near-patient testing. Rising availability of simplified, accurate rapid testing kits suitable for use outside traditional clinical settings continues to reinforce this segment's rapid growth trajectory relative to conventional hospital and laboratory-based testing channels.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.60% |
|
Europe |
Germany |
22.80% |
|
Asia Pacific |
China |
34.60% |
|
Middle East & Africa |
Saudi Arabia |
24.60% |
|
Latin America |
Brazil |
27.40% |
North America Mononucleosis Diagnostic Market Insights
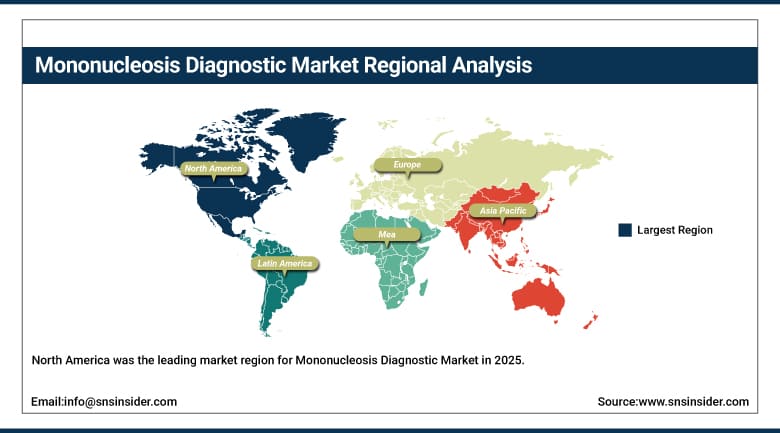
North America was the leading market region for Mononucleosis Diagnostic Market in 2025, on account of the developed health care infrastructure, favorable reimbursement scenario, and the high prevalence of infectious mononucleosis in the region. Continued investments in health care infrastructure that facilitates new methods of testing, along with ongoing research and development activities by diagnostic companies operating in the region, are strengthening the dominance of the region.
The U.S. represented around 85.60% of the North American market in 2025, owing to the presence of a large number of diagnostic laboratories and hospitals that have the capacity for conducting advanced diagnostic tests. Canada is contributing to the growth of the regional market through investments in health care infrastructure and adoption of new diagnostic tests.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Mononucleosis Diagnostic Market Insights
Europe represented a meaningful share of the global Mononucleosis Diagnostic Market in 2025, supported by well-established healthcare systems and growing adoption of advanced serological and point-of-care testing technology across major member states. Rising awareness of infectious mononucleosis among healthcare professionals continues to reinforce steady regional demand for accurate diagnostic solutions.
Germany led the European market with a 22.80% regional share in 2025, supported by its strong domestic diagnostic manufacturing base and well-established laboratory infrastructure. The United Kingdom, France, and Italy are also contributing meaningfully to regional growth, supported by expanding point-of-care testing adoption across major European healthcare markets.
Asia Pacific Mononucleosis Diagnostic Market Insights
The APAC region is projected to experience the highest CAGR during the forecast period 2026-2035 due to the rapid development of healthcare infrastructure, growing adoption of diagnostic technologies, and increasing healthcare spending in China, India, and Southeast Asia. Increasing awareness about infectious mononucleosis and availability of advanced diagnostic centers further add up to the impressive growth witnessed by the region.
China held around 34.60% share of the APAC market in 2025 owing to the development of its domestic diagnostics industry along with increasing investments in hospital and laboratory infrastructure. Other notable contributors to the growth of the region include India, Japan, and South Korea, the latter growing in popularity thanks to the growing adoption of point-of-care testing.
Middle East & Africa and Latin America Mononucleosis Diagnostic Market Insights
The ME&A region is showing consistent growth due to increasing investment in healthcare infrastructure in the Gulf states, backed by increasing government expenditure on healthcare and diagnostics laboratories. The Latin America region has benefited due to increasing healthcare access and growing investment in the private diagnostic laboratories within the region.
Saudi Arabia was the largest market for the ME&A region with a regional share of 24.60% in 2025 due to the presence of national healthcare infrastructure investment. Brazil had a regional share of 27.40% in 2025 for the Latin America region owing to the presence of increasing investment in diagnostic laboratories in the country.
Market Dynamics:
Growth Drivers: Rising Disease Awareness and Rapid Testing Demand Driving Market Growth
The Mononucleosis Diagnostic Market is being driven primarily by increasing prevalence of infectious mononucleosis, growing awareness among healthcare professionals and the public regarding the condition, and advancements in diagnostic technologies improving accuracy and speed of testing. Healthcare providers increasingly prioritize rapid, accurate diagnostic solutions given mononucleosis symptoms' overlap with other common infections such as streptococcal pharyngitis and influenza, requiring definitive differentiation for appropriate patient management.
Growing development of rapid point-of-care testing kits continues to expand diagnostic accessibility beyond traditional laboratory settings into urgent care, physician offices, and increasingly home-based testing environments. Rising integration of AI for diagnostic accuracy is further improving result interpretation and reducing operator-dependent variability. Expanding telehealth services supporting remote consultation are also reinforcing sustained diagnostic testing demand across increasingly decentralized healthcare delivery models.
Restraints: Diagnostic Specificity Issues and High Advanced Testing Costs Limiting Market Expansion
Even with positive fundamentals of demand side, the industry is still bound to some constraints that are linked to problems of diagnostic specificity on account of some rapid testing techniques that can lead to false negatives especially in the initial stage of the disease because of undetectably low levels of heterophile antibodies. Expensive nature of molecular and serological diagnostics still continues to impede adoption especially in the price sensitive emerging markets and healthcare infrastructure with low resources.
Difficulties in accessing the diagnostic technologies in poor countries still continues to hinder further growth of the industry, thereby creating a constant imbalance in terms of diagnostic capacity between the developed and the emerging market countries. Competition between the rising number of diagnostic firms is still increasing and has been reducing margins in most test categories.
Opportunities: Point-of-Care Innovation and Emerging Market Healthcare Investment Creating New Growth Avenues
Substantial opportunity exists in continued development of increasingly sophisticated point-of-care testing platforms capable of delivering laboratory-grade accuracy within minutes, directly addressing clinician demand for rapid, actionable diagnostic results. Manufacturers that successfully commercialize next-generation rapid testing technology stand to capture significant share of category growth as healthcare delivery continues shifting toward decentralized, near-patient testing models.
Growing healthcare infrastructure investment across emerging markets in Asia Pacific, the Middle East, and Latin America represents a further significant growth avenue, as rising healthcare expenditure and expanding diagnostic laboratory networks create substantial new demand for mononucleosis testing solutions. Continued expansion of telehealth integration and AI-driven diagnostic accuracy improvements are also opening new opportunity for manufacturers developing next-generation testing platforms.
Recent Developments:
-
2025: Abbott received Health Canada approval for its latest mononucleosis diagnostic assay, enabling commercial launch across Canadian healthcare facilities.
-
2024: BD (Becton, Dickinson and Company) received FDA clearance for a new mononucleosis rapid test, expanding rapid point-of-care testing options for clinicians.
-
2025: Abbott and Quidel Corporation expanded their Monospot product portfolios with multiplex lateral flow platforms detecting heterophile antibodies alongside bacterial infection markers.
-
2025: The FDA continued streamlining approval pathways for novel mononucleosis diagnostic devices, enabling manufacturers to more rapidly commercialize next-generation testing platforms.
Mononucleosis Diagnostic Market key players are:
-
Abbott Laboratories
-
Thermo Fisher Scientific Inc.
-
Danaher Corporation
-
Bio-Rad Laboratories, Inc.
-
Siemens Healthineers AG
-
bioMérieux SA
-
Quidel Corporation (QuidelOrtho)
-
Meridian Bioscience, Inc.
-
Sekisui Diagnostics, LLC
-
ELITechGroup
-
Cardinal Health, Inc.
-
Immunostics, Inc.
-
Hologic, Inc.
-
Revvity, Inc.
-
F. Hoffmann-La Roche Ltd
-
DiaSorin S.p.A.
-
Zeus Scientific, Inc.
-
Chembio Diagnostics, Inc.
-
OraSure Technologies, Inc.
-
Trinity Biotech plc
Mononucleosis Diagnostic Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.95 Billion |
| Market Size by 2035 | USD 4.46 Billion |
| CAGR | CAGR of 8.60% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Test Type (EBV Antibody Test, Monospot Test, Complete Blood Count Test, Molecular/PCR Test) • by Technology (Serological/Immunoassay, Molecular Diagnostics, Point-of-Care Testing) • by End User (Hospitals, Diagnostic Laboratories, Clinics, Home Care/POC) |
| Regional Analysis/Coverage | North America (US, Canada, Mexico), Europe (Eastern Europe [Poland, Romania, Hungary, Turkey, Rest of Eastern Europe] Western Europe] Germany, France, UK, Italy, Spain, Netherlands, Switzerland, Austria, Rest of Western Europe]), Asia Pacific (China, India, Japan, South Korea, Vietnam, Singapore, Australia, Rest of Asia Pacific), Middle East & Africa (Middle East [UAE, Egypt, Saudi Arabia, Qatar, Rest of Middle East], Africa [Nigeria, South Africa, Rest of Africa], Latin America (Brazil, Argentina, Colombia, Rest of Latin America) |
| Company Profiles | Abbott Laboratories, Thermo Fisher Scientific Inc., Danaher Corporation, Bio-Rad Laboratories, Inc., Siemens Healthineers AG, bioMérieux SA, Quidel Corporation (QuidelOrtho), Meridian Bioscience, Inc., Sekisui Diagnostics, LLC, ELITechGroup, Cardinal Health, Inc., Immunostics, Inc., Hologic, Inc., Revvity, Inc., F. Hoffmann-La Roche Ltd, DiaSorin S.p.A., Zeus Scientific, Inc., Chembio Diagnostics, Inc., OraSure Technologies, Inc., Trinity Biotech plc |
Frequently Asked Questions
The Mononucleosis Diagnostic Market is expected to grow at a CAGR of 8.60% from 2026 to 2035.
The Mononucleosis Diagnostic Market was valued at USD 1.955 Billion in 2025.
The market is driven by increasing prevalence of infectious mononucleosis, growing disease awareness, and advancements in diagnostic technologies improving accuracy and speed of testing.
The EBV Antibody Test segment dominated the Mononucleosis Diagnostic Market in 2025, accounting for approximately 38.60% market share.
The North America region dominated the Mononucleosis Diagnostic Market in 2025.
