
Mulching Materials Market Report Scope & Overview:
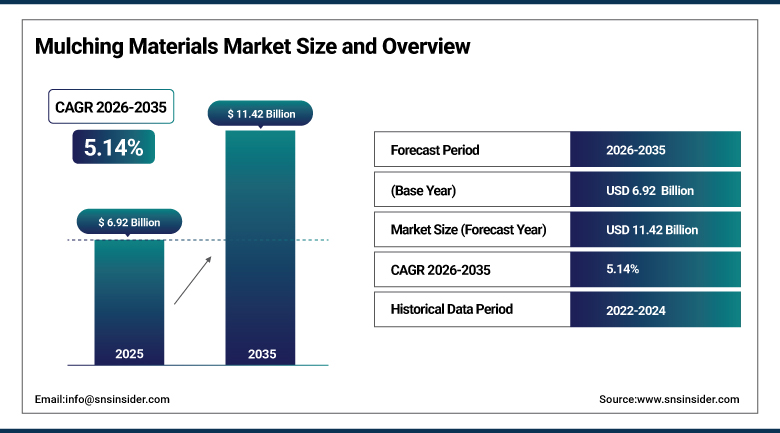
The Mulching Materials Market was valued at USD 6.92 Billion in 2025 and is expected to reach USD 11.42 Billion by 2035, growing at a CAGR of 5.14% from 2026-2035.
The Mulching Materials Market is witnessing growth due to the rising demand for water conservation agriculture, soil conservation, and increased efficiency in crop production. The use of mulching materials helps conserve soil moisture, regulate temperature, prevent weed growth, and reduce soil erosion, all of which ensure efficient farming practices. With the scarcity of water and changing weather conditions, there has been increased adoption of mulching practices among farmers in order to protect the crops as well as make efficient use of irrigation. The increase in horticultural activities, greenhouse farming, landscaping activities, and commercial farming is fueling the demand. There is widespread use of plastic mulches, but the use of biodegradable and organic mulches is also gaining traction.
⮞In December 2021, the Food and Agriculture Organization of the United Nations projected that global demand for greenhouse, mulching and silage films would rise by 50 percent between 2018 and 2030. This outlook points to sustained volume growth for film-based mulching materials across protected and open-field farming.
To Get more information Mulching Materials Market - Request Free Sample Report
Mulching Materials Market Trends
-
Certification under EN 17033 and new EU fertilizer rules is steering growers toward soil-biodegradable mulch films.
-
Paper and biomass-based films are gaining field trials as alternatives to conventional polyethylene.
-
China is promoting biodegradable film through pilots and targets while actual adoption remains gradual.
-
Online ordering and bulk landscape supply are widening mulch sales in North America.
-
PHA blends and fertilizer-releasing films are moving from laboratories into field trials.
U.S. Mulching Materials Market Outlook
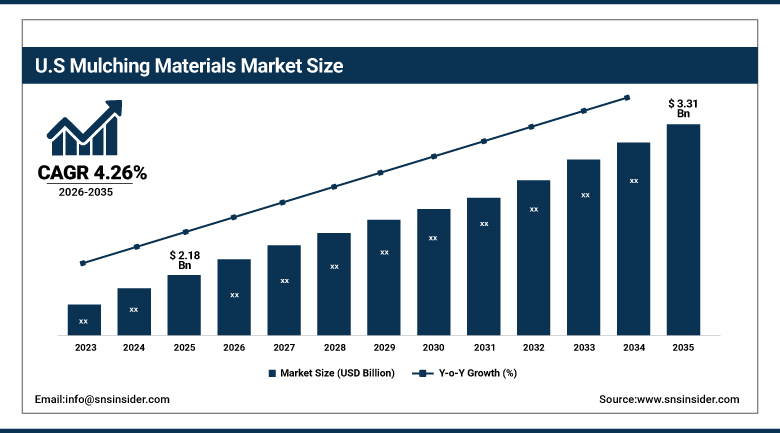
The U.S. Mulching Materials Market was valued at USD 2.18 Billion in 2025 and is expected to reach USD 3.31 Billion by 2035, growing at a CAGR of 4.26% from 2026-2035.
The U.S. Mulching Materials Market grows on steady residential landscaping demand and rising use of films in specialty crop production. Homeowners buy bagged and bulk wood mulch each spring for beds and slopes. Landscape contractors specify bark and compost blends for commercial sites and public projects. Vegetable and berry growers rely on polyethylene films to conserve water and suppress weeds. Disposal costs for used film are pushing growers toward soil-biodegradable options. Online ordering and truckload delivery are widening access for small buyers. Sawmills and tree care firms keep wood residue supply stable across most states. Local yards deliver loads within a short haul, which holds delivered prices in check.
⮞For example, the U.S. Mulch & Soil Council reported in February 2026 that 54 percent of surveyed sellers saw bulk mulch sales grow during the first half of 2025. The result confirms firm demand for landscape-grade products and supports the steady U.S. growth outlook.
Mulching Materials Market Segment Analysis
-
By Type, the Organic Mulch segment dominated the Mulching Materials Market with approximately 55.27% share in 2025, while the Inorganic Mulch segment is the fastest growing with a CAGR of approximately 5.64%.
-
By Application, the Agriculture segment dominated the Mulching Materials Market with approximately 46.97% share in 2025, while the Landscaping segment is the fastest growing with a CAGR of approximately 5.54%.
-
By Material, the Wood Chips segment dominated the Mulching Materials Market with approximately 32.80% share in 2025, while the Plastic segment is the fastest growing with a CAGR of approximately 6.64%.
By Type, Organic Mulch Dominates the Mulching Materials Market and Inorganic Mulch Grows Fastest
Organic mulch holds its lead because it is cheap near the point of use and easy to buy in bulk. Sawmills, tree care firms and composters supply residues that landscapers spread on beds, slopes and orchard rows. Homeowners associate bark and wood chips with moisture retention and a finished look, which keeps repeat purchases steady each spring. Straw serves vegetable and strawberry growers who want a biodegradable cover without removal labor. Compost adds nutrients as it breaks down and supports soil health programs on municipal and commercial grounds. These benefits make it the default choice across residential and public projects.
Inorganic mulch is gaining speed as commercial growers adopt films that warm the soil, block weeds and cut irrigation needs. Black polyethylene remains the workhorse for vegetables and berries while soil-biodegradable films answer rising disposal costs and tighter rules on plastic residue. Recycled rubber and stone find steady use in playgrounds and decorative landscapes where durability matters more than nutrient value. Producers are also developing thinner films that lay faster on mechanical equipment. Because these products outlast bark or straw they appeal to buyers focused on lifetime cost rather than purchase price alone.
⮞In November 2025, Novamont received a conformity certificate under EU Fertilising Products Regulation 2019/1009 for its Mater-Bi mulch film. The certification gives soil-biodegradable film a recognized route as a soil improver and strengthens the case for inorganic mulch products that leave no residue.
By Application, Agriculture Dominates the Mulching Materials Market and Landscaping Grows Fastest
Farm use leads because mulch pays back inside a single season on high-value crops. Vegetable, strawberry and orchard growers apply films and straw to hold soil moisture, stabilize root-zone temperature and reduce herbicide passes. Greenhouse and tunnel operators lay mulch beneath drip lines to improve water use efficiency. Public horticulture programs in several countries subsidize film purchases. Rising labor costs also favor mulch since one installation replaces repeated hand weeding. Large contract farms buy by the roll or truckload, which supports volume and stable supplier relationships. Orchard and vineyard owners add wood chips to cut summer heat stress at the root zone.
Landscaping is accelerating as urban development and home improvement spending add planted area. Cities specify mulch to cut irrigation on parks and road verges and to suppress weeds without chemicals. Property managers refresh beds on annual contracts, which creates recurring orders. Playground and recreational surfacing programs add bark and rubber products that meet impact safety requirements. Colored and treated wood mulches are marketed for curb appeal and reach buyers through garden centers and online platforms. Climate adaptation plans also encourage moisture-saving ground cover in drought-prone cities.
⮞In November 2024, the University of Massachusetts Lowell received a four-year USDA grant of USD 744,000 to develop fully degradable mulch films that release fertilizer such as urea as they break down. A successful design would let growers combine weed control and nutrition in one field pass.
By Material, Wood Chips Dominate the Mulching Materials Market and Plastic Grows Fastest
Forestry and tree care operations generate a steady stream of low-cost residue, which explains the top position of wood chips. Processors grind, screen and sometimes dye the chips before bagging them or loading trucks for landscapers. The product suits paths, tree rings and ornamental beds where bulk coverage matters more than precision. Slow decay cuts replenishment frequency compared with straw or fine compost. Local sourcing limits freight cost and appeals to sustainability-minded customers. Municipal chipping programs and storm debris recycling also feed supply during peak seasons. Chipped hardwood and cedar blends command premiums in retail bags.
Plastic films expand fastest as protected cultivation spreads and growers chase higher yields per hectare. Polyethylene and polylactic acid blends are laid by tractor-drawn equipment that also installs drip tape. Film color can be tuned to warm soil or reflect light, which adds agronomic value beyond weed control. Biodegradable formulations are widening the addressable base because farmers avoid removal and landfill fees. Resin price swings still influence buying decisions but long-term contracts with film converters help smooth costs. Thinner gauges and wider rolls also lower material use per hectare.
⮞In April 2024, BASF announced that mulch films made from its ecovio M 2351 grade are completely degraded by soil microorganisms and are certified under the EN 17033 standard. Because such film can be plowed in after harvest it removes retrieval cost and supports plastic-based mulch where disposal is restricted.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
86.00 |
|
Europe |
United Kingdom |
26.00 |
|
Asia Pacific |
China |
44.00 |
|
Latin America |
Brazil |
52.00 |
|
Middle East & Africa |
United Arab Emirates |
34.00 |
North America Mulching Materials Market Insights
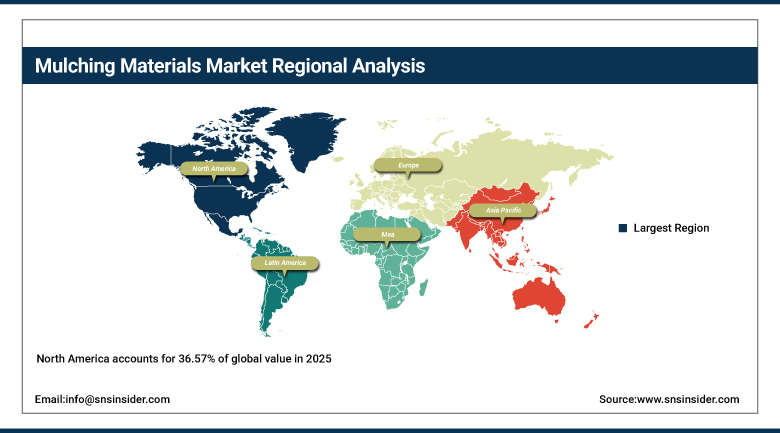
North America accounts for 36.57% of global value in 2025 on the strength of a mature landscaping economy and large specialty crop acreage. The United States anchors regional demand through home improvement chains and professional landscape contractors. Canadian greenhouse and nursery producers add steady volume. Bark, cedar and colored wood mulch dominate shelf space while film use concentrates in vegetable, berry and melon fields. Warm growing regions in the south and west drive most film use in vegetables and berries. Homeowner spending on yards and outdoor living keeps replenishment cycles short.
Cost and policy pressures shape the next phase. Growers face rising fees to remove and dispose of used film and universities are testing biodegradable alternatives under federal research funding. Wood waste recycling programs are enlarging the supply of chipped material for landscape buyers. Retailers are also expanding online mulch calculators and delivery tools that help customers size orders. These shifts favor suppliers able to serve both bulk and bagged formats. Bulk yards and garden centers also invest in screening and coloring lines that raise the value of each ton of residue.
⮞In May 2025, Washington State University Extension estimated that U.S. agriculture uses about 1 million tonnes of polyethylene mulch each year. The volume shows the scale of film demand across North America and the size of the replacement opportunity for biodegradable grades.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Mulching Materials Market Insights
Europe pairs a large garden and landscape market with the most developed rules for agricultural plastics. Greenhouse belts in Spain and Italy use film mulch intensively for vegetables and fruit. Northern buyers in the United Kingdom and Germany purchase bark and compost through garden centers and landscape merchants. Producer responsibility and waste rules raise the cost of conventional film disposal, which shifts procurement toward soil-biodegradable grades. Landscape architects increasingly favor bark and wood chip covers that reduce irrigation and herbicide use in public spaces.
Common Agricultural Policy funding for eco-schemes and organic conversion supports spending on sustainable ground cover. European resin makers and film converters are close to growers, which speeds field testing of paper and starch-based products. Test standards give buyers a common benchmark when they compare products from different suppliers. Waste collection networks for farm plastics are also expanding across member states. Competition from paper mulch and from mechanical weeding keeps pricing disciplined across the region. Retailers also promote peat-free and locally sourced mulch products to environmentally aware gardeners.
⮞In November 2024, the European Commission brought Delegated Regulation (EU) 2024/2787 into force and added mulch films to Component Material Category 9 of the Fertilising Products Regulation. The change opens a formal pathway for biodegradable mulch film to be sold as an EU fertilizing product component.
Asia Pacific Mulching Materials Market Insights
Asia Pacific is projected to expand at a CAGR of 6.74% over 2026-2035, the fastest pace among regions. China is the anchor market and the region also leads global mulch film consumption. India is widening plastic mulching for horticulture under state-supported schemes. Japan and South Korea favor high-quality biodegradable films for greenhouse crops. Southeast Asian vegetable and plantation growers are adopting mulch as labor becomes scarcer and rainfall less reliable. Rice-wheat rotations and orchards in South Asia also use straw and crop residues as low-cost cover.
Government programs are central to growth, yet adoption of biodegradable film still lags behind official targets in China. Cheaper polyethylene film remains the default for smallholders who weigh price above residue risk. Local resin plants and film converters are scaling output to lower the price gap. Australia contributes demand from orchards and vineyards that use organic mulch for water saving. Provincial extension services in China also train farmers to collect used film and test degradable alternatives. These factors keep the regional outlook strong across both farm and landscape uses.
⮞Science and Technology Daily reported in March 2026 that agricultural film in China now covers more than 270 million mu of farmland, equal to roughly 18 million hectares. That coverage makes China the anchor of regional demand and the main target for biodegradable substitution programs.
Latin America and Middle East & Africa Mulching Materials Market Insights
Latin America benefits from export-oriented fruit and vegetable production in Brazil and Mexico where growers use mulch films to protect berries and tomatoes and to save water. Chile and Peru add demand from orchards and table grapes. Local converters and distributors supply silver-black and black-black films alongside biodegradable options. Garden retail is smaller but growing in Brazilian cities where new housing adds landscaped areas. Governments and exporters encourage water-saving practices as droughts recur. Currency swings and import costs for resin still shape pricing across the region.
Middle East & Africa demand rises from water-scarce farming and fast-growing city landscaping. Gulf states use stone and wood mulch in public gardens and along roadsides while greenhouse projects in the United Arab Emirates and Saudi Arabia adopt plastic film for drip-irrigated crops. Egypt and South Africa add vegetable and citrus demand. Drought recurrence and desalinated water costs make moisture-retaining ground cover attractive to farms and city planners alike. Limited local manufacturing keeps the region dependent on imported films and chipped material.
Market Dynamics
Growth Drivers: Water scarcity and public support for soil-friendly farming are raising mulch adoption worldwide.
Mulch reduces evaporation from the soil surface and lets farms hold yields with less irrigation. Growers in drought-prone regions apply films and organic cover to protect root zones and stabilize soil temperature. Weed suppression replaces repeated herbicide passes and hand labor. Protected cultivation adds demand because greenhouse and tunnel crops pair mulch with drip lines. Landscape managers apply the same logic to parks and road verges where irrigation budgets are tight. Yield protection is especially valuable for fruit and vegetable crops that command premium prices.
Public programs reinforce this demand. Governments subsidize film purchases and recycling pilots and give priority to biodegradable grades that avoid retrieval cost. Disposal fees for conventional film push farms toward alternatives. Sustainability targets among food retailers and garden chains also encourage suppliers to document recycled content and soil safety. Labor shortages in many farming regions raise the value of products that reduce manual weeding. Extension services train growers to lay films correctly. These forces combine to keep mulch purchasing a recurring line item in farm and municipal budgets.
⮞In March 2022, China's Ministry of Agriculture and Rural Affairs launched film recycling pilots with priority support for fully biodegradable film and a 2022 target of 5 million mu. The program signals durable official backing for mulch adoption in the largest film-consuming country.
Restraints: Higher prices for biodegradable films and uneven field degradation are slowing the shift away from polyethylene.
Biodegradable films cost more than polyethylene and often need adjusted installation settings. Resin prices for both conventional and bio-based polymers swing with feedstock markets and freight, which complicates season-ahead contracts. Installers need training to handle new film types without tears. Degradation speed varies with soil temperature, moisture and microbial activity, so growers worry about films that break down too early or too late. Counterfeit thin films in some Asian markets also erode confidence in quality claims. Warranty claims after failed seasons make some distributors cautious about stocking new grades.
Substitutes add pressure. Herbicides and mechanical cultivation remain cheaper for many field crops while paper and spray-on covers compete for premium vegetable plots. Certification processes take time and cost money for small producers. Used polyethylene collection is labor intensive and dirty, but growers often accept it rather than pay more for new materials. Fragmented regional rules on biodegradability claims also create compliance work for exporters. Buyers in cost-sensitive markets therefore delay conversion. These frictions keep conventional film in a dominant position despite regulatory encouragement.
⮞In September 2023, the USDA National Organic Program told its advisory board that biodegradable mulch films with 80 percent biobased content were not available. Organic growers therefore still need 100 percent biobased products, which limits supplier choice.
Opportunities: Certified biodegradable films and fertilizer-carrying designs are opening new product lines for producers.
Regulatory recognition turns biodegradable mulch film from an experiment into a standard catalog item. Producers that secure certificates can sell into organic, specialty crop and public landscaping programs. Smallholder horticulture in Africa, South and Southeast Asia and Central America is a large unserved base that responds to low-cost starter products. Bundling mulch with drip tape and planting services creates higher-value offers for protected cultivation. Municipal procurement for parks and playgrounds rewards suppliers that offer certified recycled content. Online storefronts let small producers reach these buyers without large dealer networks.
Material innovation adds more routes. Recycled rubber mulch converts waste tires into playground and landscape products. Closed-loop collection programs let converters recover used film and sell recycled grades. Carbon credit schemes and sustainability premiums can offset the higher cost of bio-based resin. Fertilizer-releasing and sensor-compatible films point to precision farming uses where mulch becomes an active input instead of a passive cover. Contract manufacturing for private-label retail brands gives smaller converters a route to scale. Training programs for installers can also lift trial rates.
⮞In April 2025, AIMPLAS reported under the COM4PHA project that PHA bioplastics can be applied to mulch films where their barrier and antimicrobial properties maintain crop quality. The finding supports a new high-performance biodegradable film category.
Recent Developments
-
In January 2025, RKW Group presented PRO-TECH BIO Carrot at Fruit Logistica, a film that combines perforated and mulch functions for carrot growers. The launch shows film makers tailoring mulch products to specific crops and installation practices.
-
In April 2026, Green Science Alliance announced a biodegradable mulch film based on plant biomass that contains about 82 percent biomass and degrades within two to six months. The product moves mulch film toward higher renewable content and flexible degradation timelines.
-
In June 2026, CTK Bio Canada launched Earth Edition Home Compostable Paper Mulch Film for agricultural use. The film laminates paper with home compostable technology and offers degradation timelines customized to crop cycles. It adds a paper-based option for growers avoiding plastic residues.
-
In June 2026, NUREL introduced two INZEA biopolymer grades, F08M and F09M, for mulch films certified to EN 17033 and OK biodegradable SOIL. The grades give film converters resin options that meet leading soil-biodegradability benchmarks.
Mulching Materials Market Key Players
-
Novamont
-
CTK Bio Canada
-
Oerlemans Plastics
-
Ginegar Plastic Products
-
Solplast
-
Jolly Gardener
Mulching Materials Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 6.92 Billion |
| Market Size by 2035 | USD 11.42 Billion |
| CAGR | CAGR of 5.14% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Organic Mulch and Inorganic Mulch) • By Application (Agriculture, Horticulture, Landscaping, and Others) • By Material (Wood Chips, Bark, Compost, Straw, and Plastic) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Novamont, CTK Bio Canada, RKW Group, Oerlemans Plastics, Ginegar Plastic Products, BioBag International, Solplast, Jolly Gardener |

Frequently Asked Questions
Key players include Novamont, RKW Group, Achilles Corporation, Ginegar Plastic Products and BioBag International among others.
Certified biodegradable films, fertilizer-releasing designs, smallholder horticulture and recycling-led closed-loop programs offer the strongest opportunities for producers.
Water scarcity and the need to protect yields with less irrigation and less labor are the major growth factors, supported by public programs that favor biodegradable films.
The Organic Mulch segment dominated the Mulching Materials Market with approximately 55.27% share in 2025 because wood residues, straw and compost are low-cost and widely available for gardens, farms and public landscapes.
North America dominated the Mulching Materials Market in 2025 with approximately 36.57% share because of its large landscaping economy and well-developed retail and online mulch distribution.
