
Multi-Layer Cryogenic Insulation Market Report Scope & Overview:
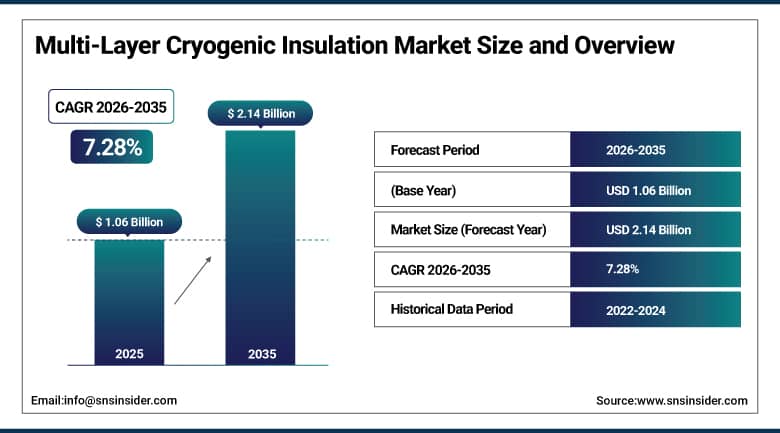
The Multi-Layer Cryogenic Insulation Market size was valued at USD 1.06 Billion in 2025 and is expected to reach USD 1.14 Billion in 2026, rising to USD 2.14 Billion by 2035. The market is forecast to expand at a CAGR of 7.28% during 2026–2035. Multi-layer insulation is a stack of thin reflective films separated by low-conductivity spacers that blocks radiant heat inside vacuum-jacketed tanks, pipes and spacecraft. Growth is supported by liquefied natural gas and hydrogen infrastructure, space launch activity and the need to cut boil-off losses in the storage and transport of cryogenic liquids.
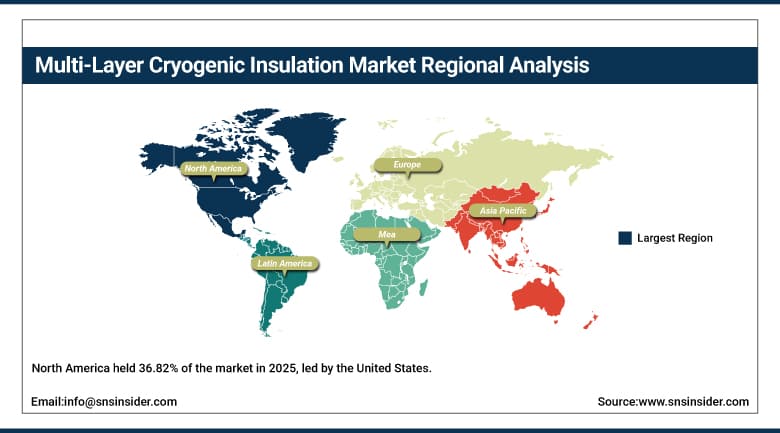
North America accounted for the largest share of the market, at 36.82% in 2025, because it combines large space programs, liquefied natural gas export terminals and a deep base of cryogenic equipment makers. Europe follows on the strength of industrial gas groups and aerospace suppliers, while Asia Pacific is the fastest growing region as China, Japan, South Korea and India build liquefied natural gas, hydrogen and launch capacity. Latin America and Middle East & Africa remain smaller markets, with demand tied to gas projects and industrial gas distribution. Growth in both smaller regions depends on project timing.
To Get More Information On Multi-Layer Cryogenic Insulation Market - Request Free Sample Report
Key Report Takeaways
-
By material, polymer-based insulation held 44.63% in 2025, while composite insulation is the fastest growing.
-
By application, cryogenic storage held 52.47% in 2025, while cryogenic transportation is the fastest growing.
-
By end use, aerospace held 31.84% in 2025, while energy is the fastest growing.
-
By thickness, medium constructions held 40.26% in 2025, while thin constructions are the fastest growing.
-
By region, North America held 36.82% in 2025, while Asia Pacific is the fastest growing.
Market Trends and Insights
Tank builders are moving from hand-wrapped blankets to pre-cut, pre-assembled insulation kits and automated winding, which cut labor hours and reduce the gaps and compression points that degrade thermal performance. Suppliers now offer quality documentation for each installed layer, and customers in space and hydrogen programs increasingly request it.
Liquid hydrogen and liquid helium storage need lower heat leak than liquefied natural gas, so designers are testing thinner spacers, perforation patterns that speed up evacuation and hybrid systems that combine multi-layer insulation with aerogel or perlite. Suppliers that can prove performance under vibration and thermal cycling are winning longer contracts.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Liquefied natural gas and hydrogen infrastructure |
+2.71% |
North America and Asia Pacific |
Short term (2 years or less) |
|
Space launch and aerospace programs |
+2.18% |
North America and Europe |
Medium term (2 to 4 years) |
|
Industrial gas, helium and research cryogenics |
+1.46% |
Global |
Medium term (2 to 4 years) |
|
Boil-off reduction and energy efficiency |
+1.12% |
Global |
Long term (4 years or more) |
|
Lightweight materials and automated installation |
+0.74% |
Global |
Long term (4 years or more) |
Liquefied Natural Gas and Hydrogen Infrastructure
Liquefied natural gas trade is expanding, and every new liquefaction train, carrier, storage tank and truck needs insulation that limits heat leak. The U.S. Energy Information Administration reported that the United States accounted for 26.00% of global liquefied natural gas exports in 2025, up from 21.00% in 2024. Hydrogen liquefaction and storage projects add demand for the highest-performance insulation, because liquid hydrogen boils at a far lower temperature and loses value quickly when heat gets in. Terminal operators also upgrade existing storage and transfer systems, which adds retrofit demand.
Space Launch and Aerospace Programs
Rockets store liquid oxygen, liquid hydrogen and methane, and spacecraft and satellites rely on multi-layer blankets to hold stable temperatures in orbit. NASA completed the crewed Artemis II lunar flyby in April 2026, and lunar, commercial launch and satellite programs continue to widen the order book. Weight is critical in flight hardware, so thin, lightweight multi-layer blankets are preferred over bulkier insulation, and qualification requirements keep suppliers close to their customers. Smaller launch providers entering the market add buyers that need qualified blankets on short schedules.
Industrial Gas, Helium and Research Cryogenics
Industrial gas groups operate large fleets of vacuum-insulated tanks, trailers and cylinders for nitrogen, oxygen, argon and helium, and they replace and refurbish this equipment on regular cycles. Medical imaging magnets, quantum computers, particle accelerators and fusion research all need liquid helium or other cryogens at stable temperatures. These users demand reliable insulation and add steady demand that is largely independent of energy cycles. Hospitals replacing magnetic resonance systems and laboratories building quantum facilities add further orders for insulated cryostats and transfer lines.
Boil-Off Reduction and Energy Efficiency
Every unit of cryogenic liquid that boils off is lost product and extra energy spent on reliquefaction. Operators of liquefied natural gas carriers, bunkering vessels and hydrogen terminals are specifying lower heat leak targets to protect cargo value and meet emissions rules. Better insulation cuts these losses over the life of the asset, so buyers accept higher initial cost for advanced multi-layer designs. Shipping companies using liquefied gas as fuel also carry the cost of lost cargo, so they focus on every source of heat entering the tank and its piping.
Lightweight Materials and Automated Installation
New films, coatings and spacer materials improve reflectivity and handling, while automated winding and laser cutting raise consistency and shorten delivery times. Lighter systems reduce the mass of mobile tanks and vehicle-mounted storage, which increases payload and range. These advances also widen the pool of builders able to use multi-layer insulation reliably, including smaller firms entering hydrogen and helium storage. Suppliers that invest in these methods can bid on larger programs with tighter schedules, and their customers gain traceable records of how each blanket was built.
Restraints Impact Analysis
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
High installation cost and sensitivity to workmanship |
-2.38% |
Global |
Short term (2 years or less) |
|
Slow progress of hydrogen projects |
-1.86% |
North America and Europe |
Medium term (2 to 4 years) |
|
Competition from alternative insulation systems |
-1.24% |
Global |
Medium term (2 to 4 years) |
|
Specialist skills and limited qualified suppliers |
-0.67% |
Global |
Long term (4 years or more) |
High Installation Cost and Sensitivity to Workmanship
Multi-layer insulation performs well only when layers are installed without compression, tears or thermal shorts, and the work is slow and labor intensive. A small error in wrapping or sealing can raise heat leak sharply, which makes quality control and inspection costly. Buyers on tight budgets often choose simpler insulation, especially for large stationary tanks where weight matters less. Skilled installers are scarce, and rework after a failed vacuum test adds cost and delays tank deliveries by weeks or even months.
Slow Progress of Hydrogen Projects
Many planned hydrogen liquefaction and storage projects have been delayed or cancelled. The International Energy Agency reported in its Global Hydrogen Review 2026 that announced low-emissions hydrogen production projects for 2030 fell to 27 million tonnes, and that only 300 kilotonnes per year of new capacity reached final investment decision since the previous edition. Weak project pipelines slow orders for premium insulation systems. Developers and lenders wait for firm offtake agreements before ordering equipment, which keeps order books for insulation uneven.
Competition from Alternative Insulation Systems
Perlite, aerogel blankets, foam and glass fiber are used in many tanks and pipes, and they are cheaper or easier to install in some designs. Advances in aerogel and vacuum insulated panels also narrow the performance gap for certain applications. Multi-layer insulation keeps its edge where weight and ultra-low heat leak count, but suppliers must keep proving value against simpler alternatives. Qualified aerogel products from specialty chemical groups continue to improve, and some tank builders prefer a single supplier for the whole insulation package.
Specialist Skills and Limited Qualified Suppliers
Few firms have the equipment, clean assembly space and trained staff to produce space-grade and hydrogen-grade blankets. Customers in aerospace and research require lengthy qualification, test data and traceability, which slows entry of new suppliers. Capacity tends to be tight when large programs ramp up, and lead times can stretch for projects that need custom shapes. Small suppliers also need working capital to carry specialty film inventories, and a few failed audits can remove them from approved vendor lists for years.
Multi-Layer Cryogenic Insulation Market Segment Analysis
By Material, Polymer-Based Insulation Dominates Multi-Layer Cryogenic Insulation Market; Composite Insulation to Register Fastest Growth.
Polymer-based insulation accounts for 44.63% of the market in 2025 because aluminized polyester and polyimide films with glass fiber or polyester net spacers offer a proven balance of reflectivity, weight and cost. These materials are available from many suppliers, are easy to cut and wrap, and have long records in tanks, vacuum lines and spacecraft. Their familiarity helps buyers qualify designs quickly. Lower film prices than specialty alternatives also help them win industrial gas vessel and transfer line contracts.
Composite insulation is projected to grow at a CAGR of 8.64% during 2026–2035. Systems that combine reflective layers with aerogel, ceramic or fiber elements deliver lower heat leak in less thickness and survive higher temperature swings. Hydrogen storage, launch vehicles and compact helium systems favor these designs, and new coatings and spacer materials are widening the range of qualified products. Pilot lines already supply qualified composite stacks to launch vehicle and hydrogen tank programs, and customers cite lower life-cycle cost.
By Application, Cryogenic Storage Dominates Multi-Layer Cryogenic Insulation Market; Cryogenic Transportation to Register Fastest Growth.
Cryogenic storage holds a 52.47% share in 2025 because large liquefied natural gas tanks, industrial gas vessels, hydrogen spheres, research dewars and rocket propellant tanks all depend on high-performance insulation. These assets are long lived and need regular upgrades, and the number of storage sites keeps rising with gas trade and industrial output. Storage buyers value low boil-off, which favors multi-layer designs. Vacuum-jacketed lines and tanks at liquefied natural gas terminals and gas plants add large insulated areas.
Cryogenic transportation is expected to expand at a CAGR of 8.93% from 2026 to 2035. Liquefied natural gas trucks and carriers, hydrogen tube trailers, liquid helium containers and bunkering vessels all need lightweight insulation to maximize payload and cut losses in transit. Fleet growth in Asia Pacific and Europe, and the move to cleaner marine fuels, raise orders. Cryogenic road tankers and ISO containers are being fitted with improved blankets to reduce venting on long routes, which shippers value.
By End Use, Aerospace Dominates Multi-Layer Cryogenic Insulation Market; Energy to Register Fastest Growth.
Aerospace accounts for 31.84% of the market in 2025. Launch vehicles, satellites, space telescopes and crewed spacecraft use multi-layer blankets to manage heat in vacuum, and the price per unit area is high because of exacting qualification. Government space agencies and a growing set of commercial launch companies place repeat orders, and each new program usually requires custom shapes and test data. Defense space programs and national agencies also fund continuous research that keeps demand for qualified suppliers high.
Energy is projected to register a CAGR of 9.12% during 2026–2035. Liquefied natural gas liquefaction, shipping and receiving terminals, hydrogen liquefaction and storage, and power-sector cryogenics all need insulation that limits heat leak. Buyers in these projects increasingly specify multi-layer systems for transfer lines and mobile storage, and large capital programs in the United States, Qatar and Asia add volume. Floating liquefied natural gas units, bunkering vessels and hydrogen export studies in Asia and the Middle East add insulation packages.
By Thickness, Medium Constructions Dominate Multi-Layer Cryogenic Insulation Market; Thin Constructions to Register Fastest Growth.
Medium constructions hold a 40.26% share in 2025 because they strike a balance between heat leak, vacuum space available in the tank wall and installation effort. Most industrial gas vessels, mobile tanks and transfer lines are designed around this range, and standard layer counts are well documented. Builders can source materials from several suppliers, which keeps costs manageable for volume programs. Standard layer counts also make it simple to compare bids, so purchasing teams often default to this range.
Thin constructions are expected to grow at a CAGR of 8.21% during 2026–2035. Space hardware, compact helium systems, quantum computing cryostats and vehicle-mounted hydrogen tanks cannot spare much wall space, so designers favor thin, high-reflectivity stacks. Better spacer materials and tighter layer control now allow these stacks to meet demanding heat leak targets. Suppliers are developing ultra-thin films with laser perforation and low-outgassing spacers to meet tight heat leak targets. Customers in space and quantum computing are early adopters.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
87.64% |
|
Europe |
Germany |
26.73% |
|
Asia Pacific |
China |
41.58% |
|
Middle East & Africa |
Qatar |
35.92% |
|
Latin America |
Brazil |
46.35% |
North America Multi-Layer Cryogenic Insulation Market
North America held 36.82% of the market in 2025, led by the United States. The U.S. market was valued at USD 342.05 Million in 2025 and is expected to register a CAGR of 6.94% during 2026–2035. The country hosts government space programs, commercial launch companies, liquefied natural gas export terminals and the largest industrial gas groups, which together create steady and varied demand for insulation. Demand from defense and civil space agencies is steady, and procurement rules favor suppliers with long flight heritage.
Canada adds demand from natural gas projects, research facilities and aerospace suppliers, while Mexico provides growing industrial gas distribution and equipment manufacturing. Federal funding for hydrogen hubs and space exploration, together with defense procurement of cryogenic systems, supports orders for high-performance blankets. National laboratories and universities operate large cryogenic research facilities, and the semiconductor and quantum computing sectors are adding dilution refrigerators and helium handling systems. These users value reliable delivery and documented performance, and they often buy small volumes of custom blankets at high prices per unit.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Multi-Layer Cryogenic Insulation Market
Asia Pacific accounted for 28.46% of the market in 2025 and is the fastest growing region, with a projected CAGR of 8.71% over 2026–2035. China is the largest country, supported by a large cryogenic equipment industry, expanding liquefied natural gas imports and a fast-growing launch and satellite sector. Japan and South Korea add shipbuilding of liquefied gas carriers and hydrogen programs. Shipyards and equipment makers in the region build many liquefied gas carriers, tanks and cryogenic trailers, which creates local demand for insulation supply.
India is building import terminals, industrial gas capacity and a national space program, and Australia contributes liquefied natural gas exports and helium projects. Regional manufacturers are moving up from standard tank insulation to space-grade and hydrogen-grade products, which broadens the supplier base and raises local demand. National space agencies in China and India, and private launch companies in several countries, are increasing launch cadence. Government support for hydrogen mobility in Japan and South Korea adds liquid hydrogen trucks and refueling stations, which need compact insulated storage.
Europe Multi-Layer Cryogenic Insulation Market
Europe accounted for 24.17% of the market in 2025, with Germany as the leading country. Industrial gas groups, cryogenic tank makers and aerospace suppliers in Germany, France and Italy buy large volumes of insulation, and the European space sector is a major buyer of spacecraft blankets. Strong research infrastructure adds demand from accelerators and fusion projects. Large research projects such as particle accelerators and fusion devices, together with regional launch and satellite programs, keep demand for custom blankets high, and several suppliers hold space agency qualifications.
The United Kingdom, the Netherlands and Norway add demand from liquefied natural gas terminals, shipping and hydrogen pilot projects. Regional emissions rules push shipowners and operators toward lower boil-off systems, and cooperation among space agencies and manufacturers keeps qualification pipelines active. Spain and the Nordic countries add industrial gas and shipping demand, while Poland and Turkey are building liquefied natural gas import terminals. Regional programs for hydrogen valleys and green shipping corridors are creating new storage and transport projects, although permitting and funding timelines remain uneven across countries.
Latin America Multi-Layer Cryogenic Insulation Market
Latin America held 5.18% of the market in 2025. Brazil leads, supported by industrial gas distribution, an aerospace manufacturing base and liquefied natural gas import terminals. Argentina has growing natural gas liquefaction ambitions in its shale basins, which could raise demand for storage and transfer insulation in the coming years. Brazilian aircraft makers and a small satellite sector use multi-layer blankets, and industrial gas companies operate cryogenic plants in several large cities. Natural gas import terminals along the coast add demand for insulated transfer systems.
Mexico, Chile and Colombia add demand from industrial gases, mining and medical uses. Most high-performance insulation is imported, and local activity centers on refurbishment and tank assembly. Project delays and currency swings remain constraints, but gas infrastructure investment should lift volumes. Peru and Trinidad and Tobago host liquefied natural gas export facilities, and regional mining and medical sectors buy liquid oxygen and nitrogen. Projects remain few and are exposed to financing conditions, but each new terminal or plant adds a lasting need for insulation and spare parts.
Middle East & Africa Multi-Layer Cryogenic Insulation Market
Middle East & Africa held 5.37% of the market in 2025. Qatar leads regional demand through its large liquefied natural gas production and shipping fleet, and the United Arab Emirates and Saudi Arabia are investing in hydrogen, helium and industrial gas capacity. These projects require insulation for storage, loading lines and transport equipment. State energy companies are expanding liquefaction capacity and building large fleets of liquefied gas carriers, which require insulated transfer lines and storage tanks supplied by major international contractors.
Oman and Egypt add liquefied natural gas capacity, and South Africa has an industrial gas market and a developing space program. Most insulation is imported, but regional fabrication of tank systems is growing. Expansion of export terminals and hydrogen ambitions should keep the region on a steady upward path. Helium production in Qatar and Algeria supplies global markets and requires cryogenic handling. Israel and Egypt add research and aerospace demand, while African industrial gas distribution is growing slowly from a small base as mining and healthcare expand.
Competitive Landscape
The Multi-Layer Cryogenic Insulation Market is fragmented. Specialty materials groups, aerospace fabricators, industrial gas companies with in-house insulation work and small custom blanket makers all compete. Competition centers on thermal performance, qualification records, delivery time and the ability to supply complete kits for specific tank designs.
Companies pursue long-term supply agreements with tank builders and space contractors, investments in automated cutting and winding, and development of composite and thin constructions. Vertical integration by cryogenic equipment groups is also reshaping the field as they bring more insulation work in-house.
Multi-Layer Cryogenic Insulation Market Industry Leaders
1. Alkegen: U.S. specialty materials group offering the CryoTherm family of cryogenic insulation.
2. Quest Thermal Group: U.S. maker of multi-layer insulation for space and cryogenic systems.
3. Aerospace Fabrication & Materials: U.S. fabricator of multi-layer insulation blankets for spacecraft.
5. Air Liquide: French industrial gas group with cryogenic insulation systems through its engineering and technologies arm.
Companies Covered in this Report
-
Alkegen
-
Quest Thermal Group
-
Aerospace Fabrication & Materials
-
Air Liquide
-
Web Industries
-
Frako-Term
Recent Industry Developments
-
July 2025: Baker Hughes agreed to acquire Chart Industries, a leading maker of vacuum-insulated cryogenic storage and transport equipment, for about USD 13.60 Billion.
-
January 2026: Air Products announced more than USD 140.00 Million in NASA contracts to supply liquid hydrogen to Kennedy Space Center, Cape Canaveral Space Force Station and other NASA facilities.
Scope and Research Methodology
This study estimates the Multi-Layer Cryogenic Insulation Market for 2025 as the base year and forecasts it through 2035. The scope covers multi-layer insulation systems made of reflective films and spacers, supplied as blankets, kits and pre-assembled wraps for cryogenic storage tanks, transfer lines, transport equipment, spacecraft and scientific instruments. Values are reported in USD at the point of sale by insulation suppliers to tank builders, space contractors and research institutions. Bulk insulation such as perlite and foam, and the cryogenic tanks themselves, are outside the scope. Segmentation covers material, application, end use and thickness, and regional analysis covers five regions and major countries. Revenue is recorded in the year of sale, and intermediate transfers between affiliated fabricators are excluded to avoid double counting.
Secondary research included company annual reports, investor presentations and filings, space agency and energy regulator publications, standards bodies, patent filings and peer-reviewed technical papers. Primary research consisted of structured interviews with executives, design engineers, procurement heads, tank builders and space contractors across the value chain. These inputs were used to validate material prices, layer counts, project timelines and the share of each material and application. Expert interviews were also used to test assumptions on layer counts, installed heat leak performance, qualification timelines and the pace of spending on gas and space projects. Responses were compared across regions to identify gaps between announced and operating capacity.
Market size was built from the bottom up using supplier revenue and insulated area, and was cross-checked from the top down against liquefied gas storage capacity, launch activity and cryogenic equipment output. Triangulation across these views fixed the base year value. Forecasts consider project pipelines, space program budgets, material costs and macroeconomic conditions, and segment and regional shares were assigned from usage patterns in each setting. An analyst quality review checked consistency before release. Sensitivity tests on project delays and material prices were run, and announced projects were risk-weighted by funding status and construction stage before being included.
Multi-Layer Cryogenic Insulation Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.06 Billion |
| Market Size by 2035 | USD 2.14 Billion |
| CAGR | CAGR of 7.28% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Material (Polymer-Based, Composite, Metal Foil, and Others) • By Application (Cryogenic Storage, Cryogenic Transportation, Space Systems, and Others) • By End Use (Aerospace, Energy, Industrial Gases, Healthcare and Research, and Others) • By Thickness (Thin, Medium, and Thick) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Alkegen, Quest Thermal Group, Aerospace Fabrication & Materials, Thermal Management Technologies, Air Liquide, Web Industries, Frako-Term |

Frequently Asked Questions
The Multi-Layer Cryogenic Insulation Market was valued at USD 1.06 Billion in 2025 and is projected to reach USD 2.14 Billion by 2035, at a CAGR of 7.28%.
North America leads, with a 36.82% share in 2025, supported by space programs, liquefied natural gas exports and a deep base of cryogenic equipment makers.
Asia Pacific is expected to grow fastest, at a CAGR of 8.71% during 2026–2035, led by China, Japan, South Korea and India.
Polymer-based insulation, cryogenic storage, aerospace and medium constructions lead, while composite insulation, cryogenic transportation, energy applications and thin constructions grow fastest.
Alkegen, Quest Thermal Group, Aerospace Fabrication & Materials, and Air Liquide lead, along with Web Industries and Frako-Term.
