
Semiconductor Back-End Equipment Market Report Scope & Overview:
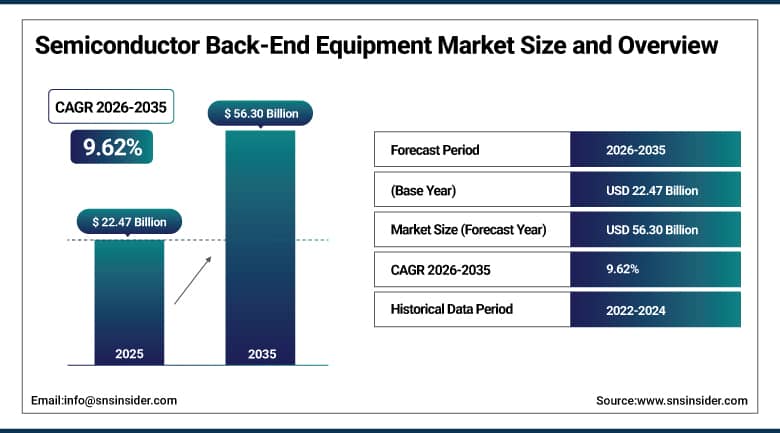
The Semiconductor Back-End Equipment Market was valued at USD 22.47 Billion in 2025 and is expected to reach USD 56.30 Billion by 2035, growing at a CAGR of 9.62% from 2026-2035.
The Semiconductor Back-End Equipment Market covers the machines that turn processed wafers into tested, packaged chips. It includes probers, testers and handlers, dicing saws, grinders, die and wire bonders, thermocompression and hybrid bonders, molding systems and related assembly tools, used by outsourced assembly and test houses, integrated device makers and foundries. Artificial intelligence accelerators, high-bandwidth memory and chiplet designs are shifting value from wafer fabrication toward packaging and test, so spending on back-end tools is rising faster than on many other equipment categories. Suppliers range from specialists in bonding, dicing and test to broad equipment groups, and they compete on placement accuracy, throughput, uptime and the strength of their service networks.
⮞In 2022, SEMI reported by assembly and packaging equipment sales would fall 14.9% to $6.1 billion in 2022, reflecting weaker semiconductor demand after strong growth in 2021. Test equipment sales were projected to decline 2.6%.
To Get More Information On Semiconductor Back-End Equipment Market - Request Free Sample Report
Semiconductor Back-End Equipment Market Trends
-
Hybrid bonding and thermocompression bonding are moving from pilot lines to volume production as high-bandwidth memory stacks and advanced logic packages demand finer interconnect pitches than solder bumps allow. Suppliers report growing customer lists for these tools.
-
Test intensity is climbing as artificial intelligence processors and memory stacks require longer test times, higher power delivery and system-level validation before shipment, which lifts demand for advanced testers, handlers and probe cards. Test cells increasingly combine wafer, package and system-level steps.
-
Panel-level and large-substrate packaging is gaining attention, pushing equipment makers to develop dicing, bonding and molding tools that handle bigger formats with tight warpage control. Larger formats could lower the cost per package over time.
-
Chip makers are investing in captive advanced packaging capacity, so foundries and memory producers are buying tools alongside traditional outsourced assembly and test providers. This widens the buyer base for premium tools.
-
Equipment suppliers are adding machine learning, in-line inspection and data analytics to bonders and testers to raise yield and cut cost per packaged die. Remote monitoring also reduces unplanned downtime.
U.S. Semiconductor Back-End Equipment Market Outlook
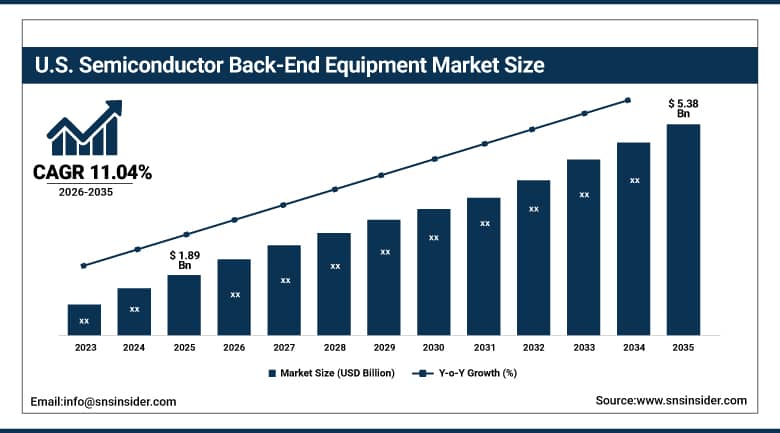
The U.S. Semiconductor Back-End Equipment Market was valued at USD 1.89 Billion in 2025 and is expected to reach USD 5.38 Billion by 2035, growing at a CAGR of 11.04% from 2026-2035.
The U.S. Semiconductor Back-End Equipment Market is the largest national market in North America, driven by federal incentives for local packaging and by new assembly and test capacity announced by leading chip makers and outsourced providers. Arizona, Texas, Oregon and Idaho are becoming centers for advanced packaging, and several tool suppliers are located in the country. Demand from cloud operators for accelerators also encourages local packaging, so equipment orders are expected to rise steadily through 2035. Close ties between chip designers, packaging providers and tool makers shorten qualification of new processes, and research programs at national laboratories and universities support workforce development.
⮞The U.S. Federal Reserve reported on 18 August 2026 that industrial production of semiconductors and related electronic components rose 11.9% year on year in July 2026.
Semiconductor Back-End Equipment Market Segment Analysis
-
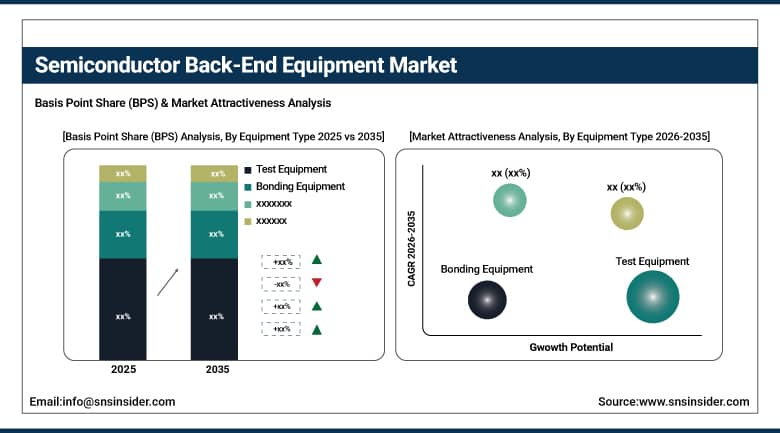
By Equipment Type, the Test Equipment segment dominated the Semiconductor Back-End Equipment Market with approximately 57.42% share in 2025, while the Bonding Equipment segment is the fastest growing with a CAGR of approximately 13.84%.
-
By Packaging Technology, the Flip Chip segment dominated the Semiconductor Back-End Equipment Market with approximately 34.76% share in 2025, while the 2.5D and 3D Integration segment is the fastest growing with a CAGR of approximately 15.23%.
-
By Application, the Computing and Data Centers segment dominated the Semiconductor Back-End Equipment Market with approximately 36.41% share in 2025 and is also the fastest growing with a CAGR of approximately 12.06%.
-
By End User, the OSATs segment dominated the Semiconductor Back-End Equipment Market with approximately 47.63% share in 2025, while the Foundries segment is the fastest growing with a CAGR of approximately 12.94%.
By Equipment Type, Test Equipment Dominates the Semiconductor Back-End Equipment Market and Bonding Equipment Grows Fastest
Test equipment holds approximately 57.42% of the Semiconductor Back-End Equipment Market in 2025. Every chip must be probed at wafer level and tested again after packaging, and artificial intelligence processors, memory stacks and automotive devices need longer test times and higher power than earlier products. Testers, handlers, probers and probe cards are therefore the largest spending category in back-end fabs, and demand follows chip output closely. Suppliers differentiate through parallel test capability, power delivery, thermal control and software that shortens test programs, and customers tend to stay with a platform once it is qualified.
Bonding equipment is the fastest growing type, with a CAGR of approximately 13.84% during 2026-2035. Thermocompression and hybrid bonders place stacked dies with micron-level accuracy for high-bandwidth memory and advanced logic, and order books at leading suppliers have expanded sharply. Dicing and grinding tools, molding systems and other assembly equipment add steady demand as package sizes and thinning requirements become more demanding. Precise placement, force control and clean-room compatibility command premium selling prices, and every new generation of memory stacking creates a fresh purchase cycle for these tools.
⮞SEMI projected assembly and packaging equipment sales would increase 8% to $5.4 billion in 2025. Artificial intelligence, high-performance computing, and increasingly complex semiconductor devices were identified as important drivers of investment.
By Packaging Technology, Flip Chip Dominates the Semiconductor Back-End Equipment Market and 2.5D and 3D Integration Grows Fastest
Flip chip accounts for approximately 34.76% of the market in 2025. The technology connects the die to the substrate through bumps and supports the high input and output counts needed by processors, graphics chips and networking devices. Mature process know-how and wide availability of bumping, bonding and reflow tools keep flip chip lines the largest tool consumers among packaging methods. Established lines make flip chip a safe choice for volume products, and upgrades from older bump pitches to finer pitches sustain replacement demand for placement and reflow equipment.
The 2.5D and 3D integration category is the fastest growing, with a CAGR of approximately 15.23% during 2026-2035. Silicon interposers, chiplets and stacked memory require precise placement, advanced bonding, thinning and heavy testing, and each package consumes far more equipment capital than a conventional one. Wafer-level and fan-out formats continue to broaden, while wire bond packaging still serves automotive, power and legacy devices. Equipment makers are therefore investing in alignment accuracy, warpage control and in-line inspection so that stacked packages reach high yields at commercial volumes.
By Application, Computing and Data Centers Dominates the Semiconductor Back-End Equipment Market and Also Grows Fastest
Computing and data centers account for approximately 36.41% of the market in 2025 and are also the fastest growing application, with a CAGR of approximately 12.06% during 2026-2035. Accelerators, server processors, high-bandwidth memory and networking chips need advanced packaging and demanding test flows, so cloud capital spending translates directly into orders for bonders, testers and handlers. Hyperscale cloud operators have lifted their capital budgets sharply, and chip makers respond by adding packaging and test lines that serve these customers first.
Consumer electronics, which include smartphones, wearables and personal computers, remain a large source of volume for assembly tools. Automotive electronics add demand for reliable packages and burn-in test, industrial controllers need long-life devices, and communications equipment calls for radio-frequency modules and optical components. These applications maintain a stable base while artificial intelligence sets the pace of growth. Product refresh cycles at major brands and the electrification of vehicles keep orders recurring, which helps suppliers balance the sharper swings seen in artificial intelligence programs.
By End User, OSATs Dominate the Semiconductor Back-End Equipment Market and Foundries Grow Fastest
Outsourced semiconductor assembly and test providers account for approximately 47.63% of the market in 2025. Fabless chip designers and many integrated device makers rely on these specialists for packaging and test, and the providers buy large fleets of bonders, dicers, molding systems and testers. Their capacity additions in Taiwan, Malaysia, China, Vietnam and the United States are a major source of equipment orders. Their scale allows them to negotiate volume purchases, and long-term contracts with chip designers give them confidence to commit to new lines ahead of demand.
Foundries are the fastest growing end user, with a CAGR of approximately 12.94% during 2026-2035. Leading wafer manufacturers are building their own advanced packaging lines to integrate chiplets and stacked dies, which brings them into the equipment market as direct buyers. Integrated device makers, especially memory producers, also invest heavily in stacking and test tools for high-bandwidth memory. Government support in several countries is also encouraging such captive facilities, which strengthens the market for suppliers able to deliver complete bonding and test lines.
⮞Japan Electronics and Information Technology Industries Association, JEITA, reported that integrated circuit exports from Japan rose 158.8% year on year in June 2026.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
33.62% |
|
North America |
United States |
87.62% |
|
Europe |
Germany |
29.46% |
|
Latin America |
Mexico |
46.37% |
|
Middle East & Africa |
Israel |
38.52% |
Asia Pacific Semiconductor Back-End Equipment Market Insights
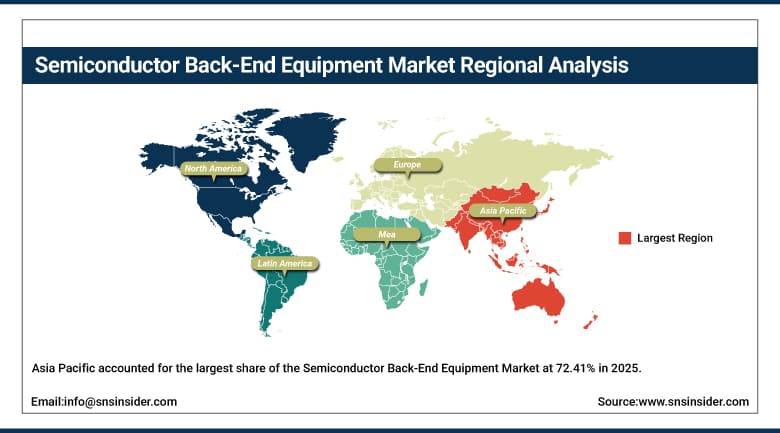
Asia Pacific accounted for the largest share of the Semiconductor Back-End Equipment Market at 72.41% in 2025, with a CAGR of 9.51% during 2026-2035. The region hosts nearly all large outsourced assembly and test providers, the leading memory makers and the biggest foundries, so it buys most of the world’s bonders, dicers and testers. Taiwan, South Korea, China, Japan and Southeast Asia form a dense supply chain. Government support for local chip and equipment industries is strengthening the supply base, and clusters in Hsinchu, Penang and Suwon shorten delivery and service times.
China is the largest country market, with 33.62% of regional demand, supported by large packaging capacity and policy efforts to build local equipment suppliers. Taiwan leads in advanced packaging for artificial intelligence chips, South Korea concentrates on high-bandwidth memory stacking, and Japan supplies dicing and grinding technology. Malaysia, Vietnam and India are adding assembly sites, and India is the fastest growing country. Competition among regional tool suppliers keeps prices attractive for packaging houses, while joint development with leading chipmakers speeds the adoption of new bonding methods.
⮞China’s National Bureau of Statistics reported on 15 July 2026 that integrated circuit output reached 279.8 billion units in the first half of 2026, up 23.1% year on year.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Semiconductor Back-End Equipment Market Insights
North America held approximately 12.39% of the Semiconductor Back-End Equipment Market in 2025 and is the fastest growing region, with a CAGR of 11.27% during 2026-2035. The United States contributes about 87.62% of regional demand and Canada the balance. New packaging plants, federal manufacturing incentives and the push to bring advanced assembly closer to wafer fabs are lifting orders for tools. Large research budgets, strong venture funding and the presence of leading cloud customers support new packaging designs and encourage suppliers to place service teams close to fabs.
Canada is regarded as the fastest growing country in the region, supported by photonics, quantum and data center investment. Mexico, which belongs to Latin America, hosts assembly and test sites for electronics makers. The region also hosts leading test, probe card and bonder suppliers, which keeps design and service close to customers and encourages local sourcing. Federal programs for chip manufacturing and advanced packaging encourage investment, and several outsourced providers have announced new sites to serve accelerator designers. Many suppliers keep applications labs near cloud customers.
⮞The Semiconductor Industry Association reported on 5 October 2026 that August 2026 global chip sales rose 144.3% year on year, with sales in the Americas up 180.9%.
Europe Semiconductor Back-End Equipment Market Insights
Europe accounted for approximately 9.28% of the Semiconductor Back-End Equipment Market in 2025, with a CAGR of 8.14% during 2026-2035. Germany, the Netherlands, France, Austria and Italy lead demand. The region is a major source of equipment rather than only a buyer, with leading bonding, wafer bonding and lithography-adjacent suppliers, and its fabs serve automotive, industrial and power markets. Long product lifecycles, strict quality requirements and a strong research base shape purchasing, and customers often work closely with suppliers during process development.
Germany is the largest market, with about 29.46% of regional demand, because of automotive and power semiconductor makers and new fabs in Saxony. The Netherlands is a hub for die attach and hybrid bonding technology, while Austria and France add specialist equipment and assembly activity. Packaging projects under the Chips Act are expected to deepen regional capacity for test and assembly. Public funding for chip and communications projects supports activity across the continent, and cooperation between research institutes and industry helps commercialize new bonding methods.
⮞The European Commission proposed Chips Act 2.0 on 28 May 2026, targeting EUR 120 Billion of combined investment by 2035 and noting that Europe holds only 8-10% of world chip output.
MEA & Latin America Semiconductor Back-End Equipment Market Insights
The Middle East and Africa and Latin America together account for approximately 5.92% of the Semiconductor Back-End Equipment Market in 2025, with Latin America at 3.45% and the Middle East and Africa at 2.47%. Israel is the leading market in the Middle East, with major chip design and manufacturing sites and several inspection and test equipment makers, while Gulf countries are planning semiconductor and data center projects. Government spending on digital infrastructure and incentives for electronics manufacturing is a key factor shaping near-term demand in both regions.
Latin America is led by Mexico, which has assembly and test operations tied to electronics, automotive and server production. Costa Rica hosts packaging and test facilities of a global chipmaker, and Brazil is building incentives for local assembly. Most equipment is imported, so service networks and distributor relationships matter. Growth is expected to follow nearshoring investment and new projects over the forecast period. Regional partners offer technical support, spare parts and local inventory to shorten delivery times and reduce downtime for customers operating older equipment.
⮞Mexico’s national statistics agency INEGI reported on 28 September 2026 that exports rose 29.3% year on year in the first eight months of 2026.
Market Dynamics
Growth Drivers: AI Accelerators and Advanced Packaging Demand Drive Growth in the Semiconductor Back-End Equipment Market
Artificial intelligence hardware is the strongest force behind the Semiconductor Back-End Equipment Market. Training and inference accelerators combine logic chiplets and stacks of high-bandwidth memory in complex packages, and each step in package complexity increases the number of bonding, thinning and test operations. Chip makers have therefore raised packaging capital budgets and are ordering tools earlier than usual. Suppliers able to meet the precision requirements can secure long-term design positions and command higher prices. Packaging announcements by leading foundries and memory makers are therefore closely watched as leading indicators of tool orders over the following quarters.
Rising test intensity is the second driver. Larger dies, higher power and tighter reliability standards lengthen test times, so operators need more testers and handlers for each wafer or package shipped. Automotive electrification and power devices add further test content. Together, these trends are lifting back-end equipment orders and extending order backlogs at leading suppliers. Spending by cloud operators therefore has a direct effect on orders, and vehicle electronics and radio access equipment add further momentum. Demand for known-good-die testing before stacking further raises the number of test insertions.
⮞The Semiconductor Equipment Association of Japan reported in September 2026 that sales of Japan-made semiconductor equipment reached a record in August 2026, up 47.4% year on year.
Restraints: Cyclical Chip Demand and High Equipment Costs Restrain Growth in the Semiconductor Back-End Equipment Market
Cyclical demand restrains the Semiconductor Back-End Equipment Market. Orders for assembly and test tools follow chip volumes, and consumer, industrial and automotive end markets can move through inventory corrections that cause buyers to delay purchases. Uneven demand between artificial intelligence products and mature chips complicates capacity planning for equipment suppliers. Companies diversify toward data center and automotive segments to reduce this exposure, although the benefit takes time to appear in order books. Contract manufacturers also trim orders quickly when end demand weakens, and corrections can last several quarters.
High equipment costs and technical complexity add further friction. Hybrid bonders and advanced testers are expensive, require cleanroom-grade environments and demand highly skilled engineers, which slows adoption among smaller packaging houses. Export controls and trade tensions also limit sales to some customers and complicate supply chains for critical components. Margins on older tools stay under pressure, which pushes suppliers toward differentiated products and recurring service revenue. Currency swings affect pricing for companies selling across regions. Qualification delays slow revenue recognition.
⮞Germany’s statistics office Destatis, as cited by the electrical industry association ZVEI in July 2026, showed that real electrical and electronics production fell 5.4% year on year in May 2026.
Opportunities: Chiplet Architectures and Regional Capacity Build-Out Create Opportunities in the Semiconductor Back-End Equipment Market
Chiplet architectures create a major opportunity. Designers are splitting large processors into smaller dies that are assembled in advanced packages, which increases demand for precise bonding, known-good-die testing and inspection. Equipment makers that offer integrated lines covering placement, bonding and test can win larger orders from chip makers and packaging providers. Integrated platforms also make it harder for rivals to displace incumbent suppliers once a package design has been released into production. Smaller firms may specialize in narrow process steps and partner with larger platform vendors.
Regional capacity build-out is a second opening. Governments in the United States, India, Europe and Southeast Asia are funding assembly and test plants to reduce dependence on a few locations. Each new site requires a full set of back-end tools, and local service centers and training programs create further revenue for suppliers that establish early partnerships. Public tenders and subsidy programs often favor suppliers with proven reliability, which rewards firms that invest early in training and spare parts. Early partnerships often lead to repeat orders as sites expand.
⮞India’s Ministry of Electronics and Information Technology reported in October 2026 that the country’s electronics production reached USD 144 Billion in fiscal year 2025-26, about five times the level of fiscal year 2014-15.
Recent Developments:
-
2026: Applied Materials announced an accelerated share purchase to lift its stake in BE Semiconductor Industries to about 20%, while Besi joined Applied’s EPIC Center as an innovation partner.
-
2026: ASMPT reported first-half bookings up 85.1% year on year, including bulk orders for more than 50 thermocompression bonding tools from outsourced assembly and test providers, and said its second-generation hybrid bonder had reached customer sampling.
-
2026: Advantest raised its sales forecast for the fiscal year ending March 2027 by about 20.70%, citing strong demand for testers used in artificial intelligence inference chips.
-
2026: Kulicke & Soffa reported fiscal third-quarter revenue of USD 330.40 Million, more than double the level a year earlier, and guided to about USD 375.00 Million for the next quarter.
Semiconductor Back-End Equipment Market Key Players
-
Advantest Corporation
-
Teradyne, Inc.
-
BE Semiconductor Industries N.V.
-
ASMPT Limited
-
Kulicke & Soffa Industries, Inc.
-
Disco Corporation
-
Tokyo Seimitsu Co., Ltd.
-
Hanmi Semiconductor Co., Ltd.
-
Applied Materials, Inc.
-
Cohu, Inc.
-
FormFactor, Inc.
-
Onto Innovation Inc.
-
Camtek Ltd.
-
Towa Corporation
-
Shibaura Mechatronics Corporation
-
SUSS MicroTec SE
-
EV Group
-
Chroma ATE Inc.
-
Hanwha Semitech Co., Ltd.
-
Changchuan Technology Co., Ltd.
Semiconductor Back-End Equipment Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 22.47 Billion |
| Market Size by 2035 | USD 56.30 Billion |
| CAGR | CAGR of 9.62% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Equipment Type (Test Equipment, Bonding Equipment, Dicing and Grinding Equipment, Molding and Encapsulation Equipment, and Others) • By Packaging Technology (Wire Bond, Flip Chip, Wafer-Level Packaging, 2.5D and 3D Integration, and Others) • By Application (Computing and Data Centers, Consumer Electronics, Automotive, Industrial, Communications, and Others) • By End User (OSATs, IDMs, and Foundries) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Advantest Corporation, Teradyne, Inc., BE Semiconductor Industries N.V., ASMPT Limited, Kulicke & Soffa Industries, Inc., Disco Corporation, Tokyo Seimitsu Co., Ltd., Hanmi Semiconductor Co., Ltd., Applied Materials, Inc., Cohu, Inc., FormFactor, Inc., Onto Innovation Inc., Camtek Ltd., Towa Corporation, Shibaura Mechatronics Corporation, SUSS MicroTec SE, EV Group, Chroma ATE Inc., Hanwha Semitech Co., Ltd., Changchuan Technology Co., Ltd. |

Frequently Asked Questions
The key players in the Semiconductor Back-End Equipment Market include Advantest Corporation, Teradyne, Inc., BE Semiconductor Industries N.V., ASMPT Limited, Kulicke & Soffa Industries, Inc., among others.
Key opportunities include chiplet architectures that raise demand for bonding, inspection and known-good-die testing, and government-backed assembly and test capacity in the United States, India, Europe and Southeast Asia.
The major growth factor is the surge in artificial intelligence accelerators and high-bandwidth memory, which require complex packages and longer test flows.
The Test Equipment segment dominated the Semiconductor Back-End Equipment Market with approximately 57.42% share in 2025, because every chip is tested at wafer and package level and test times are rising.
Asia Pacific dominated the Semiconductor Back-End Equipment Market with a 72.41% share in 2025, supported by the concentration of assembly and test providers, memory makers and foundries.
