
Subsea Manifolds Market Report Scope & Overview:
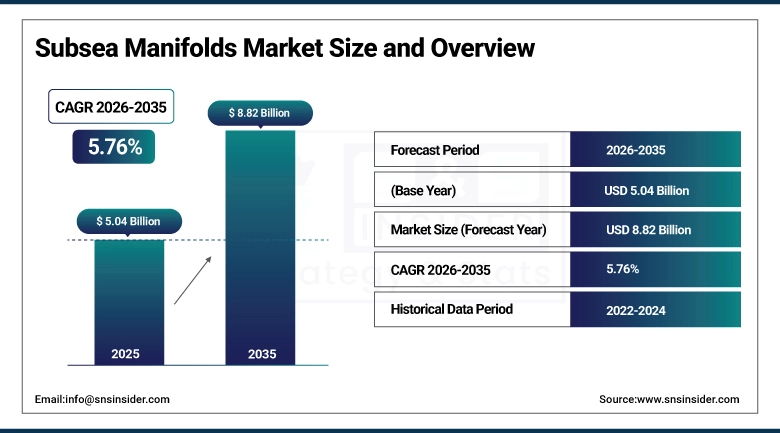
The Subsea Manifolds Market was valued at USD 5.04 Billion in 2025 and is expected to reach USD 8.82 Billion by 2035, growing at a CAGR of 5.76% from 2026-2035.
The Subsea Manifolds Market is on a steady expansion path as operators sanction deepwater tie-backs and standardized production systems that gather, route, and inject fluids across many wells. Each development needs structures that combine valves, piping, connectors, and controls, and awards are increasingly bundled with trees, umbilicals, and flowlines under integrated contracts. Configure-to-order designs are shortening delivery schedules, while compact modular manifolds can be installed from smaller vessels. Brownfield tie-backs in the North Sea, the Gulf of America, and Brazil reuse existing infrastructure, and greenfield programs in Guyana, Africa, and Southeast Asia add new demand. Fabrication yards, valve makers, and controls suppliers share in this spending as order books extend into the next decade and capacity investments follow.
⮞In September 2025, TechnipFMC announced that ExxonMobil Guyana had awarded it a substantial subsea contract for the Hammerhead project in the Stabroek Block. TechnipFMC will manage, engineer, and manufacture subsea production systems for production and water injection, using Subsea 2.0 trees, manifolds, and controls, in its seventh greenfield award from ExxonMobil Guyana.
To Get more information On Subsea Manifolds Market - Request Free Sample Report
Subsea Manifolds Market Trends
-
Rising adoption of configure-to-order and standardized manifold designs that shorten delivery schedules.
-
Growing use of compact, modular manifolds that can be installed from smaller vessels.
-
Expanding use of subsea tie-backs that connect new wells to existing host facilities.
-
Increasing integration of electro-hydraulic distribution and digital monitoring into manifold packages.
-
Rising interest in subsea injection hubs for water, gas, and carbon dioxide storage projects.
U.S. Subsea Manifolds Market Outlook
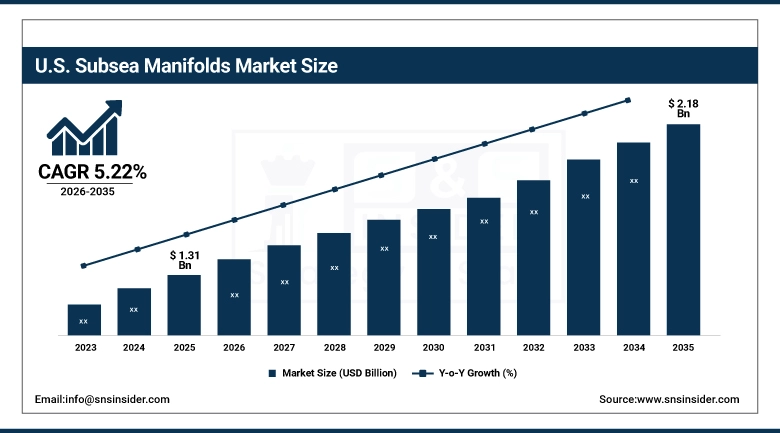
The U.S. Subsea Manifolds Market was valued at USD 1.31 Billion in 2025 and is expected to reach USD 2.18 Billion by 2035, growing at a CAGR of 5.22% from 2026-2035.
The U.S. Subsea Manifolds Market is expanding as deepwater projects in the Gulf of America move from sanction to installation and as operators extend producing fields through tie-backs. High-pressure, high-temperature reservoirs in the Paleogene are driving demand for 20,000 psi equipment, while multiphase boosting and injection systems support older fields. Houston concentrates engineering, project management, and controls expertise, and fabricators along the Texas and Louisiana coasts build manifolds, foundations, and connection systems for regional and international customers. Independent operators favor repeatable designs that limit cost and schedule risk, and integrated awards covering trees, manifolds, umbilicals, and flowlines are now common. Suppliers also export U.S.-built equipment to Mexico, Brazil, and West Africa, which keeps Gulf Coast shops busy between local awards.
⮞In October 2024, bp awarded TechnipFMC an iEPCI contract for its Kaskida development in the Gulf of America, covering subsea production systems that include 20,000 psi standardized trees and manifolds, plus umbilicals, risers, and flowlines. The award followed an integrated front-end engineering and design study that TechnipFMC completed for the project.
Subsea Manifolds Market Segment Analysis
-
By Type, the Template Manifold segment dominated the Subsea Manifolds Market with approximately 45.87% share in 2025, while the Cluster Manifold segment is the fastest growing with a CAGR of approximately 6.74%.
-
By Application, the Production segment dominated the Subsea Manifolds Market with approximately 66.41% share in 2025, while the Injection segment is the fastest growing with a CAGR of approximately 6.93%.
-
By Water Depth, the Deep Water segment dominated the Subsea Manifolds Market with approximately 47.26% share in 2025, while the Ultra-Deep Water segment is the fastest growing with a CAGR of approximately 7.58%.
-
By Component, the Valve segment dominated the Subsea Manifolds Market with approximately 33.58% share in 2025, while the Control System segment is the fastest growing with a CAGR of approximately 7.12%.
-
By Field Application, the Offshore Oil Production segment dominated the Subsea Manifolds Market with approximately 52.34% share in 2025, while the Subsea Gas Production segment is the fastest growing with a CAGR of approximately 6.69%.
By Type, Template Manifold Dominates the Subsea Manifolds Market and Cluster Manifold Grows Fastest
Template manifolds lead because they place the manifold, well slots, and foundation in one integrated structure that can be fabricated onshore, tested, and set on the seabed in a single lift. Operators drilling several wells within a compact reservoir footprint favor this arrangement, since it reduces seabed interfaces and the offshore hours spent on hook-up. Yards, such as Worley Rosenberg and Marketex build large templates for Norwegian fields, and integrated template structures from OneSubsea give trees and manifold a protected foundation together. Template layouts also standardize well design, so repeat programs reuse engineering and shorten the path from sanction to first oil.
Cluster manifolds are advancing fastest because they let operators connect satellite wells and outlying reservoirs to a central gathering point without building a full template. The approach suits phased developments in which wells are added as drilling results arrive, and it suits tie-backs that reuse existing host facilities. Six-slot units ordered for Brazil's Bonito and Bicudo fields show how mid-sized accumulations can be developed with one flexible structure. Modular designs, including Baker Hughes' Aptara compact manifold, are lighter and can be installed from smaller vessels, which lowers campaign costs. Rising demand for expandable layouts in mature basins is steering orders toward this configuration.
⮞In June 2024, Trendsetter Engineering won a contract from Trident Energy do Brasil to supply two six-slot production subsea manifolds for the Bonito and Bicudo fields, covering design, manufacture, pipework, and mudmat foundations. Production valves come from Advanced Technology Valve of Italy, with delivery scheduled for the third quarter of 2025.
By Application, Production Dominates the Subsea Manifolds Market and Injection Grows Fastest
Production manifolds account for the largest demand because every producing field needs a structure that commingles well output and routes it to the host through flowlines. Operators specify them from the first development concept, and they carry the isolation valves, flow meters, chemical distribution, and pigging loops that keep flow assurance manageable. Greenfield projects in Guyana, Brazil, Norway, and the Gulf of America each include several production manifolds per phase, and the equipment is bought alongside trees and controls under single awards. Expansion orders for ageing fields add a second stream, since manifold structures are designed for long service lives and extended through retrofits.
Injection manifolds are growing fastest as reservoir management shifts toward water, gas, and chemical injection to hold pressure and lift recovery in maturing fields. A dedicated injection manifold distributes treated seawater or produced gas to several wells from one point, cutting the number of lines and umbilical connections. Developments in the South China Sea with gas lift and gas injection trees, and in Guyana with water injection built into the production architecture, illustrate the pattern. Carbon storage projects add another class of injection hub, with subsea CO2 injection systems in the North Sea now moving into expansion. Operators treat injection capacity as protection for production plateaus.
⮞In March 2026, SLB OneSubsea won an integrated EPC contract from CNOOC for the Kaiping 18-1 deepwater field in the South China Sea, a 20-well development. The scope includes dual ESP configurations, gas lift and gas injection horizontal trees, manifolds, connectors, and control systems, with regional partners and in-country manufacturing.
By Water Depth, Deep Water Dominates the Subsea Manifolds Market and Ultra-Deep Water Grows Fastest
Deep water holds the largest position because many major discoveries of the past two decades sit at depths where subsea tie-backs are the only practical development route. Brazil's pre-salt fields, Guyana's Stabroek Block, West Africa, the Gulf of America, and the South China Sea all feature fields in this range, and each needs manifolds rated for high pressure and low seabed temperatures. Kikeh 3B in Malaysia, developed in roughly 1,300 to 1,400 meters of water, is typical of mid-range projects that buy a manifold with trees, distribution units, and controls. Floating production units anchor these hubs, and manifolds link wells to risers across long distances.
Ultra-deep water is expanding fastest as operators drill beyond earlier depth limits and as rated equipment catches up with the reservoirs. Pressure ratings of 20,000 psi, heavier foundations, and diverless connection systems are becoming routine requirements, and installation vessels with larger lifting capacity are being contracted for multi-year campaigns. Projects in the Paleogene of the Gulf of America, deepwater Mozambique, and the Brazilian pre-salt push specifications upward, and suppliers are qualifying larger connectors and compact designs to cope. Longer tie-back distances raise the value of each manifold, because it must remain reliable for decades at depths where remotely operated vehicles provide the only access.
⮞In March 2026, PTTEP Sabah Oil awarded SLB OneSubsea an EPC contract for integrated subsea production systems at Kikeh 3B, the second development phase of Malaysia's first deepwater field, in water 1,300 to 1,400 meters deep. The scope includes one manifold, three subsea trees, a subsea distribution unit, and integrated control systems, with execution through 2027.
By Component, Valve Dominates the Subsea Manifolds Market and Control System Grows Fastest
Valves lead component spending because a manifold is, in functional terms, a set of valves arranged around piping that directs flow, isolates wells, and permits testing. Each unit carries many gate or ball valves with remotely operated vehicle interfaces or hydraulic actuators, and the valves must meet strict qualification for pressure, temperature, and sealing over long service lives. Specialist valve makers supply bodies and actuators, as with the Italian supplier named on Trendsetter's Brazilian manifolds, and fabricators integrate them with piping and connectors. Because failures are costly to repair at depth, buyers pay for proven designs, and spares orders recur through the life of a field.
Control systems are rising fastest as manifolds take on more monitoring, metering, and automated actuation. Electro-hydraulic distribution units, subsea control modules, and distribution manifolds route power, signals, and fluids to many valves from a single umbilical termination. Fabricators that once supplied hardware alone now bid electrical and hydraulic scope, as KOIL Energy's West Africa award shows. Digital sensors on flow, pressure, and sand detection add data for operators, and electric actuation reduces hydraulic fluid volumes. Standardized controls platforms from the large system suppliers are shortening integration, and projects that combine trees, manifolds, and controls under one award favor this component.
⮞In December 2024, KOIL Energy secured a contract to engineer, procure, fabricate, assemble, and test electrical and hydraulic distribution manifolds for a West African project of a prominent international oil and gas company. The units will be built at KOIL's Houston facility, with delivery estimated for the second half of 2025.
By Field Application, Offshore Oil Production Dominates the Subsea Manifolds Market and Subsea Gas Production Grows Fastest
Offshore oil production leads because most installed manifolds serve oil-weighted developments tied back to floating production units, particularly in Brazil, West Africa, Guyana, Norway, and the Gulf of America. Oil developments typically require both production and injection manifolds, and associated gas handling adds further structures. Operators continue to sanction projects such as Hammerhead in Guyana and Kaskida in the Gulf of America due to standardized equipment shortens cycle times. The large installed base also supports a long tail of expansion tie-backs, repairs, and replacement structures. Steady demand from national oil companies in Brazil and China keeps order flow balanced against international operator cycles.
Subsea gas production is growing fastest as LNG-linked developments in Mozambique, Indonesia, and Australia draw on long-distance subsea gas gathering. Wet gas fields require manifolds that manage hydrates, high flow rates, and corrosive fluids, and large frame agreements, such as the multi-year arrangement for Coral North, lock in supply across several phases. Subsea gas compression manifolds, contracted for Western Australia's Jansz-Io field, extend plateau life without topside changes. Gas fields also offer longer plateau periods than oil, giving manifold suppliers a stable pipeline of repeat awards across the decade.
⮞In January 2026, Eni awarded Baker Hughes a multi-year frame agreement for subsea production systems and associated services for the Coral North LNG project in deepwater Mozambique. The scope of supply includes subsea trees, controls, manifolds, distribution, and topsides, according to Offshore magazine's report of the award.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
88.53% |
|
Asia Pacific |
China |
36.82% |
|
Europe |
Norway |
47.13% |
|
Latin America |
Brazil |
71.08% |
|
Middle East & Africa |
Angola |
31.69% |
North America Subsea Manifolds Market Insights
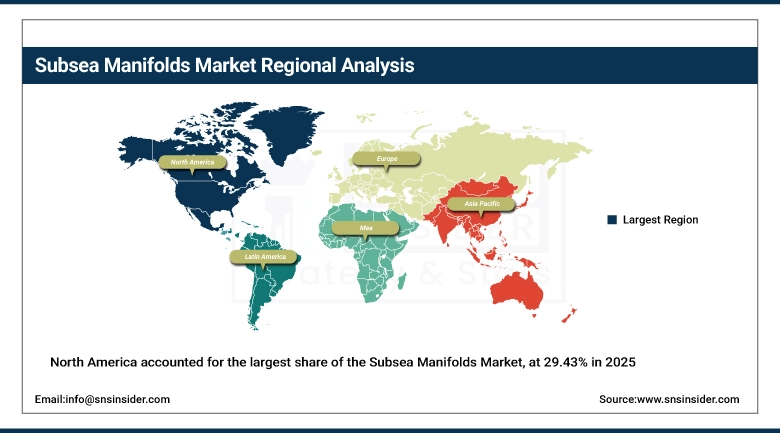
North America accounted for the largest share of the Subsea Manifolds Market, at 29.43% in 2025, supported by deepwater activity in the Gulf of America, a dense Houston engineering base, and a fabrication cluster along the Gulf Coast. Operators are developing high-pressure Paleogene reservoirs with 20,000 psi systems and extending older fields through tie-backs and boosting. Integrated awards that bundle trees, manifolds, umbilicals, and flowlines are common, and suppliers maintain manufacturing and service bases close to customers. Independent operators prefer repeatable designs, which supports steady order flow for standardized manifolds across the cycle.
In the United States, projects such as Kaskida and Shenandoah anchor demand, with HPHT equipment and multiphase boosting systems entering the order book alongside conventional structures. Canada's East Coast offshore fields depend on subsea tie-backs to floating units and offer a smaller but steady opportunity. Mexico is a deepwater growth market, where Woodside hired Trendsetter in December 2023 to supply several subsea manifolds for the Trion development. Regional suppliers also export manifolds, connectors, and intervention tooling to Brazil and West Africa, and the concentration of service companies in Houston supports spares, repairs, and upgrades for the installed base.
⮞In April 2026, Beacon Offshore Energy awarded SLB OneSubsea a high-pressure, high-temperature multiphase boosting system for the Shenandoah field in the Gulf of America, designed to operate above 15,000 psi. SLB said its engagement with Beacon began in January 2025 and that the system supports enhanced oil recovery.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Subsea Manifolds Market Insights
Asia Pacific is the fastest-growing regional market, projected to expand at a CAGR of 7.14% from 2026 to 2035, as national oil companies and international operators move into deeper water to offset maturing shallow fields. CNOOC has installed central manifolds in the South China Sea and awarded a 20-well development at Kaiping 18-1, while Offshore Oil Engineering delivered China's first central manifold for 1,500 meters of water. Malaysia, Indonesia, and Australia add gas-led projects that need long tie-backs, and regional fabrication capacity is expanding to meet the order pipeline.
Indonesia's Kutei Northern Hub and Maha developments call for multiple deepwater trees and manifolds, while Malaysia's Kikeh 3B adds another phase to the country's first deepwater field. In India, Larsen & Toubro has fabricated subsea manifolds in consortium with Baker Hughes and McDermott for deepwater gas developments, building local skills. Australia's subsea compression manifolds support gas plateau life, and Japanese and Korean engineering firms participate through yards and component supply. In-country manufacturing requirements are encouraging suppliers to open or expand regional facilities, which shortens lead times and strengthens competition among fabricators.
⮞In April 2024, CNOOC reported that all three deepwater subsea central manifolds for Phase II of its Deep Sea No. 1 gas project in the South China Sea had been installed. The manifolds, which connect seabed wellheads and channel gas to the platform, were built in-house by CNOOC.
Europe Subsea Manifolds Market Insights
Europe is a mature but active market in which Norway leads on manifold demand, supported by tie-back programs around existing hosts in the North Sea and the Norwegian Sea. Equinor, Aker BP, and Vår Energi favor standardized templates and manifolds that can be reused across fields, and local yards such as Worley Rosenberg in Stavanger fabricate large structures for contractors. Fram Sør, Yggdrasil, and Johan Castberg satellite fields illustrate the pipeline, and operators expect dozens of further tie-backs over the coming decade. Carbon storage developments add subsea injection hardware to the regional order book.
The United Kingdom contributes tie-back work in the North Sea, where integrated alliances between system suppliers and installers continue to win projects. Norway's yards, along with Estonian fabricators such as Marketex, supply templates, pipeline end manifolds, and spools to contractors across the region. The Netherlands and Germany participate mainly through engineering, valves, and components, while Italy provides valve and fabrication capacity. Regional operators also export design expertise to Brazil, West Africa, and Asia. Fabrication slots at Norwegian and Baltic yards are filling years ahead of delivery as tie-back volumes rise.
⮞In May 2026, Worley Rosenberg won a Subsea7 contract to fabricate 34 subsea structures at its Stavanger yard for Equinor's Fram Sør development, including pipeline end manifolds, pipeline end terminations, and pig launchers and receivers. Steel cutting was planned for June 2026, with delivery scheduled for the first half of 2027.
MEA & Latin America Subsea Manifolds Market Insights
The Middle East & Africa is led by West African deepwater, where Angola and Nigeria host long-running production hubs and new tie-back developments. Shell's Bonga North in Nigeria is adopting configure-to-order production systems, and KOIL Energy is building distribution manifolds for a West African project. East Africa is emerging as a gas region, with Mozambique's Coral North and Rovuma LNG projects requiring trees, manifolds, and controls under large frame awards. Offshore activity in the Gulf states is concentrated in shallower water, so subsea manifold demand there is limited. Local-content expectations are pushing suppliers to establish service bases and training programs near operating areas.
⮞In September 2026, ExxonMobil Moçambique, acting for the Area 4 partners, awarded SLB OneSubsea a contract for subsea production systems for the first phase of the Rovuma LNG project offshore Mozambique, covering manifolds, subsea trees, umbilicals, and control systems. OneSubsea plans a services base in Mozambique to support regional operators.
Latin America is a concentrated deepwater market, led by Brazil and Guyana. Petrobras continues to order trees, pipeline end manifolds, and distribution units for the pre-salt Santos and Campos basins, and independent operators such as Trident Energy are developing smaller fields with local suppliers. In Guyana, ExxonMobil's Stabroek Block programs buy manifolds in repeat batches, supported by fabrication of larger structures in-country. Trinidad and Tobago, Argentina, and Colombia add smaller projects, including a high-integrity pressure protection manifold for Ginger. Manufacturing bases in Macaé have become strategic for suppliers.
⮞In August 2024, Petrobras signed a contract with SLB OneSubsea for subsea equipment for the Santos and Campos basins, including six pipeline end manifolds, up to 19 wet Christmas trees, and five electro-hydraulic distribution units, with manufacturing set to begin in the third quarter of 2024.
Market Dynamics
Growth Drivers: Deepwater Tie-Back Development and Standardized Subsea Systems
Deepwater and tie-back development is the foundation of manifold demand. Operators in Brazil, Guyana, West Africa, Norway, and the Gulf of America are sanctioning projects that connect new wells to existing floating hosts, and each tie-back needs manifolds or templates to gather and route production. Brownfield programs extend field life at lower capital cost than new hosts, and gas-led developments in Mozambique, Indonesia, and Australia add long-distance gathering systems. National oil companies in China and Brazil are building their own deepwater pipelines, broadening the buyer base. Together these programs give suppliers visible order books that extend several years into the future and support investment in regional manufacturing capacity.
Standardization and configure-to-order designs form the second driver, since they cut engineering hours, shorten delivery, and lower risk for operators that must control capital. Pre-engineered core components, modular manifolds, and repeatable templates allow suppliers to quote fixed scopes and execute faster, and large buyers such as ExxonMobil Guyana, Eni, and Shell are adopting them across programs. Integrated EPCI awards that bundle trees, manifolds, controls, and installation reduce interfaces and give customers single-point accountability. Standard designs also simplify spares and maintenance, which supports aftermarket revenue and helps suppliers amortize qualification costs over many projects and operators.
⮞In March 2024, Saipem said at a company workshop that its Guyana operation would fabricate larger and more complex subsea structures for ExxonMobil's Stabroek Block, occupying 81,000 square meters at the Vreed-en-Hoop shore base by the third quarter of 2024. Saipem's earlier Guyana supply included five manifolds for Liza 1, eight for Liza 2, and 11 for Payara, with 12 planned for Yellowtail.
Restraints: Oil Price Cyclicality and Qualification and Supply Chain Constraints
Capital spending on offshore projects follows oil and gas prices and operator cash flow, and manifold orders can be delayed when sanctions slip. Deepwater developments carry large budgets, and investment committees compare them with shorter-cycle onshore options when prices soften. Cost inflation in steel, valves, and fabrication labor has raised bid prices, while customers resist passing through increases on fixed-price scopes. Contract awards are lumpy, so quarterly order intake swings widely and complicates capacity planning for yards and suppliers. Smaller operators in particular may postpone tie-backs until financing is secure, which pushes manifold deliveries into later years and extends the time between award and revenue.
Qualification and supply chain constraints also slow growth. Subsea equipment must pass extensive testing against pressure, temperature, and reliability requirements, and new materials, connectors, or manufacturing methods take years to gain approval from operators and classification societies. Specialist valves, forgings, and connectors come from a limited number of suppliers, and lead times lengthen when several large projects order at once. Fabrication yards with the right welding and inspection capability are scarce, and local-content expectations can force suppliers to qualify new facilities. Offshore installation vessels are booked well ahead, so delays to a campaign can cascade across a manifold delivery schedule.
Opportunities: Subsea Injection Hubs and Life-of-Field Services
Subsea injection hubs offer a growing opportunity as operators seek to protect production and meet storage needs. Water and gas injection manifolds support recovery programs in mature basins, and carbon dioxide injection systems in the North Sea show how the same hardware serves storage projects. Frontier basins and emerging offshore regions need export manifolds and pipeline end structures that connect new production to buoys and terminals. Suppliers that offer standardized, expandable designs can serve both established and new customers, and service agreements for inspection, spares, and intervention create recurring revenue. Regions with early-stage offshore programs may adopt configure-to-order products from the start, avoiding custom engineering costs.
Life-of-field services are a second opportunity because installed manifolds stay in service for decades and need inspection, repair, spares, and upgrades. Suppliers with large installed bases, such as those reporting well over one hundred manifolds in service, can convert delivery into long agreements that cover valve replacement, connector refurbishment, and control retrofits. Digital monitoring adds data that supports condition-based maintenance, and compact, lighter structures let operators use smaller vessels for intervention. Regional service bases in Brazil, West Africa, Southeast Asia, and Mozambique shorten response times and satisfy local-content expectations. Operators are receptive because avoiding a retrieval campaign saves far more than the cost of a maintenance plan, and standardized designs make spares pooling practical across fields.
⮞In February 2026, DOF Group won a substantial contract in Argentina covering mooring pre-lay, pipeline end manifold installation and construction management, tie-in spool installation, and hook-up of two CALM buoys, using the Skandi Hera and Skandi Patagonia. Offshore work is scheduled in two campaigns during 2026, totaling more than 250 vessel days.
Recent Developments:
-
August 2026: Baker Hughes won a contract from Searah North Ganal Limited, a subsidiary of the Eni and PETRONAS joint venture Searah, to supply subsea systems for the Kutei Northern Hub offshore Indonesia. The scope covers 17 deepwater horizontal tree systems with associated manifolds and connections, control and distribution systems, and Cordant asset protection and condition monitoring systems.
-
May 2025: Marketex Offshore Constructions completed delivery of ten subsea templates for Aker BP's Yggdrasil development in the North Sea, with the final four shipped to Norway after six units in 2024. The templates were produced with Aker Solutions and OneSubsea, and form part of 18 templates Marketex has developed for global customers.
-
April 2025: bp awarded the Subsea Integration Alliance of SLB OneSubsea and Subsea7 an EPCI contract for the Ginger project offshore Trinidad and Tobago. OneSubsea will supply four vertical monobore subsea trees and a HIPPS manifold, described as the region's first, while Subsea7 provides a diver-installed tie-in system and a flexible production flowline.
-
December 2024: Shell Nigeria Exploration and Production Company awarded TechnipFMC a substantial contract for the Bonga North development offshore Nigeria, covering Subsea 2.0 tree systems, controls, manifolds, jumpers, and services. TechnipFMC said Shell was the first operator to adopt its configure-to-order Subsea 2.0 solution.
Subsea Manifolds Market Key Players are:
-
TechnipFMC plc
-
SLB (including SLB OneSubsea)
-
Baker Hughes Company
-
Subsea7 S.A.
-
Saipem S.p.A.
-
NOV Inc.
-
Oil States International, Inc.
-
WOM Group (Worldwide Oilfield Machine, Inc.)
-
Larsen & Toubro Limited (L&T Energy Hydrocarbon)
-
Aibel AS
-
Worley Limited
-
Oceaneering International, Inc.
-
Hunting PLC (FES Subsea)
-
Aker Solutions ASA
-
Siemens Energy
-
Dril-Quip (now part of Innovex)
-
Weatherford International plc
-
Halliburton Company
-
Trendsetter Engineering, Inc.
-
Jotne Group
Subsea Manifolds Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 5.04 Billion |
| Market Size by 2035 | USD 8.82 Billion |
| CAGR | 5.76% from 2026-2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type: Dominant – Template Manifold (45.87% share in 2025); Fastest-Growing – Cluster Manifold (CAGR 6.74%) • By Application: Dominant – Production (66.41% share in 2025); Fastest-Growing – Injection (CAGR 6.93%) • By Water Depth: Dominant – Deep Water (47.26% share in 2025); Fastest-Growing – Ultra-Deep Water (CAGR 7.58%) • By Component: Dominant – Valve (33.58% share in 2025); Fastest-Growing – Control System (CAGR 7.12%) • By Field Application: Dominant – Offshore Oil Production (52.34% share in 2025); Fastest-Growing – Subsea Gas Production (CAGR 6.69%) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | TechnipFMC plc, SLB (including SLB OneSubsea), Baker Hughes Company, Subsea7 S.A., Saipem S.p.A., NOV Inc., Oil States International, Inc., WOM Group (Worldwide Oilfield Machine, Inc.), Larsen & Toubro Limited (L&T Energy Hydrocarbon), Aibel AS, Worley Limited, Oceaneering International, Inc., Hunting PLC (FES Subsea), Aker Solutions ASA, Siemens Energy, Dril-Quip (now part of Innovex), Weatherford International plc, Halliburton Company, Trendsetter Engineering, Inc., Jotne Group |

Frequently Asked Questions
Key players include TechnipFMC plc, SLB (including SLB OneSubsea), Baker Hughes Company, Subsea7 S.A., Saipem S.p.A., NOV Inc., Oil States International, Inc., and Trendsetter Engineering, Inc., among other system suppliers, fabricators, and engineering contractors.
Subsea injection hubs for water, gas, and carbon dioxide, along with life-of-field inspection, spares, and upgrade services for installed manifolds, represent the primary opportunities.
Growth is primarily driven by deepwater and tie-back development, combined with standardized and configure-to-order subsea systems that shorten delivery schedules and lower project risk.
By Type, Template Manifold dominated the market with approximately 45.87% share in 2025, reflecting the preference for integrated structures that combine manifold, well slots, and foundation in a single lift.
North America dominated the market with approximately 29.43% share in 2025, driven by deepwater activity in the Gulf of America, a Houston engineering base, and a Gulf Coast fabrication cluster.
