
Urgent Care Apps Market Report Scope & Overview:
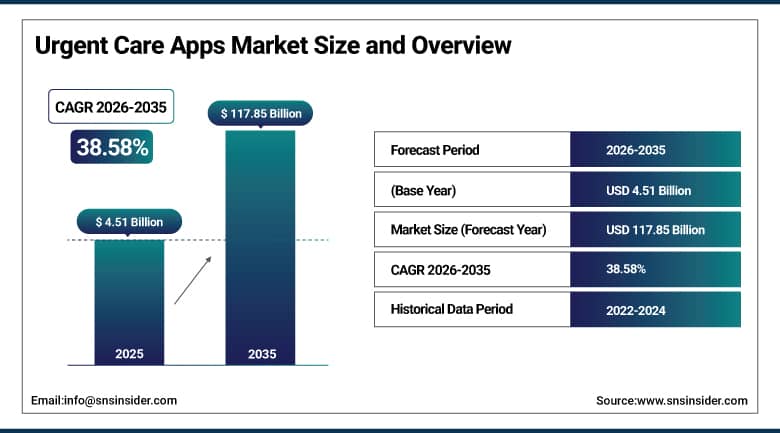
The Urgent Care Apps Market was valued at USD 4.51 Billion in 2025 and is expected to reach USD 117.85 Billion by 2035, growing at a CAGR of 38.58% from 2026-2035.
The Urgent Care Apps Market growth is driven by rising internet penetration and smartphone connectivity, which continue to expand patient and clinician access to mobile and web-based applications designed to provide quick access to medical care and information for non-life-threatening as well as time-critical conditions. These applications help users locate nearby urgent care centers, book appointments, consult with healthcare professionals, and coordinate real-time communication between emergency medical services, hospital emergency departments, and specialist care teams. Continued rise in the incidence of various health conditions further fuels the need for digital access to healthcare services, whereas continued corporate spending on integration of clinical communication within pre-hospital, hospital, and post-hospital settings further emphasizes the importance of digital health technology by organizations seeking reduction in time to treatment.
In June 2026, Pulsara came up with the Pulsara Intelligence software to add features such as automation of information gathering by using AI technology. Pulsara’s software enables automation of information gathering from a provider's narrative. The development strengthens Pulsara’s digital platform for EMS and hospital teams managing time-sensitive emergency care and patient coordination.
To Get More Information On Urgent Care Apps Market - Request Free Sample Report
Urgent Care Apps Market Trends
-
Rising integration of AI-driven triage and symptom assessment capability within urgent care and emergency communication apps.
-
Growing consolidation among clinical communication platforms through acquisitions of specialized pre-hospital technology providers.
-
Expanding use of urgent care apps to unify communication across EMS, hospital, and post-discharge care settings.
-
Increasing adoption of cloud-based, EHR-linked communication platforms supporting real-time patient information sharing.
-
Rising deployment of secure, HIPAA-compliant messaging platforms replacing legacy pager and phone-based clinical communication.
U.S. Urgent Care Apps Market Outlook
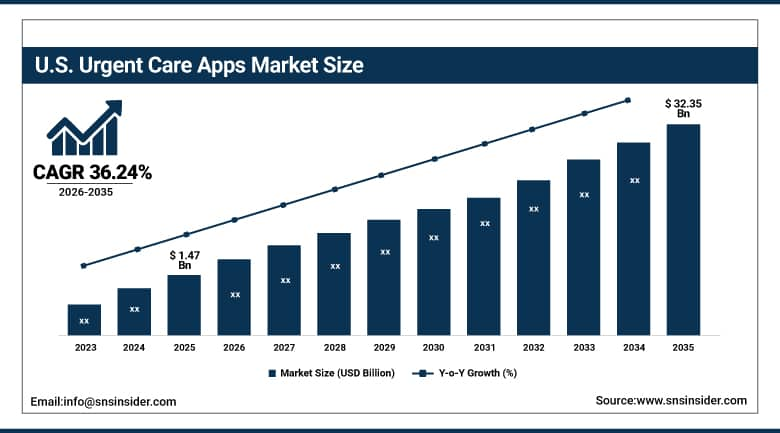
The U.S. Urgent Care Apps Market was valued at USD 1.47 Billion in 2025 and is expected to reach USD 32.35 Billion by 2035, growing at a CAGR of 36.24% from 2026-2035.
The U.S. Urgent Care Apps Market growth remains bolstered by the well-developed healthcare system infrastructure and high level of technology adoption for healthcare in the United States for hospitals, emergency medical services, and health systems. Healthcare systems in the domestic market are increasingly focusing on ensuring seamless communication amongst care providers within and outside the hospital environment due to increasing adoption of out-of-hospital care services, enhanced by improved EMS communication, inter-facility transportations, and post-discharge patient follow-up. Growing demand for healthcare communication technologies is also increasing adoption within trauma, stroke, and cardiology emergency care services, where timely information exchange between pre-hospital and in-hospital care teams directly impacts patient outcomes.
On February 27, 2025, TigerConnect launched its TigerConnect Pre-Hospital product along with the Early Access release of its TigerConnect Transfer product at HIMSS25, following its acquisition of Twiage recently, as a means of improving healthcare communication by integrating emergency medical services, emergency department teams, and transfer centers. The launch illustrates how established U.S. clinical communication platforms continue to expand pre-hospital and inter-facility transfer capability, enabling care teams to route case and patient information to the right specialists prior to a patient's arrival and reduce time-to-treatment across domestic health systems.
Urgent Care Apps Market Segment Analysis
-
By Platform, the android segment dominated the urgent care apps market with approximately 48.50% share in 2025, while the iOS segment is the fastest growing with a CAGR of approximately 43.34% from 2026–2035.
-
By Type, the post-hospital apps segment dominated the urgent care apps market with approximately 36.60% share in 2025, while the pre-hospital emergency care & triaging apps segment is the fastest growing with a CAGR of approximately 41.20%.
-
By Clinical Area, the trauma segment dominated the urgent care apps market with approximately 28.60% share in 2025, while the stroke segment is the fastest growing with a CAGR of approximately 40.80%.
-
By End-User, the hospitals & clinics segment dominated the urgent care apps market with approximately 43.20% share in 2025, while the patients segment is the fastest growing with a CAGR of approximately 40.90% from 2026–2035.
By Platform, android dominates the urgent care apps market, iOS grows fastest
Android Platform accounted for the major market share of the urgent care apps market in 2025 owing to its wide reach among smartphone users globally, being affordable and available worldwide. Android urgent care apps help people have virtual consultations, assess their symptoms, schedule appointments, receive emergency assistance, and communicate with health care providers. Penetration of smartphones and adoption of digital health solutions will keep on increasing the size of the addressable user base for Android apps.
The iOS segment is expected to register the fastest growth in the urgent care apps market, driven by increasing adoption of secure, user-friendly digital healthcare applications among consumers and healthcare professionals. The iOS platforms allow for advanced applications features, smooth integration with other connected devices, safe data handling, and personalized medical services. The increasing popularity of remote consultations, remote symptoms checking, digital triaging, and instant communication will further boost the use of iOS in advanced technology healthcare markets.
By Type, post-hospital apps dominates the urgent care apps market, pre-hospital emergency care & triaging apps grows fastest
The post-hospital apps have a strong presence in the market owing to their significance in ensuring that the patients are taken care of after being discharged from the hospitals. The healthcare organizations benefit from such apps in terms of lowering readmission rates and ensuring patients are adhering to medications among others. The increasing emphasis by healthcare organizations on value-based healthcare that rewards low readmission rates is another key reason why post-hospital apps remain the largest type category of urgent care apps.
Pre-hospital emergency care and triaging apps are the fastest-growing type as health systems and emergency medical services increasingly adopt communication platforms that streamline coordination between ambulance crews and hospital emergency departments before a patient arrives. This growth is reinforced by continued acquisition and product investment activity among established clinical communication vendors expanding into pre-hospital workflows, as health systems prioritize accelerating time-to-treatment for trauma, stroke, and cardiac emergencies where minutes directly affect patient outcomes.
By Clinical Area, trauma dominates the urgent care apps market, stroke grows fastest
Trauma is the leading clinical area among the urgent care app categories since trauma patients are some of the most time-sensitive and communicative emergencies. The need to share information efficiently between the various parties involved in the treatment process is important to ensure the best possible outcome. The commonality of trauma cases in urban and rural healthcare facilities is why trauma remains the dominant category.
Stroke represents the fastest-growing clinical area as rising global stroke incidence, with more than 13.7 million new cases registered annually according to World Stroke Organization data, continues to drive health system investment in rapid stroke response communication platforms. This growth is reinforced by the well-established clinical imperative around minimizing time-to-treatment for stroke patients, where urgent care apps enabling pre-hospital stroke alert and rapid specialist consultation can meaningfully improve treatment eligibility and patient outcomes.
By End-User, hospitals & clinics dominates the urgent care apps market, patients grows fastest
The hospitals & clinics segment led the market for urgent care apps in 2025 because of the increasing use of technology for patient triage, communication, appointments scheduling, monitoring from a distance, and after hospitalization. The healthcare industry uses urgent care apps to optimize patients' processes, communicate effectively with patients and healthcare professionals, and offer services outside physical facilities. The digitization of healthcare and the need for efficient management of patient volume have helped boost their adoption.
The Patients segment is forecasted to grow at the fastest pace owing to the growing inclination towards convenient healthcare services. Urgent care applications offer a wide range of facilities such as obtaining advice about symptoms, virtual consultations, appointments, medicines, and other follow-ups without necessarily visiting doctors in person. Increased usage of smartphones, increased telemedicine usage, and rising consumer expectations from healthcare service providers have led to an increase in the usage of urgent care apps.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
84.60% |
|
Asia Pacific |
China |
39.60% |
|
Europe |
Germany |
27.80% |
|
Middle East & Africa |
Saudi Arabia |
26.40% |
|
Latin America |
Brazil |
29.80% |
North America Urgent Care Apps Market Insights
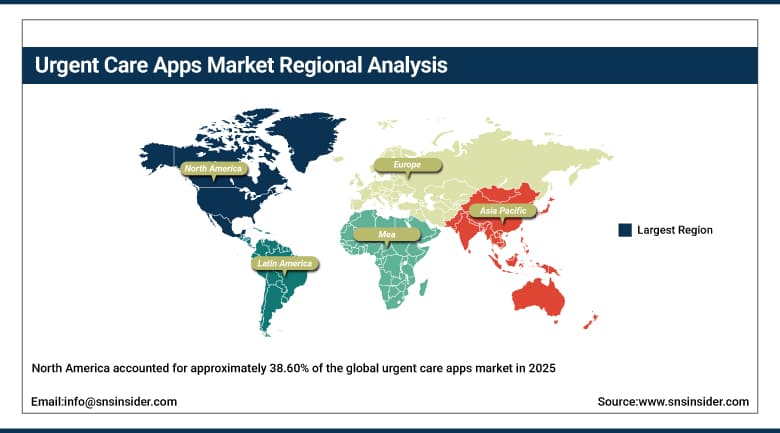
North America accounted for approximately 38.60% of the global urgent care apps market in 2025, making it the largest regional market, driven by the region's well-established healthcare infrastructure and high rate of digital technology adoption among hospitals, emergency medical services, and health systems. The United States accounts for the substantial majority of regional demand, anchored by a concentrated base of established clinical communication vendors and health systems pursuing unified, technology-enabled care coordination.
Canada is contributing incremental demand as regional health systems continue to invest in digital care coordination technology. Despite slower growth in percentage terms when compared to emerging economies, North America is projected to maintain its leadership in the market because of ongoing consolidation and investments by vendors in their products within the domestic clinical communication platforms.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Urgent Care Apps Market Insights
The Asia Pacific region is the fastest-growing market, with a growth rate of about 41.60% between 2026 to 2035, which is due to an increased number of smartphones, investments in digital health infrastructure, and government efforts promoting telemedicine and digital health adoption in China, India, and Southeast Asian countries. The digital health ecosystem in China keeps on driving quick platform scaling, and there is an addition of scale coming from Japan, which has many clinical communication technology developers in the region.
India and Southeast Asian markets are contributing significant incremental growth as expanding healthcare digitization initiatives extend urgent care app adoption into a broader range of healthcare settings. This combination of smartphone penetration growth and healthcare digitization investment is expected to sustain Asia Pacific's position as the fastest-growing market through the forecast period.
Europe Urgent Care Apps Market Insights
Europe is another region that constitutes an important market segment for the urgent care apps market owing to the size of the healthcare technology industry in Germany and the focus of Europe towards the transformation of its health system through digital means. Europe continues to make investments in clinical communication systems that can comply with European healthcare regulations.
The Netherlands, home to established clinical communication vendor Siilo, alongside the United Kingdom and France, are contributing steady demand growth as regional health systems extend urgent care app adoption from pilot programs into broader clinical deployment. Regional vendors continue to invest in HIPAA-equivalent, GDPR-compliant messaging platforms to serve the region's healthcare data protection requirements.
MEA & Latin America Urgent Care Apps Market Insights
The Middle East & Africa market is growing as the demand for digital health solutions increases, with such applications offering virtual consultations, health tracking, and medication management services to make healthcare more accessible. In the kingdom of Saudi Arabia, the market for telemedicine applications is growing steadily, which shows the growing demand for digital health solutions in the region and further adoption of urgent care apps.
Latin American market is dominated by Brazil, where rising healthcare digitalization has been continuously fueling the development of urgent care applications in a gradual manner. The contribution of Mexico can be seen in terms of growth due to digital healthcare projects in the region. Overall, the adoption of such technology solutions is limited to the bigger health care systems only.
Market Dynamics
Growth Drivers: Digital Health Adoption and Time-Critical Care Coordination
Growing internet penetration and smartphone connectivity represent the primary driver of urgent care apps market growth, as rising digital access continues to expand the population capable of using mobile applications to access urgent medical care and information. Increasing demand for patient-centric healthcare continues to reinforce this trend, as consumers increasingly expect on-demand, digitally mediated access to medical guidance and care coordination comparable to other digital service categories.
The increasing prevalence of time-critical health disorders, including stroke, trauma, and cardiovascular conditions, represents a second major growth driver, as health systems increasingly recognize that rapid, coordinated communication between EMS, hospital, and specialist care teams directly affects patient outcomes for these conditions. Rising health system investment in unifying communication across pre-hospital, in-hospital, and post-hospital care settings continues to reinforce adoption as care coordination increasingly extends beyond traditional hospital walls.
Restraints: Data Security Concerns and App Reliability Challenges
In terms of data security and privacy issues, these pose an important constraint in the growth of the market, as the use of such apps in the health sector involves weighing convenience against the sensitive nature of the health information that is being exchanged using these platforms. There needs to be continued investment on the part of vendors in certification and compliance capabilities as a way of overcoming the adoption constraint.
Inconsistency in app reliability and dependence on correct user input represent a further restraint, as urgent care apps must function reliably under time-critical, high-stress conditions where communication failures or data entry errors could meaningfully affect patient outcomes. This reliability requirement creates a higher quality and testing bar for urgent care app vendors relative to less clinically critical digital health applications.
Opportunities: AI-Driven Triage Integration and Care Continuum Unification
Continued integration of AI-driven triage, symptom assessment, and predictive analytics capability represents a substantial opportunity, as vendors that can meaningfully improve clinical decision-support accuracy are positioned to differentiate beyond basic communication functionality toward genuine clinical workflow enhancement. Vendors pursuing this capability are extending urgent care apps' role from simple messaging tools into more sophisticated platforms capable of supporting real clinical decision-making.
The continued unification of communication across the full care continuum, spanning pre-hospital, in-hospital, and post-hospital settings, offers a further avenue for growth, as health systems increasingly seek single, integrated platforms rather than fragmented point solutions for each care setting. Vendors that can offer comprehensive, end-to-end care coordination capability through both acquisition and in-house development are well positioned to capture demand from health systems pursuing unified clinical communication strategies.
Recent Developments:
-
2026: Medisafe partnered with AssistRx to strengthen connected patient engagement, combining digital medication-support capabilities with patient services to improve therapy participation and healthcare coordination.
-
2026: AlayaCare expanded its AI-powered home-care capabilities through AlayaFlow, introducing workflow automation for intake, scheduling, clinical documentation, and billing processes across home-based care operations.
-
2026: Stryker expanded its connected-care strategy through its SmartHospital Platform, integrating digital technologies across patient rooms and operating environments to support connected healthcare delivery.
Urgent Care Apps Market Key Players are:
-
Pulsara (CommuniCare Technology, Inc.)
-
Stryker Corporation (Vocera Communications)
-
PatientSafe Solutions, Inc.
-
Baxter International Inc. (Hill-Rom)
-
Hospify Ltd.
-
Johnson & Johnson Health & Wellness Solutions, Inc.
-
Imprivata, Inc.
-
Medisafe
-
Siilo B.V.
-
AlayaCare Inc.
-
Smartpatient GmbH (MyTherapy)
-
Forward Health
-
Zocdoc Inc.
-
Teladoc Health, Inc.
-
Ada Health GmbH
-
MDLIVE, Inc.
-
Brave Care, Inc.
-
Epic Systems Corporation
Urgent Care Apps Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 4.51 Billion |
| Market Size by 2035 | USD 117.85 Billion |
| CAGR | CAGR of 38.58% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Pre-Hospital Emergency Care & Triaging Apps, In-Hospital Communication & Collaboration Apps, Post-Hospital Apps) • By Platform (iOS, Android, Web-based) • By Clinical Area (Trauma, Stroke, Cardiac Conditions, Rashes & Allergies, Musculoskeletal Pain & Injuries, Others) • By End-User (Hospitals & Clinics, Emergency Medical Services (EMS), Patients) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | TigerConnect, Inc., Pulsara (CommuniCare Technology, Inc.), Allm Inc., Stryker Corporation (Vocera Communications), PatientSafe Solutions, Inc., Baxter International Inc. (Hill-Rom), Hospify Ltd., Johnson & Johnson Health & Wellness Solutions, Inc., Imprivata, Inc., Medisafe, Siilo B.V., AlayaCare Inc., Smartpatient GmbH (MyTherapy), Forward Health, Zocdoc Inc., Teladoc Health, Inc., Ada Health GmbH, MDLIVE, Inc., Brave Care, Inc., Epic Systems Corporation |
Frequently Asked Questions
Key players include TigerConnect, Inc., Pulsara, Allm Inc., Stryker Corporation (Vocera Communications), PatientSafe Solutions, Inc., and Siilo B.V., among other clinical communication and digital health platform providers.
Continued integration of AI-driven triage and predictive analytics capability and continued unification of communication across pre-hospital, in-hospital, and post-hospital care settings represent the primary opportunities.
Growth is primarily driven by growing internet penetration and smartphone connectivity combined with the increasing prevalence of time-critical health disorders requiring rapid, coordinated care communication.
By Type, Post-Hospital Apps dominated the market with approximately 36.60% share in 2025, reflecting their pivotal role in managing patient care and reducing readmissions after discharge.
North America dominated the market with approximately 38.60% share in 2025, driven by the region's well-established healthcare infrastructure and high rate of digital technology adoption.
