
Wearable Camera Market Report Scope & Overview:
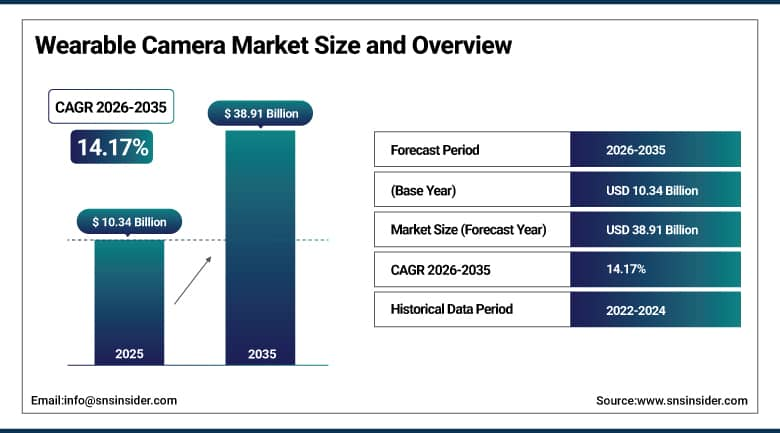
The Wearable Camera Market was valued at USD 10.34 Billion in 2025 and is expected to reach USD 38.91 Billion by 2035, growing at a CAGR of 14.17% from 2026-2035.
The Wearable Camera Market covers compact cameras and accessories that are worn on the head, body, ear or eyewear to capture hands-free photos and video. Products include action cameras for sports and travel, body-worn cameras used by police and security staff, and smart glasses that combine cameras with audio and artificial intelligence assistants. Demand comes from adventure sports, content creation, law enforcement transparency programs, healthcare training and industrial inspection. Better sensors, longer batteries, on-device artificial intelligence and falling prices support strong growth through 2035. Suppliers include action camera specialists, public safety technology firms and consumer technology platforms. Government funding for public safety programs provides further support.
⮞The International Telecommunication Union reported on 17 November 2025 that about 6 billion people, roughly three-quarters of the world’s population, were online in 2025.
To Get More Information On Wearable Camera Market - Request Free Sample Report
Wearable Camera Market Trends
-
Smart glasses with built-in cameras and voice assistants are moving from early adopters toward mainstream consumers.
-
Body-worn cameras are adding on-device artificial intelligence for transcription, license scanning and automatic activation.
-
Action cameras are adopting larger one-inch sensors, variable apertures and 8K recording while staying waterproof and compact.
-
Cloud platforms that manage, redact and share footage are becoming a recurring revenue stream for camera vendors.
-
Open-gate and 360-degree capture are letting creators reframe video after shooting, which suits social media formats.
U.S. Wearable Camera Market Outlook
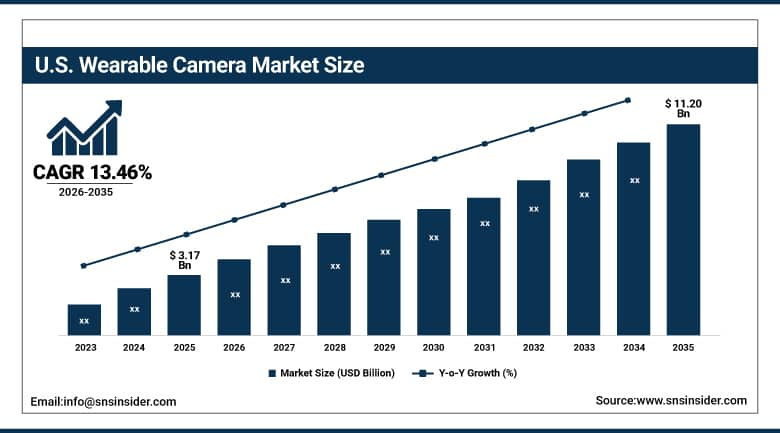
The U.S. Wearable Camera Market was valued at USD 3.17 Billion in 2025 and is expected to reach USD 11.20 Billion by 2035, growing at a CAGR of 13.46% from 2026-2035.
The US Wearable Camera Market is the largest market in North America. Factors such as the adoption of body worn cameras by law enforcement organizations, presence of outdoor activities and adventure sport cultures in the region, and early adoption of smart glasses make the US the largest market. Government grants at the federal and state levels support local authorities to purchase the cameras and data storage facilities; additionally, there are legal requirements from courts and communities for evidence. Individuals buy action cameras for activities such as cycling, skiing, surfing, and travel. Content creators prefer compact and stabilized cameras. Platform holders and eyewear companies are making large investments in camera glasses.
⮞The U.S. Department of Justice, through its Bureau of Justice Assistance, released the fiscal 2026 Body-Worn Camera Policy and Implementation Program on 13 August 2026, offering 16 awards to law enforcement and correctional agencies.
Wearable Camera Market Segment Analysis
-
By Type, the Head Mount segment dominated the Wearable Camera Market with approximately 51.46% share in 2025, while the Ear Mount & Smart Glass segment is the fastest growing with a CAGR of approximately 17.62%.
-
By Product, the Camera segment dominated the Wearable Camera Market with approximately 86.27% share in 2025, while the Accessories segment is the fastest growing with a CAGR of approximately 15.84%.
-
By Application, the Sports & Adventure segment dominated the Wearable Camera Market with approximately 46.18% share in 2025, while the Healthcare segment is the fastest growing with a CAGR of approximately 18.74%.
-
By Sales Channel, the Offline segment dominated the Wearable Camera Market with approximately 56.73% share in 2025, while the Online segment is the fastest growing with a CAGR of approximately 16.28%.
By Type, Head Mount Dominates the Wearable Camera Market and Ear Mount & Smart Glass Grows Fastest
Head-mounted cameras hold approximately 51.46% of the Wearable Camera Market in 2025. This type includes helmet cameras, headbands and compact action cameras that attach to helmets for cycling, skiing, motorsport and climbing, and it benefits from a first-person perspective that suits adventure content. Established action camera brands sell millions of units each year, and a large accessory ecosystem of mounts and housings supports repeat purchases. Strong sales of mounts for helmets, handlebars and chests keep the ecosystem active. Low weight and a secure fit are decisive for buyers who use cameras during intense activity. Compact size lets them blend into protective gear.
Ear mount and smart glass products are the fastest growing type, with a CAGR of approximately 17.62% during 2026-2035. Camera glasses look like ordinary eyewear, capture photos and video hands-free and connect to artificial intelligence assistants that translate, identify objects and answer questions. Eyewear makers, technology platforms and consumer electronics firms are all launching products, and fashion partnerships are widening appeal beyond technology enthusiasts. Prescription lens options and lightweight frames are removing earlier barriers to everyday use. Battery life and thermal limits in small frames remain the main design hurdles that vendors are working to solve. Fashion collaborations widen appeal further.
⮞The Camera & Imaging Products Association of Japan reported in August 2026 that digital camera shipments in the first half of 2026 rose about 0.5% year on year, with fixed-lens compact cameras up 16%.
By Product, Camera Dominates the Wearable Camera Market and Accessories Grow Fastest
Cameras make up 86.27% of the market because all purchasing starts with the cameras themselves. They come in many price ranges starting from basic action cameras through professional body-worn cameras and top-range 360-degree cameras. As the sensor technology advances and more features such as stabilizers and battery capacity, buyers will continue to upgrade their equipment. The law enforcement will be purchasing cameras in bulk amounts and possibly together with docking stations and licenses for software. Improvement of the sensor technology drives the buyers to replace their old equipment with better video performance. Lens kits for different fields of vision accompany the new cameras.
Accessories are the fastest growing product segment, at a CAGR of approximately 15.84% through 2035. Mounts, extra batteries, memory cards, lenses, filters, microphones, docking stations and protective housings are bought to customize cameras for different activities. Vendors build accessory ecosystems because margins are healthy and customers tend to stay within a brand. Subscription cloud storage is an additional recurring offering. Third-party accessory makers add choice. Cloud storage subscriptions bundled with accessories lift the lifetime value of each camera customer. Charging cases and power banks designed for cameras sell steadily.
⮞Japan’s Ministry of Internal Affairs and Communications reported in May 2026 that 91.8% of Japanese households owned a smartphone in 2025, up from 90.5% a year earlier.
By Application, Sports & Adventure Dominates the Wearable Camera Market and Healthcare Grows Fastest
Sports and adventure accounts for approximately 46.18% of the market in 2025. Cycling, skiing, surfing, diving, motorsport, hiking and travel all generate demand for rugged, waterproof and stabilized cameras. Social media platforms reward immersive first-person footage, and creators upgrade equipment frequently. Brands run athlete sponsorships and content contests that keep the category visible to casual buyers. Seasonal tourism and holiday travel create reliable annual peaks in unit sales. Steady growth in mountain biking, trail running and water sports widens the base of enthusiastic users. Travel influencers extend the audience further.
Healthcare is the fastest growing application, with a CAGR of approximately 18.74% during 2026-2035. Surgeons and trainers use head-mounted cameras to record procedures for education and review, nurses use body cameras to document care and protect staff in emergency departments, and telemedicine providers use wearable video to guide remote assistance. Patient safety programs and teaching hospitals are expanding their use of video. Rising spending on clinical training and patient safety supports adoption. Remote consultations and simulation training are further widening the range of wearable video users in hospitals.
⮞The Outdoor Industry Association reported on 17 June 2026 that 183.2 million Americans, a record 59% of people aged 6 and over, took part in outdoor recreation in 2025.
By Sales Channel, Offline Dominates the Wearable Camera Market and Online Grows Fastest
Offline channels account for approximately 56.73% of the market in 2025. This channel includes direct institutional sales to police departments, security firms and healthcare systems, along with specialist camera shops, sports retailers and electronics chains. Institutional buyers prefer tendered contracts with training, support and integration, while consumers often want to handle a camera before purchase. After-sales service networks and training support also favor physical channels. Integrators and resellers add services such as installation and configuration for enterprise buyers. Trade shows also help vendors win institutional contracts.
Online is the fastest growing channel, with a CAGR of approximately 16.28% during 2026-2035. Brand websites and marketplaces offer product comparison, creator reviews, bundles and fast delivery, and they are particularly effective for action cameras and smart glasses launched with online campaigns. Direct-to-consumer sales also give makers access to customer data that guides accessory and software offers. Livestream retail in Asia has become a notable outlet for new releases. Bundles of cameras with software trials and extended warranties are pulling more shoppers online. Affiliate marketing drives sales.
⮞The Telecom Regulatory Authority of India reported on 12 October 2026 that India had 1,114.17 million internet subscribers as of 30 June 2026.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
80.37% |
|
Europe |
Germany |
22.46% |
|
Asia Pacific |
China |
38.71% |
|
Latin America |
Brazil |
49.38% |
|
Middle East & Africa |
United Arab Emirates |
28.74% |
North America Wearable Camera Market Insights
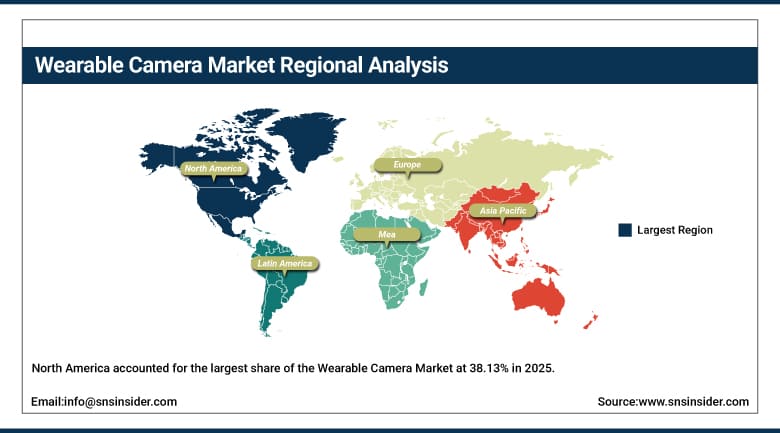
North America accounted for the largest share of the Wearable Camera Market at 38.13% in 2025, with the United States contributing about 80.37% of regional demand and Canada the balance. The region has the world’s largest body-worn camera deployments among police forces, a strong outdoor recreation culture and the headquarters of several leading camera and smart glasses companies. Affluent consumers adopt new devices early, and retailers stock a wide range. Large public safety grants and budgets support steady replacement cycles for agencies. Strong software ecosystems, including evidence management platforms, give regional vendors an advantage. Some agencies are piloting AI-enabled models. Canada's police services are scaling deployments.
Canada is regarded as the fastest growing country in the region as provincial police services roll out body-worn cameras and outdoor tourism expands. Mexico, which belongs to Latin America, is a growing market for security and consumer cameras. Buyers value cloud integration, evidence management and privacy controls, and procurement cycles tied to public budgets influence timing. Retail partnerships with sporting goods chains broaden consumer reach. Sports and outdoor retailers carry wide ranges. Strong venture funding supports start-ups in camera glasses.
⮞The Consumer Technology Association reported on 5 January 2026 that U.S. consumer technology unit shipments were forecast to grow 0.7% in 2026.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Wearable Camera Market Insights
Europe held approximately 26.37% of the Wearable Camera Market in 2025, with the United Kingdom, Germany, France, Italy and the Nordic countries leading demand. Police forces and security services are increasing use of body-worn video, and winter sports, cycling and sailing communities support consumer sales. Strict data protection rules shape product design and storage practices. Cross-border police cooperation also fosters standardization of evidence handling. National programs to modernize policing also support equipment spending. Large festivals and sporting events add temporary demand for security cameras.
Germany is the largest market, with about 22.46% of regional demand, followed by the United Kingdom and France. Retailers range from specialist outdoor shops to large electronics chains, and online sales are rising. European buyers emphasize privacy compliance, encryption and data residency, which gives local cloud partners a role, while smart glasses are drawing interest in fashion capitals. Cycling and winter sports clubs add enthusiastic communities of buyers across the continent. Public tenders typically favor vendors with strong local support. Retail gift seasons lift consumer volumes.
⮞Eurostat reported on 23 April 2026 that 40% of European Union citizens lacked basic digital skills in 2025.
Asia Pacific Wearable Camera Market Insights
Asia Pacific accounted for approximately 25.46% of the Wearable Camera Market in 2025 and is the fastest growing region, with a CAGR of 16.34% during 2026-2035. The region is home to leading camera and smart glasses makers and has enormous populations of smartphone users who are moving into video creation. China, Japan, South Korea, India and Australia all contribute, with strong demand from vloggers, travelers and security users. Large manufacturing clusters in Shenzhen supply many global brands. Strong exports from the region also supply cameras to buyers across other continents.
China is the largest country market, with 38.71% of regional demand, backed by major action camera, drone and smart glasses brands and a huge social video ecosystem. Japan has a mature camera culture and strong imaging component suppliers, while India is expanding as police forces and consumers adopt cameras. Australia adds demand from surfing, diving and outdoor tourism. Government smart city projects create demand from public safety users. Rising incomes expand the market among younger adults. Vlogging culture in Southeast Asia is a major consumer driver.
⮞The China Academy of Information and Communications Technology reported on 11 August 2026 that China’s mobile phone shipments reached 133 million units in the first half of 2026, with 5G models at 92.0%.
MEA & Latin America Wearable Camera Market Insights
The Middle East and Africa and Latin America together account for approximately 10.04% of the Wearable Camera Market in 2025, with Latin America at 6.20% and the Middle East and Africa at 3.84%. In the Gulf, the United Arab Emirates and Saudi Arabia are deploying body-worn cameras in policing and smart city programs and are early adopters of smart glasses. South Africa, Kenya and Nigeria show growing security and consumer demand. Government procurement is the main source of institutional demand. Smart glasses are drawing early interest among affluent consumers in the Gulf.
Latin America is led by Brazil and Mexico, where security concerns support body-worn camera programs and a young population drives action camera and creator equipment sales. Argentina, Colombia and Chile add smaller volumes. Imports dominate supply, so currency swings and import duties influence prices, and distributors and online marketplaces are the main routes to buyers. Retail partnerships with telecom operators extend reach. Local resellers often provide training and service. Rising online shopping improves access in secondary cities. Distributor credit supports sales.
⮞The Brazilian Institute of Geography and Statistics reported on 2 July 2026 that 89.8% of Brazilians aged 10 and over owned a mobile phone in 2025.
Market Dynamics
Growth Drivers: Police Accountability Programs and Creator Culture Drive Growth in the Wearable Camera Market
Programs for police accountability are the strongest institutional force behind the Wearable Camera Market. Governments and communities expect recorded evidence of public encounters, and agencies are moving from pilots to full deployments with cameras, docking stations and evidence software. Each deployment creates recurring revenue through storage, software licenses and refresh cycles of a few years. Training programs and community engagement efforts help build public acceptance. Legislation in several jurisdictions now requires or funds the use of cameras, which provides lasting demand. Many agencies also report better complaint resolution times after adoption.
Creator culture is the second driver on the consumer side. Short-form video platforms reward immersive first-person content, and action cameras, 360-degree cameras and camera glasses make it easy to capture it. Better stabilization, low-light performance and automatic editing tools lower the skill barrier, which brings casual users into the market. Influencers and athletes act as informal sales channels for new devices. Rising incomes among younger consumers expand the number of buyers in emerging markets. Gaming and streaming communities add another group of heavy users who upgrade often. Corporate security teams are also trialing body cameras for staff safety.
⮞The Royal Canadian Mounted Police reported on 17 March 2026 that body-worn cameras were deployed at 90 of 185 detachments in British Columbia, with full deployment expected in fall 2027.
Restraints: Privacy Concerns and Data Management Burdens Restrain Growth in the Wearable Camera Market
Privacy concerns restrain the Wearable Camera Market. Camera glasses and always-on devices raise worries about recording people without consent, and venues, schools and employers are introducing restrictions. Regulators in several countries are examining facial recognition and data retention, which can slow adoption of smart glasses and complicate product design. Some venues, gyms and clinics already ban recording eyewear. Public debate about surveillance creates reputational risk for vendors. Employees may also resist continuous recording at work, which slows enterprise rollouts and calls for clear policies.
Data management burdens add costs for institutional buyers. Agencies must store, review, redact and release large volumes of footage, and delays or missing recordings can undermine confidence in programs. Budget constraints, union negotiations and training needs prolong purchasing cycles. Battery life and heat in compact devices remain engineering challenges. Cybersecurity expectations for stored footage add further compliance work. Replacement of hardware can add to total cost of ownership. Integration with legacy records systems often proves complex and costly for smaller agencies. Vendors are responding with encryption and audit tools.
⮞The New York City Comptroller reported on 31 October 2025 that the New York Police Department failed to answer 85% of body-camera footage requests within 25 business days.
Opportunities: Artificial Intelligence Features and Healthcare Uses Create Opportunities in the Wearable Camera Market
Artificial intelligence features create a major opportunity. On-device processing can transcribe speech, translate languages, identify objects, scan documents and summarize scenes, which turns a camera into an assistant. Camera glasses and body cameras both benefit, and vendors that build open software platforms can attract developers and recurring subscription revenue. Developers building apps for glasses and body cameras expand the value of each installed device. Wake-word and gesture control make interaction more natural for users. Partnerships with phone makers extend reach. Gesture recognition adds further utility.
Healthcare, training and industrial inspection offer a second opening. Hands-free video supports remote expert assistance, surgical education, nurse safety and field maintenance, and companies see productivity gains from guided workflows. Rising adoption of artificial intelligence tools by internet users also prepares the ground for wearable assistants in daily life. Remote support and field service use cases are growing quickly. Insurers and utilities are exploring wearable video for claims and field inspections. Warehouse and construction firms are early adopters. Training budgets are growing.
⮞The Communications, Space and Technology Commission of Saudi Arabia reported on 19 July 2026 that 45.2% of internet users in the Kingdom used artificial intelligence tools.
Recent Developments:
- 2025: DJI released the Osmo Action 6, an action camera with a 1/1.1-inch sensor, a variable f/2.0 to f/4.0 aperture, 4K recording at 120 fps, 50 GB of internal storage and 20 m waterproofing.
- 2026: GoPro announced the Mission 1 series, built around a 50 MP one-inch sensor with 8K60 and 4K240 recording and 20 m waterproofing, with shipments starting on 28 May 2026.
- 2026: Meta introduced the third-generation Ray-Ban Meta glasses with a 12 MP camera, 3K Ultra HD video and battery life of up to nine hours at its Connect event.
- 2026: Axon announced the Axon Body 5 and Body 5 Pro body cameras with 25 times the artificial intelligence processing of earlier generations and 20% longer battery life.
Wearable Camera Market Key Players are:
-
Axon Enterprise, Inc.
-
Motorola Solutions, Inc.
-
GoPro, Inc.
-
SZ DJI Technology Co., Ltd.
-
Arashi Vision Inc. (Insta360)
-
Meta Platforms, Inc.
-
Alibaba Group Holding Limited
-
Google LLC
-
Xiaomi Corporation
Wearable Camera Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 10.34 Billion |
| Market Size by 2035 | USD 38.91 Billion |
| CAGR | CAGR of 14.17% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Head Mount, Body Mount, Ear Mount, and Smart Glass) • By Product (Camera and Accessories) • By Application (Sports and Adventure, Security and Law Enforcement, Healthcare, Industrial, Media and Entertainment, and Others) • By Sales Channel (Offline and Online) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Axon Enterprise, Inc., Motorola Solutions, Inc., GoPro, Inc., SZ DJI Technology Co., Ltd., Arashi Vision Inc. (Insta360), Meta Platforms, Inc., Alibaba Group Holding Limited, Google LLC, Xiaomi Corporation |

Frequently Asked Questions
The key players in the Wearable Camera Market include Axon Enterprise, Inc., Motorola Solutions, Inc., GoPro, Inc., SZ DJI Technology Co., Ltd., Arashi Vision Inc. (Insta360), among others.
Key opportunities include on-device artificial intelligence features such as translation and transcription, and healthcare, training and industrial inspection uses of hands-free video.
The major growth factor is the expansion of police accountability programs, supported by rising creator culture that drives consumer demand for action cameras and camera glasses.
The Head Mount segment dominated the Wearable Camera Market with approximately 51.46% share in 2025, because helmet and action cameras suit adventure content and have established accessory ecosystems.
North America dominated the Wearable Camera Market with a 38.13% share in 2025, supported by large police deployments, outdoor recreation culture and the presence of leading camera and smart glasses companies.
