
Wireless Brain Sensors Market Report Scope & Overview:
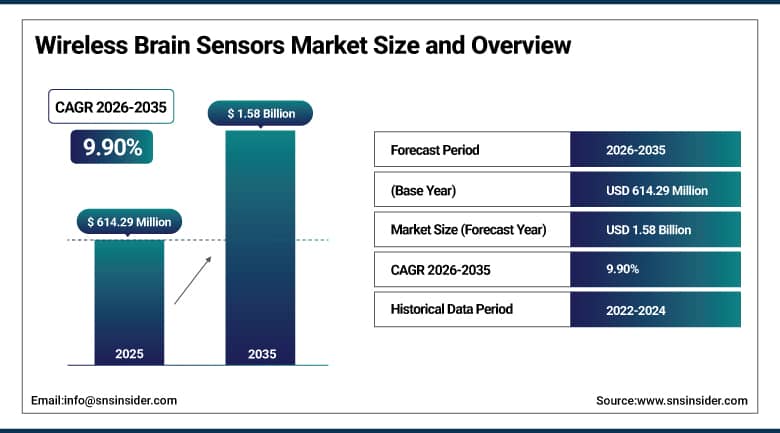
The Wireless Brain Sensors Market was valued at USD 614.29 Million in 2025 and is expected to reach USD 1.58 Billion by 2035, growing at a CAGR of 9.90% from 2026-2035.
The Wireless Brain Sensors Market is expanding as brain monitoring moves out of hospital rooms and into homes, clinics and research labs. Wireless headsets, patches and earbuds record electrical brain activity without cables, which makes tests faster and more comfortable. Epilepsy, dementia, stroke and head injury all need frequent assessment, and wireless sensors lower the cost of each recording. Artificial intelligence now reads signals at the bedside and flags seizures or delirium. Longer battery life and dry electrodes support multi-day use. Consumer neurotechnology and brain-computer interface research add new demand. Privacy rules and clinical validation remain hurdles, but investment is rising and clearances are being granted.
⮞In October 2025, the World Health Organization reported that neurological disorders cause over 11 million deaths a year and affect more than 3 billion people. The burden shows the scale of demand for accessible brain monitoring.
To Get More Information On Wireless Brain Sensors Market - Request Free Sample Report
Wireless Brain Sensors Market Trends:
-
Wireless EEG headbands and patches for rapid bedside seizure detection
-
Artificial intelligence algorithms that read brain signals and flag delirium or seizures
-
Dry-electrode and earbud designs that support multi-day home recording
-
Consumer neurotechnology and brain-computer interface products entering the market
-
Neural data privacy rules and ethics frameworks shaping product design
U.S. Wireless Brain Sensors Market Outlook:
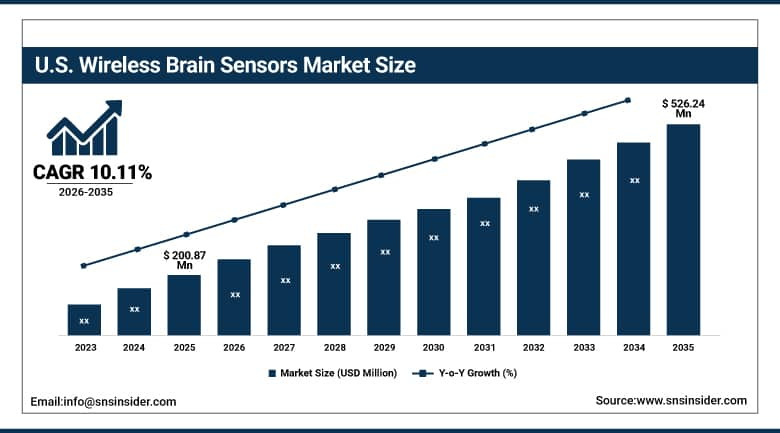
The U.S. Wireless Brain Sensors Market was valued at USD 200.87 Million in 2025 and is expected to reach USD 526.24 Million by 2035, growing at a CAGR of 10.11% from 2026-2035.
The U.S. Wireless Brain Sensors Market is the largest national market, supported by a high burden of brain injury, dementia and epilepsy. Hospitals face shortages of EEG technologists and limited night coverage. Rapid-setup wireless headsets let nurses start a recording within minutes. The Food and Drug Administration has cleared several wireless EEG systems in recent years, and payers are testing coverage for new indications. Neurologists also use home systems to record several days of activity. Venture funding is strong, and consumer brands are adding brain sensing to headphones and earbuds. Reimbursement gaps and data privacy laws remain hurdles. Growth is expected to stay steady.
⮞In April 2026, the Centers for Disease Control and Prevention reported 68,663 deaths related to traumatic brain injury in the United States in 2023. The toll shows why hospitals are seeking faster and more portable brain assessment tools.
Wireless Brain Sensors Market Segment Analysis:
-
By Product Type, the EEG Devices segment dominated the Wireless Brain Sensors Market with approximately 47.83% share in 2025 and is also the fastest growing with a CAGR of approximately 10.40%.
-
By Application, the Traumatic Brain Injury segment dominated the Wireless Brain Sensors Market with approximately 30.95% share in 2025, while the Dementia segment is the fastest growing with a CAGR of approximately 11.00%.
-
By End User, the Hospitals and Neurology Centers segment dominated the Wireless Brain Sensors Market with approximately 40.45% share in 2025, while the Home Care Settings segment is the fastest growing with a CAGR of approximately 11.35%.
-
By Connectivity, the Bluetooth Low Energy segment dominated the Wireless Brain Sensors Market with approximately 48.00% share in 2025, while the Wi-Fi segment is the fastest growing with a CAGR of approximately 10.90%.
By Product Type, EEG Devices Dominates the Wireless Brain Sensors Market and Is Also the Fastest Growing
EEG devices lead because electroencephalography is the first test ordered for seizures, encephalopathy, sleep disorders and many cognitive complaints. Wireless headsets and patches remove the cables, gel and long setup times of conventional systems. Nurses and technicians can apply them quickly, so recordings begin sooner in emergency rooms and intensive care units. Dry and semi-dry electrodes lower skin preparation time. Hospitals value the lower staffing demand, and researchers value the freedom of movement. The long clinical history of EEG supports reimbursement and training, which keeps this segment ahead of other sensor types. Vendors also bundle software, storage and review services, which raises revenue per device.
The same devices are also growing fastest because clinical use is widening. Rapid-response headbands detect non-convulsive seizures in critical care, and ambulatory patches record for days or weeks at home. Algorithms score signals automatically, which extends EEG to hospitals without neurophysiology teams. Sleep monitoring devices, magnetoencephalography systems and intracranial pressure monitors hold smaller shares but add important clinical uses. Manufacturers are improving channel counts, battery life and signal quality, and new indications such as delirium monitoring are being cleared, keeping demand strong. Pediatric clearances further extend the addressable patient group.
⮞In December 2025, Nihon Kohden stated that its aireeg system is the only 64-channel true-wireless EEG system, sampling at up to 4,000 Hz. The specification shows that wireless designs are reaching research-grade signal quality.
By Application, Traumatic Brain Injury Dominates the Wireless Brain Sensors Market and Dementia Grows Fastest
Traumatic brain injury leads because falls, road crashes and sports collisions create a large, steady stream of patients. Emergency teams need fast tools to decide who requires imaging and who can go home. Portable sensors that read brain activity at the point of care help triage concussion and more severe injury. Military and sports programs also screen for injury in the field. Intracranial pressure and transcranial Doppler sensors add monitoring for severe cases. The urgency of the use and the need for repeated assessment keep this application in the lead position. Pediatric concussion programs add further demand.
Dementia is growing fastest as populations age and drug treatments make early detection more valuable. Wireless EEG and event-related potential systems can record cognitive signals in a clinic or at home, without large imaging equipment. Researchers use them to follow disease progress and treatment response, and care providers use them to screen at-risk patients. Epilepsy, stroke, sleep disorders and Parkinson's disease remain important applications, each with distinct monitoring needs. Neurologists also use wireless sensors during rehabilitation to track recovery. Longer, home-based recordings are especially useful for conditions that vary from day to day.
⮞In 2026, the Alzheimer's Association reported that 7.4 million Americans aged 65 and older are living with Alzheimer's dementia. The number of patients shows the demand for accessible cognitive monitoring.
By End User, Hospitals and Neurology Centers Dominates the Wireless Brain Sensors Market and Home Care Settings Grows Fastest
Hospitals and neurology centers lead because they hold the equipment budgets, the trained staff and the patients with acute needs. Emergency departments, intensive care units and epilepsy monitoring units run most EEG studies. Wireless systems let them cover more beds with fewer specialists and reduce the time patients wait for a reading. Procurement teams favor devices that connect to hospital networks and electronic records. Teaching hospitals also run research programs that test new sensors. These institutions set practice standards, so their purchases influence adoption elsewhere. Purchasing is often centralized, which favors suppliers with service networks.
Home care settings are growing fastest because long recordings are more informative when taken in daily life. Conventional hospital EEG is usually limited to a few days, while wireless patches can record for several weeks. Patients avoid admission costs, and clinicians capture rare events that short stays miss. Telehealth and remote review let specialists interpret data without travel. Consumer-grade headbands for sleep and focus also expand awareness. Research institutes remain a stable user group, buying flexible systems for cognitive studies and brain-computer interface projects, and their results guide clinical design.
⮞In August 2026, Epitel stated that traditional EEG is limited to about 72 hours, while its wireless REMI system can record for several weeks. The longer window shows why home and remote recording is gaining ground.
By Connectivity, Bluetooth Low Energy Dominates the Wireless Brain Sensors Market and Wi-Fi Grows Fastest
Bluetooth Low Energy leads because it uses little power and links easily to phones, tablets and bedside computers. Most wireless EEG headsets and earbuds use it to stream signals to an app. Low energy use lets sensors run for many hours on small batteries, which suits wearable designs. Mass-market chips keep component cost low, and developers can build software on widely supported platforms. Short range is acceptable for bedside and home use. These strengths make Bluetooth the standard choice for most commercial products. Firmware updates over the air keep devices current.
Wi-Fi is growing fastest because high-channel systems need more bandwidth than Bluetooth can carry. Research and clinical headsets with dozens of channels stream data at high sampling rates to local servers. Hospitals with strong wireless networks can monitor many patients from a central station. Cloud links allow remote experts to review recordings in real time. Near-field communication and proprietary radio links serve specialized needs such as pairing and synchronization across devices. Hospitals also test mesh networks for large wards. Designers are balancing battery life against data rate as channel counts rise. Shielding and antenna design are important to avoid dropped data.
⮞In April 2026, Zeto stated that its New Wave headset has 21 soft-tip electrodes and records for up to 2.5 hours. The design shows how wireless headsets are being built for quick clinical use.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
75.00 |
|
Europe |
Germany |
26.43 |
|
Asia Pacific |
China |
38.16 |
|
Latin America |
Brazil |
49.28 |
|
Middle East & Africa |
Saudi Arabia |
29.57 |
North America Wireless Brain Sensors Market Insights
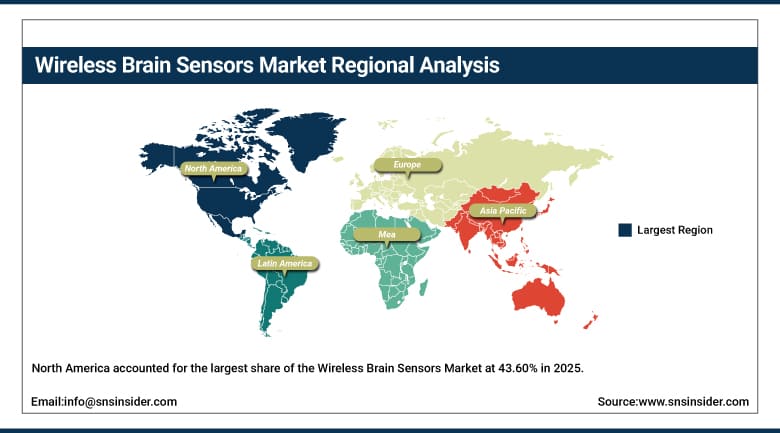
North America accounted for the largest share of the Wireless Brain Sensors Market at 43.60% in 2025, led by the United States. Hospitals face a shortage of EEG technologists and limited weekend coverage, which raises interest in rapid-setup headsets. Companies such as Ceribell, Epitel, Zeto and NextSense are based in the region, and venture funding for neurotechnology is strong. Academic centers also run trials of home recording and brain-computer interfaces. Canada adds demand through research institutes and growing adoption in tertiary hospitals. Veterans and sports medicine programs are also buying portable systems for concussion care.
The Food and Drug Administration has cleared several wireless EEG products through the 510(k) pathway, and manufacturers continue to file for new age groups, including devices for children and for new indications such as delirium. Reimbursement is still developing, and hospitals weigh cost against staffing savings. State laws on neural data privacy in Colorado, California and Montana add compliance work for consumer products. Payers are testing coverage for home recording, and technology brands are bringing brain-sensing earbuds and headphones to retail channels.
⮞In December 2025, Ceribell stated that about 31% of intensive care patients have delirium, and it received FDA 510(k) clearance for a delirium monitoring solution. The clearance shows regulators accepting wireless EEG for new bedside uses.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Wireless Brain Sensors Market Insights
Europe is the second largest region and is led by Germany, the United Kingdom, France, Italy and Spain. An aging population and strong public funding for neuroscience support demand for EEG and cognitive assessment tools. Research instrument makers such as Brain Products, Mentalab, g.tec and Bitbrain are based in Germany, Austria and Spain, and they supply universities and hospitals worldwide. The region has a large base of neurology centers, and national health systems influence which devices are purchased. Cross-border research consortia also share equipment.
The Medical Device Regulation requires strong clinical evidence and post-market surveillance, which raises entry cost for new sensors but builds clinician confidence. Notified body capacity is limited, so approval timelines can stretch. Data protection rules limit how neural data may be stored and processed. Public hospitals buy through tenders that favor proven suppliers, so smaller firms often start with research customers. European research programs on brain health and digital twins are funding wireless recording projects, and sleep clinics are adopting forehead and ear-based devices. Collaboration between academic groups and manufacturers is common, which speeds feedback on new designs.
⮞In October 2025, the European Brain Council stated that over one third of the world's population is affected by neurological conditions, in comment on the global neurology report. The statement reflects the weight of brain health on the European policy agenda.
Asia Pacific Wireless Brain Sensors Market Insights
Asia Pacific is projected to be the fastest growing region, with a CAGR of 11.50% during 2026-2035. China, Japan, India, South Korea and Australia lead regional demand. Large aging populations and rising stroke and dementia rates raise the need for monitoring, and families increasingly seek home-based care options. Nihon Kohden in Japan supplies advanced wireless EEG, and Chinese firms are investing in brain-computer interfaces and consumer neurotechnology. Hospital building programs and rising health spending in India and Southeast Asia are expanding neurology services.
Government policy is a strong driver. China has issued national guidance to build brain-computer interface industry clusters, and similar programs are emerging elsewhere in the region. Local manufacturers can price products below imports, and online retail channels carry consumer headbands. Regulators in Japan, South Korea and Australia are building approval routes for software-driven devices. Shortages of neurologists outside large cities make remote and automated reading attractive, though uneven reimbursement slows adoption. Large hospital groups in Japan and South Korea are testing automated seizure detection to ease the load on specialists.
⮞In August 2025, China's Ministry of Industry and Information Technology and six other ministries issued a brain-computer interface guideline that targets two to three industrial clusters by 2027. The policy shows state backing for neural sensing technology.
MEA & Latin America Wireless Brain Sensors Market Insights
In Latin America, Brazil is the largest market, followed by Mexico, Argentina and Colombia. Neurologists are scarce in many countries, and patients often wait long periods for an EEG. Portable wireless systems can extend testing to smaller hospitals and mobile clinics. Public health agencies are focusing on epilepsy and stroke programs, and private hospital groups in Brazil and Mexico are adding advanced monitoring. Import costs and currency swings remain obstacles for new device purchases, and tender cycles can delay orders.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Israel and South Africa lead demand. Gulf states are investing in neuroscience centers and digital health, and conferences are drawing international specialists to the region. Much of Africa has limited EEG capacity, which creates a clear need for low-cost wireless tools, though funding and trained staff are limiting factors. Partnerships with distributors and training programs are helping global suppliers build early positions. Donor programs for epilepsy care in several African countries may add demand for low-cost devices.
⮞In September 2025, the Emirates Neurological Society held the fifth Brain Diseases Conference in Abu Dhabi with more than 450 experts and over 45 lectures and workshops. The event shows growing clinical interest in brain care across the Gulf.
Market Dynamics:
Growth Drivers: Neurological Disease Burden and AI-Enabled Bedside Monitoring Drive Growth in the Wireless Brain Sensors Market
The rising burden of neurological disease is the main source of demand. Traumatic brain injury, epilepsy, stroke and dementia affect large populations, and many patients need repeated or prolonged monitoring. Population aging increases the number of people at risk, and awareness of brain health is growing among both clinicians and consumers. Wireless sensors lower the cost of each study and make testing possible in places that lack neurophysiology staff, which widens the group of patients who can be assessed. Research funding for brain health adds a further stream of equipment purchases.
Technology advances add momentum. Artificial intelligence reads signals at the bedside and flags seizures, delirium or abnormal rhythms within minutes, which reduces dependence on scarce specialists. Dry electrodes, low-power chips and better batteries make devices comfortable for multi-day wear. Telehealth links allow neurologists to review recordings remotely. Government and private funding for neuroscience and brain-computer interface research are creating new product categories and customers in clinical and consumer segments. Sleep clinics and pediatric centers are early adopters of simpler, lighter sensors.
⮞In December 2025, the Australian Institute of Health and Welfare reported that about 2.2 million Australians, or about 1 in 12, lived with a long-term neurological condition in 2022. The figure shows how common these conditions are within a single national population.
Restraints: Neural Data Privacy and Clinical Validation Hurdles Restrain Growth in the Wireless Brain Sensors Market
Neural data privacy and consent concerns are a growing restraint. Brain signals can reveal health status, attention and emotion, and regulators are drafting rules for how they may be collected and shared. Companies must invest in encryption, consent tools and data governance, which raises cost. Consumers may hesitate to wear devices that record brain activity, especially when employers or advertisers might gain access. Divergent rules among countries and states complicate product design and marketing. Breach risk adds insurance and audit costs.
Clinical validation and cost add further barriers. Many consumer headsets are not cleared for diagnosis, so hospitals cannot use them for care. Clearing a medical device requires clinical studies and quality systems that small firms find costly. Signal quality from dry electrodes can be affected by motion and hair, which limits reliability. Reimbursement for new wireless uses is limited, and implantable sensors carry safety concerns. Long development cycles slow the arrival of new products, and small manufacturers often depend on a single clearance for revenue.
⮞In November 2025, UNESCO adopted a global recommendation on the ethics of neurotechnology that warns against workplace monitoring and non-therapeutic use, particularly for children. The framework signals tighter oversight of brain-sensing products.
Opportunities: Home EEG Access and Consumer Neurotechnology Create Opportunities in the Wireless Brain Sensors Market
Home and remote EEG offers a large, under-served opportunity. Many patients with suspected seizures or sleep disorders never receive a full test because hospitals lack capacity. Wireless patches and headsets can be mailed to patients, applied at home and read by remote specialists. Payers see potential savings from avoiding admissions. Pediatric and elderly patients, who find hospital visits difficult, are especially suited to this approach. Services built around device rental and interpretation can create recurring revenue, and partnerships with telehealth firms can speed rollout.
Consumer neurotechnology and emerging markets add further potential. Headphones and earbuds with brain sensing can reach millions of users interested in focus, sleep and meditation, and licensing to audio and wearable makers can scale sales. Brain-computer interface research is producing new assistive products. Countries with few neurologists need low-cost tools, and local partnerships can reduce distribution costs. New reimbursement codes for monitoring in intensive care could open further hospital demand, particularly for seizure detection outside specialist centers. Sleep and cognitive programs add steady volume.
⮞Neurable announced in December 2025 a USD 35 million Series A round to expand its EEG-enabled headphones and licensing to device makers. The funding shows investor interest in consumer brain-sensing products.
Recent Developments:
-
In March 2025, Muse announced Muse S Athena, a headband that combines EEG with functional near-infrared spectroscopy. The product was trained on more than 80,000 sessions and extends brain sensing to cognitive fitness and meditation users.
-
In May 2025, Cognixion announced a distribution agreement with Blackrock Neurotech for Axon-R, its wearable brain-computer interface for research use. The product is not cleared for clinical use, and the deal widens access for research laboratories.
-
In June 2025, BrainScope announced the launch of a deep-learning platform called the Large Neural Model to improve brain health insights from its point-of-care EEG head injury assessment system. The platform supports faster and more consistent triage.
-
In November 2025, NextSense announced a USD 16 million Series A round to develop its EEG earbuds for sleep and brain health monitoring. The funding supports clinical studies and manufacturing scale-up.
Wireless Brain Sensors Market Key Players:
-
Ceribell, Inc.
-
Zeto, Inc.
-
Epitel, Inc.
-
NextSense, Inc.
-
Nihon Kohden Corporation
-
Interaxon Inc. (Muse)
-
Neurable Inc.
-
Beacon Biosignals, Inc.
-
Brain Products GmbH
-
EMOTIV Inc.
-
g.tec medical engineering GmbH
-
Bitbrain Technologies
-
OpenBCI
-
Mentalab GmbH
-
BrainScope Company, Inc.
-
NeuroSky, Inc.
-
Cognixion
-
Wearable Sensing
Wireless Brain Sensors Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 614.29 Million |
| Market Size by 2035 | USD 1.58 Billion |
| CAGR | CAGR of 9.90% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (EEG Devices, Sleep Monitoring Devices, MEG Devices, ICP and TCD Devices, and Others) • By Application (Traumatic Brain Injury, Epilepsy, Dementia, Sleep Disorders, Stroke, and Others) • By End User (Hospitals and Neurology Centers, Research Institutes, Home Care Settings, and Others) • By Connectivity (Bluetooth Low Energy, Wi-Fi, NFC, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Ceribell, Inc., Zeto, Inc., Epitel, Inc., NextSense, Inc., Nihon Kohden Corporation, Interaxon Inc. (Muse), Neurable Inc., Beacon Biosignals, Inc., Brain Products GmbH, EMOTIV Inc., g.tec medical engineering GmbH, Bitbrain Technologies, OpenBCI, Mentalab GmbH, BrainScope Company, Inc., NeuroSky, Inc., Cognixion, Wearable Sensing |

Frequently Asked Questions
Key players include Ceribell, Zeto, Epitel, NextSense, Nihon Kohden, Interaxon (Muse), Neurable, Beacon Biosignals, Brain Products, EMOTIV, g.tec medical engineering, Bitbrain, OpenBCI, Mentalab, BrainScope, NeuroSky, Cognixion and Wearable Sensing.
Key opportunities include home and remote EEG, artificial intelligence-based bedside monitoring, consumer neurotechnology and low-cost tools for regions with few neurologists.
The rising burden of neurological disease, together with demand for faster and more portable brain monitoring, is the main growth factor.
By Product Type, the EEG Devices segment dominated the market in 2025 with an estimated 47.83% share, supported by its use as the first test for seizures and many other brain conditions.
North America dominated the market with a share of 43.60% in 2025, driven by a high burden of brain injury and dementia, shortages of EEG technologists and strong neurotechnology funding.
