
Autonomous Navigation Market Report Scope & Overview:
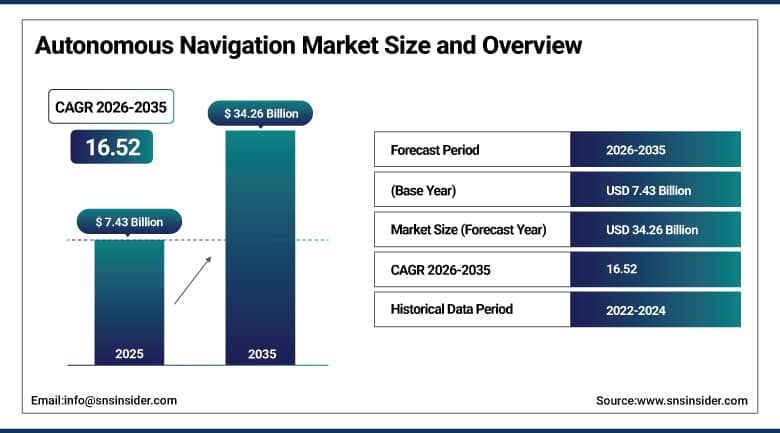
The Autonomous Navigation Market was valued at USD 7.43 Billion in 2025 and is expected to reach USD 34.26 Billion by 2035, growing at a CAGR of 16.52% from 2026-2035.
The Autonomous Navigation Market growth is driven primarily by development of AI and machine learning, global positioning system evolution, regulatory support and frameworks, automotive industry growth, and rising demand for automation across commercial, industrial, and defense applications. Autonomous navigation is employed in order to transform manned vehicles to unmanned vehicles and can help in planning, navigating, and execution of a course without human involvement through the use of technologies such as inertial navigation, GNSS, radar, lidar, cameras, odometer, barometer, ultrasound, and infrared sensors. Autonomous navigation systems comprise a number of complex systems that help in decision making depending on their environment and operation of vehicles without human interaction, which includes drones, robots, automobiles, boats, and other vehicle types.
In March 2026, Furuno Electric Co., Ltd. highlighted the commercial operation of what it described as the world’s first Level 4 autonomous container ship, marking a significant development in autonomous maritime navigation. The company also reported that four demonstration vessels received certification from Japan’s government under the MEGURI2040 Stage 2 program. These developments strengthen Furuno’s autonomous navigation and remote vessel-management capabilities while supporting the broader commercialization of highly automated shipping operations and the adoption of advanced navigation technologies across the commercial maritime sector.
To Get More Information On Autonomous Navigation Market - Request Free Sample Report
Autonomous Navigation Market Trends
- Rising integration of AI-driven navigation algorithms enabling more sophisticated real-time decision-making across platforms.
- Growing adoption of sensor fusion combining LiDAR, radar, and camera data for improved navigation accuracy and redundancy.
- Expanding development of urban air mobility solutions requiring advanced AI-driven autonomous navigation capability.
- Increasing investment in autonomous ride-hailing and robotaxi services extending beyond driver-assistance technology supply.
- Rising adoption of fully autonomous marine navigation systems supporting unmanned coastal shipping and patrol vessels.
- Growing extension of autonomous navigation technology into general-purpose robotics beyond traditional vehicle applications.
U.S. Autonomous Navigation Market Outlook
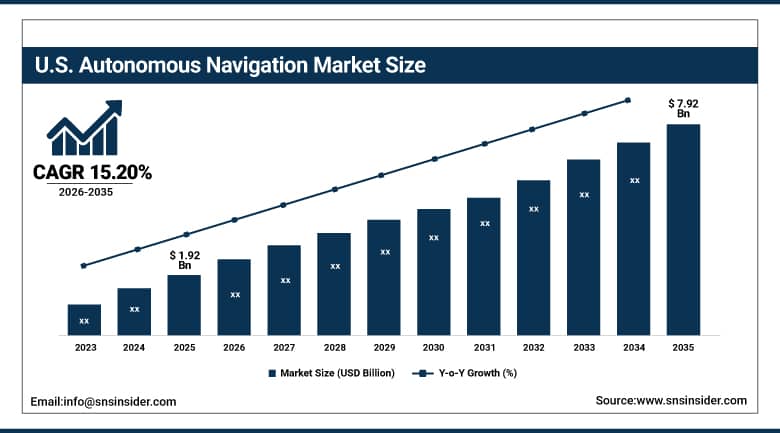
The U.S. Autonomous Navigation Market was valued at USD 1.92 Billion in 2025 and is expected to reach USD 7.92 Billion by 2035, growing at a CAGR of 15.20% from 2026-2035.
The U.S. Autonomous Navigation Market growth continues to be reinforced by significant military investments, strong presence of leading technology providers, and expanding integration in commercial and industrial autonomous platforms. The country's concentration of established semiconductor, software, and autonomous vehicle technology companies continues to anchor domestic market leadership, as automakers and technology companies increasingly compete to deliver advanced driver-assistance and fully autonomous navigation capability. Rising domestic investment in autonomous ride-hailing and robotaxi services continues to extend market demand beyond traditional driver-assistance technology supply into vertically integrated mobility service operation. Further development of the market will come as a result of increased investments in the domestic market in AI-based navigation algorithms, sensor fusion, and real-time positioning technologies for greater efficiency.
In 2025, Mobileye, along with Lyft and Marubeni, launched a joint project to expand their robotaxi service from Dallas to various other American cities using the autonomous driving technology platform developed by Mobileye. The collaboration illustrates how established domestic and international autonomous navigation technology providers continue to pursue strategic partnerships extending their platforms from underlying technology supply into direct commercial mobility service deployment, reinforcing the competitive importance of end-to-end platform capability as autonomous ride-hailing services continue to scale across major U.S. metropolitan markets.
Autonomous Navigation Market Segment Analysis
- By Component, the Sensing System segment dominated the Autonomous Navigation Market with approximately 42.60% share in 2025, while the Software segment is the fastest growing with a CAGR of approximately 18.60%.
- By Platform, the Automotive segment dominated the Autonomous Navigation Market with approximately 44.60% share in 2025, while the Marine & Offshore segment is the fastest growing with a CAGR of approximately 18.80%.
- By Sensor Type, the Camera segment dominated the Autonomous Navigation Market with approximately 32.60% share in 2025, while the LiDAR segment is the fastest growing with a CAGR of approximately 19.20%.
- By Application, the Commercial segment dominated the Autonomous Navigation Market with approximately 58.60% share in 2025, and is also the fastest growing with a CAGR of approximately 17.20%.
By Component, Sensing System Dominates the Autonomous Navigation Market and Software Grows Fastest
Sensing systems dominate the market because the physical sensor hardware, including LiDAR, radar, cameras, and GNSS receivers, represents the foundational technology required to perceive the surrounding environment across every autonomous navigation application, from automotive driver-assistance to defense unmanned vehicle platforms. The technical sophistication and precision manufacturing required for sensors capable of delivering reliable, real-time environmental data under demanding operating conditions continues to sustain sensing systems' position as the largest and most capital-intensive component category across the autonomous navigation industry.
The software component is the fastest growing one due to increasingly complex AI-based navigation algorithms that allow these platforms to stand out from each other not only in terms of sensor data collection, but also in terms of real-time path planning and decision-making capabilities. This trend is strengthened by the ongoing development of compound AI system architecture and machine learning-based navigation systems, which make the software become increasingly important for differentiating between platforms in terms of autonomous decision-making capabilities.
By Platform, Automotive Dominates the Autonomous Navigation Market and Marine & Offshore Grows Fastest
The automotive platforms lead in terms of usage, in line with the magnitude of global automobile manufacturing and the place that the automotive industry occupies as an adopter of autonomous navigation technology, from driver assistance systems to more advanced autonomous driving platforms. The automotive industry's significant investment in navigation technology, motivated by consumer safety concerns and government regulations in favor of ADAS systems, helps maintain the dominance of automotive platforms among other autonomous navigation technology platforms.
Marine and offshore platforms are the fastest-growing platform category as sovereign navies fund unmanned patrol craft and shipping lines pursue crew-light cargo operations requiring advanced autonomous navigation capability. This growth is reinforced by national programs including Japan's Nippon Foundation MEGURI2040 initiative, which continues to work toward practical implementation of fully autonomous navigation for coastal shipping, positioning marine and offshore platforms for accelerating adoption as collision-avoidance and automated berthing technology continues to mature.
By Sensor Type, Camera Dominates the Autonomous Navigation Market and LiDAR Grows Fastest
Cameras continue to rule the sensor market because, as mentioned, this particular kind of sensor keeps providing an economical yet deployable option for sensing the environment in ADAS for automobiles and for other autonomous navigation applications as well. The ability of this particular sensor to work with already developed algorithms for computer vision and AI-based image processing, along with its relatively cheaper price compared to LiDAR sensors, ensures the dominance of cameras as the largest category of sensors.
LiDAR is the fastest-growing sensor type as rising demand for precise, three-dimensional environmental mapping capability continues to drive adoption across increasingly autonomous vehicle platforms requiring redundant, high-accuracy perception beyond camera-only systems. This growth is reinforced by continued cost reduction in LiDAR sensor manufacturing, positioning the technology as an increasingly viable complement to camera-based perception systems as autonomous navigation platforms pursue higher levels of autonomy requiring enhanced sensor redundancy and precision.
By Application, Commercial Dominates the Autonomous Navigation Market and Also Grows Fastest
Commercial applications dominate the market as automotive, logistics, and industrial robotics applications continue to represent the largest addressable market for autonomous navigation technology, spanning driver-assistance systems, warehouse automation, and delivery robotics. The scale of commercial vehicle production and rapidly expanding industrial automation adoption continues to sustain commercial applications' position as the largest application category for autonomous navigation technology providers.
Commercial applications are also the fastest-growing application category as increasing deployment of fully autonomous systems, rising adoption of AI-based navigation algorithms, and expansion of smart transportation networks continue to accelerate commercial autonomous navigation investment. This growth is reinforced by growing investments in autonomous ride-hailing and robotaxi services, which continue to extend commercial autonomous navigation demand beyond traditional automotive driver-assistance technology into vertically integrated mobility service operation.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Europe |
Germany |
29.60% |
|
North America |
United States |
84.60% |
|
Asia Pacific |
China |
39.60% |
|
Middle East & Africa |
United Arab Emirates |
30.60% |
|
Latin America |
Brazil |
27.60% |
Europe Autonomous Navigation Market Insights
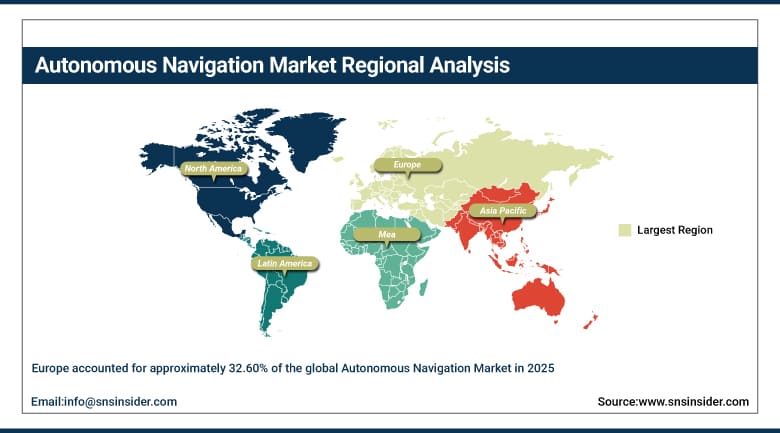
Europe accounted for approximately 32.60% of the global Autonomous Navigation Market in 2025, making it the largest regional market, supported by rising investments by regulatory governments in autonomous navigation technology and the region's established automotive and defense technology industrial base. Germany's large automotive manufacturing sector continues to anchor regional demand, with regional automakers and technology suppliers continuing to invest heavily in advanced driver-assistance and autonomous navigation capability.
Europe has two dominant countries, France and the UK, that offer major regional scale due to their already existing aerospace and defense industry technologies incorporating autonomous navigation technologies. It is predicted that with continued support from the EU regarding regulations for safety and the adoption of autonomous vehicle technology, Europe will maintain its dominant position throughout the forecast period.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Middle East & Africa Autonomous Navigation Market Insights
Middle East & Africa is the fastest-growing regional market growing at a CAGR of 15.7% during forecast period, driven by accelerating government investment in autonomous transportation infrastructure and smart city initiatives across the United Arab Emirates and Saudi Arabia. Autonomous navigation technology continues to be sought after by regional governments as part of economic diversification and infrastructure upgrading policies, expanding the application domain from the typical automotive industry to logistics infrastructure.
United Arab Emirates is expected to sustain regional demand through substantial investment made by the government in autonomous car test drives and implementation programs. Saudi Arabia is expected to provide incremental growth to the region as the nation's development plan focuses on advanced transportation and logistics infrastructure, thus ensuring the Middle East & Africa remains the fastest-growing market.
North America Autonomous Navigation Market Insights
North America represents a significant share of the global Autonomous Navigation Market, anchored by the United States' significant military investments, strong presence of leading technology providers, and expanding integration in commercial and industrial autonomous platforms. The region's concentration of established semiconductor, software, and autonomous vehicle technology companies continues to reinforce sustained market leadership across both commercial and defense applications.
Canada is generating incremental regional demand due to the expansion of its autonomous vehicle testing and development programs. Continued investments made in Canada in the areas of AI-powered navigation algorithms and autonomous ride-hailing services will drive consistent regional growth throughout the forecast period.
Asia Pacific & Latin America Autonomous Navigation Market Insights
The Asia Pacific region is emerging as an increasingly large share of the total market for Autonomous Navigation, based on China’s massive financial commitment to autonomous vehicles technology. In addition, Japan’s Nippon Foundation MEGURI2040 project continues to drive the development of fully autonomous marine navigation, while South Korea adds scale through its automotive and electronic technologies industries.
Latin America's market remains at an earlier stage of development, with Brazil contributing incremental growth as regional automotive manufacturing and technology adoption continue to expand. Regional governments continue to evaluate autonomous navigation technology investment as part of broader transportation infrastructure modernization, though adoption across the region remains considerably earlier-stage relative to more established markets.
Market Dynamics
Growth Drivers: AI and Machine Learning Advancement and Automotive Industry Growth
Development of AI and machine learning represents the primary driver of Autonomous Navigation Market growth, as continued advancement in artificial intelligence continues to enable increasingly sophisticated real-time decision-making capability across autonomous vehicle, drone, robot, and marine vessel platforms. Global positioning system evolution continues to reinforce this trend, as enhanced positioning accuracy and reliability continue to support increasingly demanding autonomous navigation applications requiring precise, real-time location awareness.
Automotive industry growth represents a second major growth driver, as continued automotive industry innovation and rising demand for automation continue to expand autonomous navigation technology adoption across both advanced driver-assistance systems and increasingly autonomous driving platforms. Regulatory support and frameworks continue to reinforce this trend, as governments worldwide increasingly establish policy structures supporting autonomous vehicle testing, deployment, and commercial operation across major automotive markets.
Restraints: Cybersecurity and Data Privacy Concerns
These cybersecurity issues and data protection concerns present a considerable constraint for market growth due to the increasing connectivity of autonomous navigation systems, where more opportunities exist for exploitation by adversaries as the systems incorporate more sophisticated AI capabilities. This security requirement adds ongoing cost and complexity relative to conventional, non-networked navigation systems across both commercial and defense applications.
The technical and regulatory complexity of achieving reliable, safety-validated autonomous operation represents a further restraint, as autonomous navigation systems must demonstrate consistent, fail-safe performance across a vast range of operating conditions before achieving broad regulatory approval and public trust. This validation complexity continues to extend development timelines and increase costs, particularly for fully autonomous applications requiring the highest levels of safety certification.
Opportunities: Robotaxi Service Expansion and Physical AI Integration
Increasing capital flows toward autonomous ride-hailing and robotaxi service businesses offer huge potential because existing autonomous navigation technology firms have been gradually transitioning from technology supply to vertically integrated mobility service provision. Companies that can successfully combine proven autonomous driving capability with fleet operations and rider services are positioned to capture demand as autonomous ride-hailing services continue to scale across major global metropolitan markets.
The continued extension of autonomous navigation technology into general-purpose robotics offers a further avenue for growth, as companies increasingly pursue Physical AI applications extending beyond traditional vehicle navigation into systems designed to understand context and act safely in the physical world more broadly. Companies that can successfully adapt proven autonomy stack technology to general-purpose robotics applications are well positioned to capture demand from an expanding range of industrial and commercial robotics customers.
Recent Developments:
- 2026: L3Harris and Shield AI completed the first flight test of their DiSCO and Hivemind autonomous electronic-warfare ecosystem. The system enabled unmanned aircraft to detect and respond to electromagnetic threats and autonomously reroute follow-on aircraft using real-time threat information.
- 2026: Collins Aerospace demonstrated its Sidekick mission-autonomy software during a successful test flight of the YFQ-42A uncrewed aircraft. The test supported the U.S. Air Force's Collaborative Combat Aircraft program and demonstrated semi-autonomous flight alongside crewed fighter aircraft.
- 2026: Tesla reported a real-world case involving Full Self-Driving (Supervised) navigation, where an authorized user remotely rerouted a Model Y toward a hospital during a medical emergency. The company highlighted the system's ability to execute navigation changes remotely while emphasizing that FSD is not a substitute for emergency services.
Autonomous Navigation Market Key Players are:
- NVIDIA Corporation
- Mobileye Global Inc.
- Tesla, Inc.
- Continental AG
- Robert Bosch GmbH
- Collins Aerospace (RTX Corporation)
- Thales Group
- Rolls-Royce Holdings plc
- Honeywell International Inc.
- ABB Ltd.
- Kongsberg Gruppen ASA
- Trimble Inc.
- Northrop Grumman Corporation
- L3Harris Technologies, Inc.
- Safran S.A.
- General Dynamics Corporation
- BAE Systems plc
- Elbit Systems Ltd.
- Furuno Electric Co., Ltd.
- Qualcomm Technologies, Inc.
Autonomous Navigation Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 7.43 Billion |
| Market Size by 2035 | USD 34.26 Billion |
| CAGR | CAGR of 16.52% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Sensing System, Software, Processing Unit) • By Platform (Automotive, Aerial Drones, Marine & Offshore, Defense, Space, Industrial & Logistics Robots) • By Sensor Type (LiDAR, Radar, Camera, GNSS + INS, Others) • By Application (Commercial (Autonomous Transportation, Logistics & Warehousing, Industrial Automation, Surveying & Mapping, Agriculture, Inspection & Monitoring), Military & Government (Surveillance & Reconnaissance, Defense Navigation, Border & Security, Search & Rescue, Government Surveying & Mapping)) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | NVIDIA Corporation, Mobileye Global Inc., Tesla, Inc., Continental AG, Robert Bosch GmbH, Collins Aerospace (RTX Corporation), Thales Group, Rolls-Royce Holdings plc, Honeywell International Inc., ABB Ltd., Kongsberg Gruppen ASA, Trimble Inc., Northrop Grumman Corporation, L3Harris Technologies, Inc., Safran S.A., General Dynamics Corporation, BAE Systems plc, Elbit Systems Ltd., Furuno Electric Co., Ltd., Qualcomm Technologies, Inc. |

Frequently Asked Questions
Key players include NVIDIA Corporation, Mobileye Global Inc., Tesla, Inc., Continental AG, Robert Bosch GmbH, Collins Aerospace, and Thales Group, among other technology and defense system providers.
Rising investments in autonomous ride-hailing and robotaxi services and continued extension of autonomous navigation technology into general-purpose robotics represent the primary opportunities.
Growth is primarily driven by development of AI and machine learning combined with automotive industry growth and rising demand for automation.
By Platform, Automotive dominated the market with approximately 44.60% share in 2025, reflecting the automotive industry's leading position in commercial autonomous navigation adoption.
Europe dominated the market with approximately 32.60% share in 2025, supported by rising regulatory government investment and the region's established automotive and defense technology base.
