
Inflammatory Bowel Disease Drugs Market Report Scope & Overview:
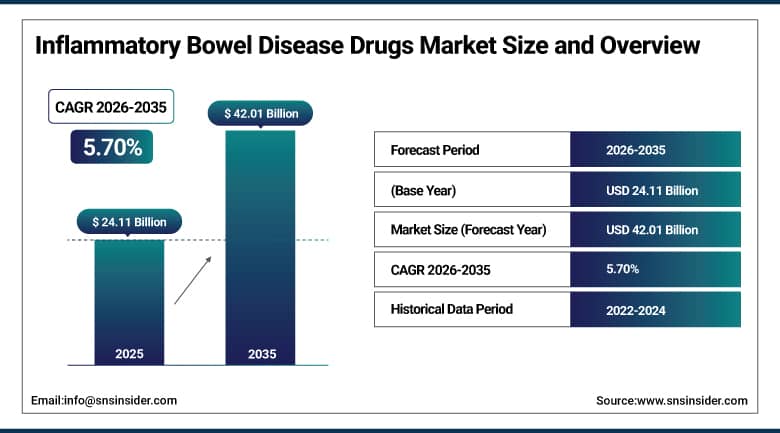
The Inflammatory Bowel Disease Drugs Market was valued at USD 24.11 Billion in 2025 and is expected to reach USD 42.01 Billion by 2035, growing at a CAGR of 5.70% from 2026-2035.
Inflammatory Bowel Disease Drugs Market growth has been significantly boosted owing to the rising number of cases of inflammatory bowel disease across the globe, advancements in immunology-based medications, and enhanced disease surveillance resulting in continued growth of long-term patient retention on treatments. Inflammatory bowel disease consists of two major diseases which are ulcerative colitis and Crohn’s disease causing inflammation within the body’s digestive tract especially the intestines. Common signs of inflammatory bowel diseases include abdominal pain, diarrhea, loss of appetite, bloating, and blood in stool. Inflammatory bowel disease involves the administration of anti-inflammatory drugs and this can be achieved through the use of anti-inflammatory drugs, biologics, small molecules, corticosteroids, and JAK inhibitors among others. Owing to growing research and drug approvals, the market will continue experiencing growth in efforts aimed at enhancing the welfare of patients and a large percentage of IBD patients failing to respond to initial therapy remains a major driver for market growth.
On September 11, 2024, Johnson & Johnson announced that the U.S. Food and Drug Administration approved TREMFYA (guselkumab) for the treatment of moderate to severe active ulcerative colitis in adult patients, making it the first and only dual-acting inhibitor targeting interleukin-23 approved for this indication and solidifying the company's leadership position in inflammatory bowel disease. Guselkumab selectively binds to the p19 subunit of IL-23 while also interacting with the CD64 receptor on IL-23-producing cells, representing a novel dual mechanism of action, reflecting the broader industry trend of established immunology drug developers continuing to introduce increasingly differentiated biologic mechanisms as the IBD treatment landscape becomes progressively more crowded and mechanistically sophisticated.
To Get More Information On Inflammatory Bowel Disease Drugs Market - Request Free Sample Report
Inflammatory Bowel Disease Drugs Market Trends
-
Rising adoption of IL-23 inhibitors offering novel dual-acting mechanisms distinct from established TNF inhibitor therapies.
-
Growing development of subcutaneous self-administration formulations reducing reliance on infusion center visits.
-
Expanding use of JAK inhibitors providing oral treatment alternatives to traditional injectable biologic therapies.
-
Increasing adoption of biosimilar TNF inhibitors expanding affordable treatment access across global markets.
-
Rising use of online pharmacy distribution channels supported by telemedicine and self-administered prefilled delivery devices.
-
Growing emphasis on personalized medicine strategies enhancing targeted treatment selection for individual patients.
U.S. Inflammatory Bowel Disease Drugs Market Outlook
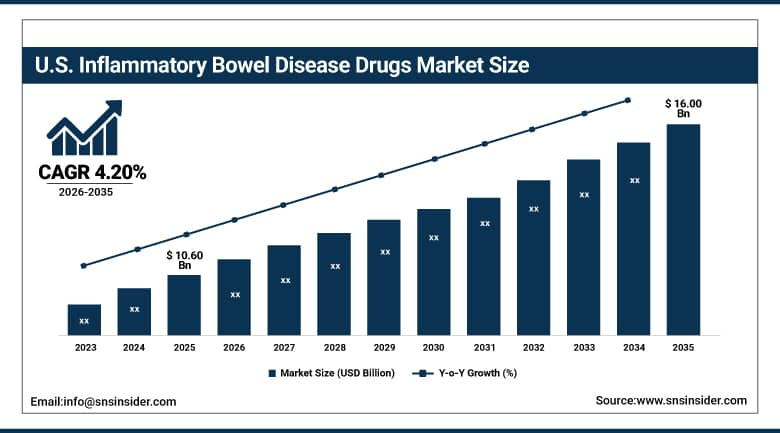
The U.S. Inflammatory Bowel Disease Drugs Market was valued at USD 10.60 Billion in 2025 and is expected to reach USD 16.00 Billion by 2035, growing at a CAGR of 4.20% from 2026-2035.
The U.S. Inflammatory Bowel Disease Drugs Market growth is being sustained by the increasing adoption of advanced therapies, such as biologics, JAK inhibitors, and individualized approaches for treating Crohn's disease and ulcerative colitis. Gastroenterologists in the United States currently have more than 14 advanced therapies available for patients diagnosed with ulcerative colitis and Crohn's disease due to the expanded range of treatment options that has been achieved within the past few years. However, despite the wide array of treatment options, there are still many patients who fail to enter into remission, or even if they do, they eventually lose their efficacy, thus making new drugs of great significance for the United States market.
On June 18, 2024, the FDA approved AbbVie's SKYRIZI (risankizumab) for the treatment of adult patients with moderately to severely active ulcerative colitis, expanding the drug's accessibility to approximately 1 million patients in the United States and making SKYRIZI the first IL-23 inhibitor approved for both ulcerative colitis and Crohn's disease. Following a 12-week induction period, patients can self-administer this medication at home using an on-body injector device, illustrating how established domestic biologic manufacturers continue to expand both indication breadth and self-administration convenience as competitive differentiators within the country's increasingly crowded inflammatory bowel disease treatment landscape.
Inflammatory Bowel Disease Drugs Market Segment Analysis
-
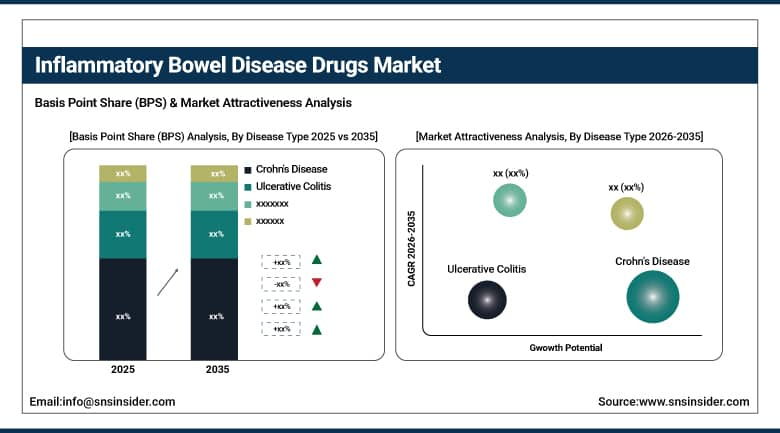
By Disease Type, the Crohn's Disease segment dominated the Inflammatory Bowel Disease Drugs Market with approximately 57.60% share in 2025, while the Ulcerative Colitis segment is the fastest growing with a CAGR of approximately 5.60%.
-
By Drug Class, the TNF Inhibitors segment dominated the Inflammatory Bowel Disease Drugs Market with approximately 35.60% share in 2025, while the JAK Inhibitors segment is the fastest growing with a CAGR of approximately 7.80%.
-
By Route of Administration, the Injectable segment dominated the Inflammatory Bowel Disease Drugs Market with approximately 58.60% share in 2025, while the Oral segment is the fastest growing with a CAGR of approximately 6.20%.
-
By Distribution Channel, the Hospital Pharmacy segment dominated the Inflammatory Bowel Disease Drugs Market with approximately 35.60% share in 2025, while the Online Pharmacy segment is the fastest growing with a CAGR of approximately 7.40%.
By Disease Type, Crohn's Disease Dominates the Inflammatory Bowel Disease Drugs Market and Ulcerative Colitis Grows Fastest
Crohn's disease dominates the market, reflecting its typically more complex clinical presentation and higher likelihood of requiring escalation to advanced biologic and targeted therapies relative to ulcerative colitis, given the condition's tendency to affect multiple segments of the digestive tract with transmural inflammation. The condition's greater propensity for complications, including strictures and fistulas requiring aggressive pharmacological intervention, continues to sustain Crohn's disease's position as the largest disease type category in terms of overall drug spending, as patients frequently require higher-cost combination biologic regimens to achieve and maintain remission.
Ulcerative colitis is the fastest-growing disease type as increasing urban diet-related gut inflammation patterns among young adults, rising adoption of early biologic therapy leading to longer maintenance treatment cycles, and improved diagnosis through widespread colonoscopy screening in tertiary hospitals continue to expand the diagnosed and treated patient population. This growth is reinforced by the expansion of advanced immunology drugs and better disease monitoring, which continue to increase long-term patient retention on therapy, supporting steady segment growth as newly approved biologics extend treatment options specifically for ulcerative colitis patients.
By Drug Class, TNF Inhibitors Dominates the Inflammatory Bowel Disease Drugs Market and JAK Inhibitors Grows Fastest
TNF inhibitors dominate due to their established efficacy in treating moderate-to-severe diseases, as well as physicians' familiarity with these drugs, as these medicines are extensively used in hospitals' gastroenterology departments. In addition, the extensive history of safety and effectiveness compared to the new drugs classes guarantees the prolonged usage of TNF inhibitors, which continues to keep these drugs in the lead despite the emergence of other drug types with new mechanisms of action. This established drug class, which is still gaining popularity, is considered as a preferred first-line biologic in many pathways due to its efficacy and safety profile.
JAK inhibitors represent the fastest growing drug class since these oral therapies offer a convenient alternative to conventional injectable biologic drugs, providing patients with pills instead of injections or infusions. This trend is supported by the increasing number of approvals for the use of JAK inhibitors in treating ulcerative colitis and Crohn's disease, as this class of medicines is considered as a promising option for those patients who failed TNF blockers' therapy.
By Route of Administration, Injectable Dominates the Inflammatory Bowel Disease Drugs Market and Oral Grows Fastest
Injectable administration dominates the market as the majority of biologic therapies, including TNF inhibitors and newer IL-23 inhibitors, require subcutaneous injection or intravenous infusion administration given the large protein-based molecular structure of these drug classes. High hospitalization rates due to the increasing severity of IBD, combined with widespread adoption of injectable drugs across both hospital and self-administered settings, continue to sustain injectable administration's position as the largest route of administration category for inflammatory bowel disease drugs.
Oral administration is the fastest-growing route of administration as the approval of oral medications, including JAK inhibitors and other small-molecule therapies, continues to encourage more patients to seek treatment options that avoid injection-related discomfort and administration complexity. This growth is reinforced by the availability of self-administered prefilled syringes and pens alongside expanding oral medication approvals, which together continue to improve treatment accessibility and patient adherence across the broader inflammatory bowel disease patient population.
By Distribution Channel, Hospital Pharmacy Dominates the Inflammatory Bowel Disease Drugs Market and Online Pharmacy Grows Fastest
Hospital pharmacies dominate the market as complex biologic therapies requiring intravenous infusion administration, along with newly diagnosed and severe disease cases requiring specialist management, continue to be dispensed primarily through hospital-based pharmacy and infusion center settings. The scale of hospital-based gastroenterology care, combined with hospitals' established relationships with specialty pharmacy distribution networks for high-cost biologic therapies, continues to sustain hospital pharmacies' position as the largest distribution channel category.
Online pharmacies are the fastest-growing distribution channel as increasing prevalence of online pharmacies, greater internet accessibility, and the availability of various discounts continue to drive channel migration for maintenance-phase inflammatory bowel disease drug dispensing. The rise of telemedicine, combined with the availability of self-administered prefilled syringes and pens for IBD and the approval of oral medications, continues to encourage more patients to turn to online pharmacies, positioning this distribution channel for continued above-market growth as digital healthcare delivery infrastructure continues to mature.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
84.60% |
|
Europe |
Germany |
29.60% |
|
Asia Pacific |
China |
39.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
North America Inflammatory Bowel Disease Drugs Market Insights
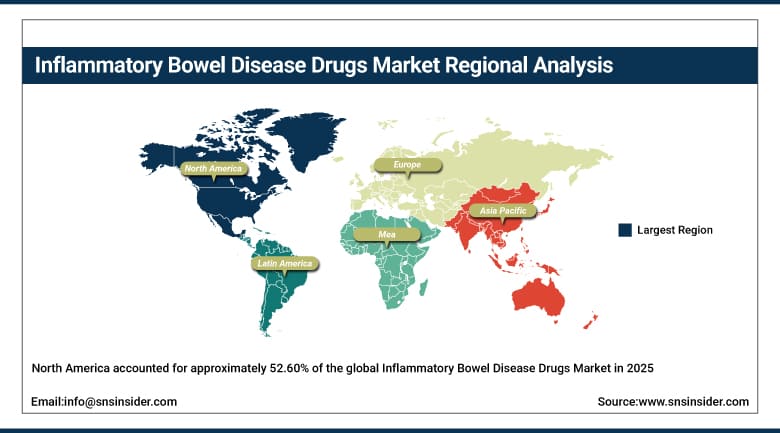
North America accounted for approximately 52.60% of the global Inflammatory Bowel Disease Drugs Market in 2025, making it the largest regional market, supported by high inflammatory bowel disease prevalence, well-established healthcare infrastructure, and broad reimbursement coverage for advanced biologic therapies. The United States dominates regional demand, anchored by a concentrated base of established immunology drug manufacturers and gastroenterology specialist networks providing access to more than 14 advanced therapy options for patients.
Canada is contributing incremental regional demand as its healthcare system continues to expand access to advanced biologic therapies. Continued domestic investment in novel drug mechanisms and expanding self-administration formulation availability is expected to sustain North America's leading position through the forecast period, even as growth in percentage terms moderates relative to faster-expanding emerging markets.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Inflammatory Bowel Disease Drugs Market Insights
Europe represents a significant share of the global Inflammatory Bowel Disease Drugs Market, anchored by Germany's large healthcare infrastructure and established gastroenterology specialist networks. European healthcare systems continue to support broad access to advanced biologic and small-molecule therapies given the region's well-developed public healthcare reimbursement frameworks covering inflammatory bowel disease treatment.
The United Kingdom, France, and Italy are contributing steady demand growth as regional healthcare systems continue to extend advanced therapy adoption across an expanding diagnosed patient population. Regional drug manufacturers continue to invest in biosimilar development to expand affordable treatment access as the region's substantial patent-expired TNF inhibitor portfolio continues to face biosimilar competition.
Asia Pacific Inflammatory Bowel Disease Drugs Market Insights
The Asia Pacific region is currently witnessing the fastest growth rate in terms of market expansion at a CAGR of about 6.60% between 2026 and 2035, attributable to the increasing diagnosis rates of inflammatory bowel diseases along with the development of healthcare infrastructure in China, Japan, and India. In particular, the growing number of diagnoses of inflammatory bowel diseases coupled with the large population size of China continues to drive demand in the Asia Pacific region.
India is driving the growth with the development of healthcare infrastructure and an increase in the number of gastroenterology specialists. The healthcare infrastructure, along with the biologic therapy adoption, in Japan and South Korea is also aiding Asia Pacific's position as the fastest growing region.
MEA & Latin America Inflammatory Bowel Disease Drugs Market Insights
The Middle East & Africa market remains comparatively small but is expanding as growing healthcare infrastructure investment across the United Arab Emirates and Saudi Arabia sustains demand for advanced inflammatory bowel disease therapies. Regional governments continue to invest in expanding gastroenterology specialist capacity to serve growing domestic demand for inflammatory bowel disease diagnosis and treatment.
Latin America's market is led by Brazil, where a growing diagnosed patient population and expanding healthcare infrastructure continue to drive gradual inflammatory bowel disease drugs market growth. Mexico is contributing growth as regional healthcare access continues to expand. Across the region, adoption remains concentrated among larger urban medical centers with established gastroenterology programs.
Market Dynamics
Growth Drivers: Rising IBD Prevalence and Advanced Biologic Innovation
The increasing global prevalence of inflammatory bowel disease represents the primary driver of Inflammatory Bowel Disease Drugs Market growth, as rising diagnosis rates continue to expand the treated patient population requiring pharmacological intervention. Increasing awareness of disease symptoms and improved diagnostic capabilities, enabling earlier detection and intervention, continue to reinforce sustained demand growth as more patients are identified and initiated on treatment earlier in their disease course.
Expansion of advanced immunology drugs represents a second major growth driver, as continued introduction of novel biologic mechanisms and small-molecule therapies continues to provide new treatment options for patients who do not respond adequately to first-line therapies. A significant proportion of IBD patients experience disease relapse or inadequate response, necessitating escalation to more effective biologics and targeted therapies, reinforcing sustained demand for an expanding pipeline of increasingly differentiated treatment mechanisms across the broader immunology drug development landscape.
Restraints: High Treatment Costs and Immunogenic Response Risk
High prices of treatment form another major constraint to growth since the more developed biological drugs continue to cost relatively much in terms of the per capita cost per year of treatment, something that is particularly challenging within price-sensitive emerging economies with less developed healthcare coverage systems. It is this issue that has continued to impede greater uptake of biologic drug treatment, especially in areas where the insurance coverage of immunology drugs is limited compared to established markets.
Immunogenic reaction is yet another constraint to growth because patients can start to build up resistance to the biologic drugs, making the treatment less effective, and requiring an increase in dosage or changing the mode of treatment altogether. This particular problem has continued to promote interest in combination treatments utilizing biologic and immunomodulatory drugs, which help avoid immunogenic reactions and provide better management of diseases, although at higher costs than single treatment methods.
Opportunities: Biosimilar Expansion and Personalized Medicine Development
Expansion of the biosimilar market represents a substantial opportunity, as affordable treatment options for patent-expired biologic therapies continue to become available globally, expanding treatment access for patients in markets with more limited healthcare budgets. Manufacturers that can develop cost-competitive, regulatory-approved biosimilar TNF inhibitors are positioned to capture demand from healthcare systems increasingly prioritizing cost-effective access to proven biologic therapy mechanisms.
Advances in personalized medicine that enhance targeted treatment strategies for patients offer a further avenue for growth, as improved biomarker identification and disease subtyping continue to enable more precise matching of patients to the therapeutic mechanisms most likely to achieve remission. Manufacturers that can develop companion diagnostic capability alongside novel biologic therapies are well positioned to capture demand from physicians and patients increasingly seeking evidence-based, individualized treatment selection strategies.
Recent Developments:
-
In March 2025, Johnson & Johnson's TREMFYA (guselkumab) received FDA approval, including both subcutaneous and intravenous induction options, for the treatment of adults with moderately to severely active Crohn's disease.
-
AbbVie received an FDA label update for RINVOQ (upadacitinib), expanding its use for adults with moderately to severely active ulcerative colitis and Crohn's disease after at least one approved systemic therapy when TNF blockers are deemed clinically unsuitable.
-
In July 2025, Abivax SA reported favorable topline results from its Phase 3 induction trials, ABTECT-1 and ABTECT-2, assessing obefazimod in adult patients with moderate to severe ulcerative colitis.
Inflammatory Bowel Disease Drugs Market Key Players
-
AbbVie Inc.
-
Johnson & Johnson (Janssen Pharmaceuticals)
-
Takeda Pharmaceutical Company Limited
-
Pfizer Inc.
-
Bristol-Myers Squibb Company
-
Eli Lilly and Company
-
F. Hoffmann-La Roche Ltd
-
Merck & Co., Inc.
-
Sanofi S.A.
-
Celltrion, Inc.
-
Amgen Inc.
-
Boehringer Ingelheim GmbH
-
Ferring Pharmaceuticals
-
Galapagos NV
-
Gilead Sciences, Inc.
-
Alfasigma S.p.A.
-
Dr. Falk Pharma GmbH
-
Bausch Health Companies Inc.
-
Abivax SA
-
Arena Pharmaceuticals, Inc. (Pfizer)
Inflammatory Bowel Disease Drugs Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 24.11 Billion |
| Market Size by 2035 | USD 42.01 Billion |
| CAGR | CAGR of 14.77% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Disease Type (Crohn's Disease, Ulcerative Colitis) • By Drug Class (TNF Inhibitors, Aminosalicylates, Corticosteroids, Immunomodulators, JAK Inhibitors, Others) • By Route of Administration (Injectable, Oral) • By Distribution Channel (Hospital Pharmacy, Retail Pharmacy, Online Pharmacy) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | AbbVie Inc., Johnson & Johnson (Janssen Pharmaceuticals), Takeda Pharmaceutical Company Limited, Pfizer Inc., Bristol-Myers Squibb Company, Eli Lilly and Company, F. Hoffmann-La Roche Ltd, Merck & Co., Inc., Sanofi S.A., Celltrion, Inc., Amgen Inc., Boehringer Ingelheim GmbH, Ferring Pharmaceuticals, Galapagos NV, Gilead Sciences, Inc., Alfasigma S.p.A., Dr. Falk Pharma GmbH, Bausch Health Companies Inc., Abivax SA, Arena Pharmaceuticals, Inc. (Pfizer) |
Frequently Asked Questions
Key players include AbbVie Inc., Johnson & Johnson, Takeda Pharmaceutical Company Limited, Pfizer Inc., Bristol-Myers Squibb Company, Eli Lilly and Company, and F. Hoffmann-La Roche Ltd, among other global immunology drug developers.
Expansion of the biosimilar market and advances in personalized medicine that enhance targeted treatment strategies represent the primary opportunities.
Growth is primarily driven by the increasing global prevalence of inflammatory bowel disease combined with expansion of advanced immunology drugs and improved disease monitoring.
By Drug Class, TNF Inhibitors dominated the market with approximately 35.60% share in 2025, reflecting strong, long-established clinical efficacy and high physician familiarity.
North America dominated the market with approximately 52.60% share in 2025, supported by high disease prevalence, well-established healthcare infrastructure, and broad biologic therapy reimbursement coverage.
