
Kidney Transplant Market Report Scope & Overview:
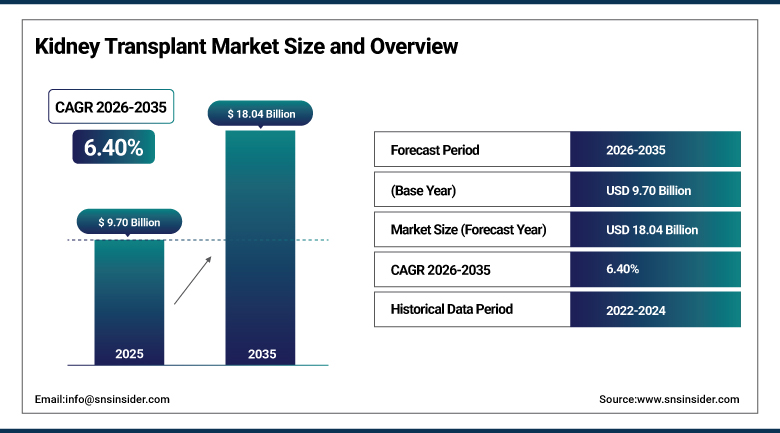
The Kidney Transplant Market was valued at USD 9.70 Billion in 2025 and is expected to reach USD 18.04 Billion by 2035, growing at a CAGR of 6.40% from 2026-2035.
The Kidney Transplant Market covers the surgical procedures, immunosuppressive drugs, organ preservation solutions and devices, and tissue-typing and monitoring services used to replace failed kidneys in patients with end-stage renal disease. Transplantation offers better survival and quality of life than long-term dialysis, and demand is rising as diabetes, hypertension and aging increase the number of patients with kidney failure. Growth is supported by expanding donor programs, improved organ preservation, better anti-rejection regimens and early research into xenotransplantation, although organ shortages and lifelong drug costs remain constraints.
⮞In November 2025, United Therapeutics announced the first transplant of its UKidney in the EXPAND trial at NYU Langone Health. The pig kidney carries 10 gene edits, and the trial plans six initial transplants at two centers in patients aged 55–70 with end-stage renal disease on dialysis, pointing to a possible new source of organs.
To Get more information Kidney Transplant Market - Request Free Sample Report
Kidney Transplant Market Trends
- Rising adoption of machine perfusion to expand the usable donor pool
- Clinical progress in gene-edited xenotransplantation as a potential long-term organ source
- Growth in living donor programs and paired kidney exchange
- Shift toward extended-release tacrolimus and mTOR-based regimens to improve adherence and reduce toxicity
- Use of donor-derived cell-free DNA and other biomarkers for rejection monitoring
- Government policy reforms to increase transplant access and reduce organ discard
U.S. Kidney Transplant Market Outlook
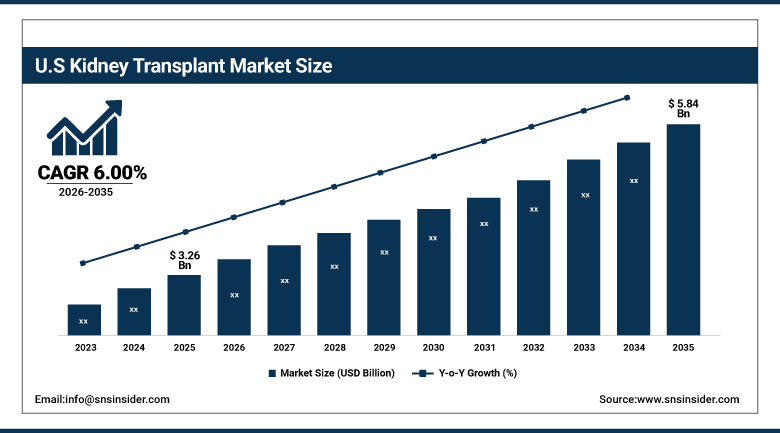
The U.S. Kidney Transplant Market was valued at USD 3.26 Billion in 2025 and is expected to reach USD 5.84 Billion by 2035, growing at a CAGR of 6.00% from 2026-2035.
The U.S. Kidney Transplant Market is supported by the largest transplant volume in the world, an established organ procurement network, broad insurance coverage for transplantation and immunosuppressants, and a strong base of device, drug and diagnostics companies. Rising rates of diabetes and hypertension increase the waiting list, and policy initiatives aim to raise procurement and reduce the number of discarded organs. Growth is moderated by persistent organ scarcity and the cost of lifelong therapy.
⮞In December 2024, the Centers for Medicare & Medicaid Services announced the Increasing Organ Transplant Access (IOTA) Model, which will assess whether payment incentives can raise transplant rates among dialysis patients. The model reflects growing attention to the number of patients who never reach the waiting list.
Kidney Transplant Market Segment Analysis
- By Donor Type, living donor segment dominated the Kidney Transplant Market in 2025 with an estimated 53.00% share; deceased donor segment is the fastest-growing segment, with an estimated CAGR of 7.00% during 2026–2035.
- By Type of Transplant, non-preemptive segment dominated the Kidney Transplant Market in 2025 with an estimated 67.50% share; preemptive segment is the fastest-growing segment, with an estimated CAGR of 8.20% during 2026–2035.
- By End User, hospitals segment dominated the Kidney Transplant Market in 2025 with an estimated 58.00% share; transplant clinics segment is the fastest-growing segment, with an estimated CAGR of 8.40% during 2026–2035.
- By Immunosuppressive Drug Class, calcineurin inhibitors segment dominated the Kidney Transplant Market in 2025 with an estimated 40.00% share; mTOR inhibitors segment is the fastest-growing segment, with an estimated CAGR of 7.60% during 2026–2035.
- By Organ Preservation Method, static cold storage segment dominated the Kidney Transplant Market in 2025 with 44.30% share; normothermic machine perfusion segment is the fastest-growing segment, with an estimated CAGR of 12.00% during 2026–2035.
By Donor Type, Living Donor Dominates Kidney Transplant Market; Deceased Donor to Register Fastest Growth.
Living donor transplants account for the largest share of the Kidney Transplant Market in our assessment, because living kidneys are planned, can be transplanted soon after removal and generally show longer graft survival than organs from deceased donors. Family members, friends and altruistic donors supply a growing number of kidneys, and paired exchange programs allow incompatible pairs to find matches. Published sources differ on which donor type is larger, so this report weights toward countries with high living donation rates, including large parts of Asia.
Deceased donor transplantation is projected to register faster growth as organ procurement systems strengthen and as preservation technologies allow kidneys that were once discarded to be used. Donation after circulatory death is expanding in many countries, and machine perfusion can improve the quality of marginal organs. In North America and Europe, deceased donors already provide most kidneys, so policy changes that raise consent rates and reduce discard have a direct effect on transplant volumes and related spending. Policy support for donation is therefore central.
By Type of Transplant, Non-Preemptive Dominates Kidney Transplant Market; Preemptive to Register Fastest Growth.
Non-preemptive transplants dominate the Kidney Transplant Market because most patients begin dialysis before a suitable donor kidney is found. Long waiting times for deceased donor organs, late referral to transplant centers and delays in work-up mean that many recipients spend months or years on dialysis. These patients require ongoing dialysis care until surgery, and their transplants are often more complex because of accumulated complications, which raises the use of tissue-typing, perioperative care and immunosuppression services. Earlier referral would reduce this burden.
Preemptive transplantation, performed before dialysis is needed, is projected to grow faster as nephrologists refer patients earlier and as living donor programs expand. Evidence shows better graft and patient survival with preemptive transplantation and lower overall cost, which attracts payers and policymakers. Initiatives that encourage early evaluation of patients with advanced chronic kidney disease, and education of potential living donors, are expected to raise the preemptive share gradually over the forecast period. Dialysis providers and transplant centers are also collaborating on education programs.
By End User, Hospitals Dominate Kidney Transplant Market; Transplant Clinics to Register Fastest Growth.
Hospitals dominate the Kidney Transplant Market because transplant surgery requires operating rooms, intensive care, donor coordination, tissue-typing laboratories and multidisciplinary teams that are concentrated in large academic and tertiary centers. Most procedures, organ preservation activity and early post-operative care take place in hospitals, which also purchase the preservation solutions, perfusion devices and immunosuppressive drugs used in the process. Public and teaching hospitals carry a large share of volume in many countries. Group purchasing and long-standing relationships with suppliers reinforce their position.
Transplant clinics are projected to register the fastest growth as follow-up care, evaluation of candidates and long-term monitoring move to specialized outpatient settings. Clinics manage immunosuppressant dosing, rejection surveillance and infection prevention, and they are increasingly adopting biomarker testing and telehealth to monitor recipients between visits. As survival improves and more patients live for decades with functioning grafts, outpatient management becomes a larger source of recurring spending. Telehealth platforms and home laboratory sampling further reduce the need for travel to major centers for routine checks.
By Immunosuppressive Drug Class, Calcineurin Inhibitors Dominate Kidney Transplant Market; mTOR Inhibitors to Register Fastest Growth.
Calcineurin inhibitors, including tacrolimus and cyclosporine, dominate the Kidney Transplant Market because they form the backbone of maintenance immunosuppression and are used in most recipients. Generic availability keeps prices low, while extended-release tacrolimus formulations support adherence by allowing once-daily dosing. Clinicians continue to rely on these agents because of their proven effectiveness in preventing acute rejection, although nephrotoxicity and metabolic side effects encourage efforts to minimize exposure over time. Regulatory approval of generics has widened access in emerging markets, and tacrolimus remains the most prescribed agent after transplantation.
mTOR inhibitors such as everolimus and sirolimus are projected to grow fastest as clinicians seek regimens that allow lower calcineurin inhibitor doses and may reduce cancer and viral risks. Antiproliferative agents and corticosteroids remain part of standard combinations, and newer biologics and costimulation blockers are being used in selected patients. Antiviral prevention drugs for cytomegalovirus also add to spending on post-transplant care. Switching between agents is guided by therapeutic drug monitoring and by individual risk of rejection and infection, so growth in monitoring services accompanies changes in drug mix, and generics of mTOR agents are expected to improve affordability.
By Organ Preservation Method, Static Cold Storage Dominates Kidney Transplant Market; Normothermic Machine Perfusion to Register Fastest Growth.
Static cold storage dominates the Kidney Transplant Market because it is simple, inexpensive and widely accepted. Organs are flushed with preservation solutions and kept on ice during transport, an approach used by almost every transplant program. Established solutions from suppliers such as Bridge to Life and Dr. Franz Köhler Chemie remain standard, and logistics networks are built around this method, which makes it the default choice for most procurement teams. Organ procurement organizations and transport providers also prefer this approach because it requires no specialized equipment.
Normothermic machine perfusion is projected to register the fastest growth because it keeps organs functioning at body temperature, allows assessment of viability and may increase use of marginal kidneys. Hypothermic machine perfusion is already used to lower delayed graft function in higher-risk organs. The high cost of devices and disposables limits adoption today, but acquisitions and clinical results are expanding availability, and larger transplant centers are building perfusion capability into routine practice. Clinical trials and registry data continue to inform when perfusion improves outcomes.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
80.00 |
|
Europe |
Germany |
24.00 |
|
Asia Pacific |
China |
38.00 |
|
Latin America |
Brazil |
45.00 |
|
Middle East & Africa |
Saudi Arabia |
28.00 |
North America Kidney Transplant Market Insights
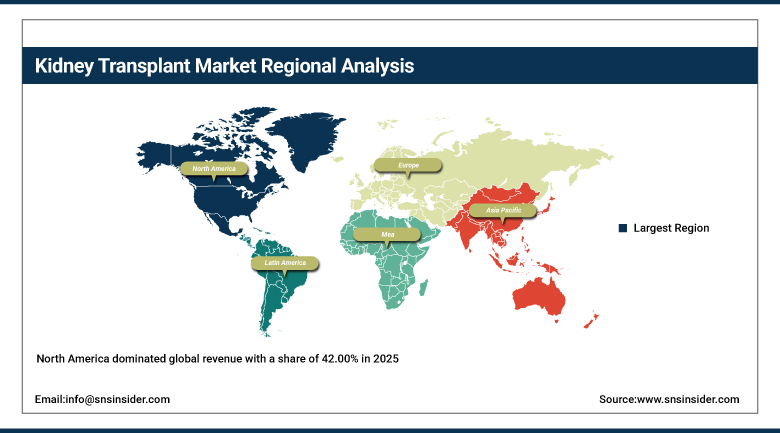
North America dominated global revenue with a share of 42.00% in 2025, supported by the largest transplant volumes in the world, wide insurance coverage, advanced transplant centers and the presence of leading companies such as Bristol-Myers Squibb, Pfizer, Thermo Fisher Scientific, CareDx, Paragonix, TransMedics and United Therapeutics. The United States accounts for about 80.00% of regional demand, with Canada contributing through provincial programs. Canada contributes through coordinated provincial donation networks and strong academic centers.
Policy initiatives such as the CMS IOTA Model, announced in December 2024, aim to increase access and procurement. In September 2024, eGenesis raised USD 191 Million in Series D financing to advance its gene-edited kidney, EGEN-2784. Although growth is moderated by the size of the existing base and organ scarcity, innovation in xenotransplantation, perfusion and monitoring continues to support spending over the forecast period. Regional focus on reducing organ discard has encouraged centers to adopt perfusion and improved logistics, while biomarker testing for rejection is being added to routine follow-up for recipients across many large programs.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Kidney Transplant Market Insights
Europe is also a major region, growing progressively during 2026-2035. Germany, Spain, France, Italy and the United Kingdom lead activity, and Spain is widely recognized for its organ donation system. Strong public health coverage supports access, and the region hosts major suppliers including Novartis, Astellas, Sanofi, Roche, Teva, XVIVO Perfusion and Dr. Franz Köhler Chemie. Eurotransplant and similar organizations coordinate allocation across borders, which improves matching for patients who are difficult to match, and academic transplant centers in the region contribute significantly to clinical research and trials.
Opt-out donation laws, national allocation systems and cross-border organ exchange organizations help raise donation rates, while donation after circulatory death is expanding. Ageing populations and the cost of long-term care for dialysis patients encourage health systems to prioritize transplantation. Price controls on drugs and budget limits on hospitals moderate growth, but efficient donation networks and adoption of perfusion technology provide steady momentum. Aging recipients and donors are also raising demand for specialized care, and growth in living donation programs in countries such as the Netherlands and the United Kingdom supports a gradual rise in volumes.
Asia Pacific Kidney Transplant Market Insights
Asia Pacific is projected to be the fastest-growing region, advancing at a CAGR of 8.20% from 2026-2035. China, India, Japan, South Korea and Australia lead regional activity, and living donation is common in many countries. Rising prevalence of diabetes and hypertension is increasing the population with kidney failure, while growing hospital capacity and insurance coverage expand access to transplantation. Rapid growth in the number of dialysis patients, particularly in China and India, creates strong pressure to expand transplantation as the more cost-effective option over the long term.
Governments are building organ donation frameworks and training transplant teams, and local manufacturers are strengthening supply of generic immunosuppressants. In March 2025, Zydus launched ANVIMO (letermovir) in India for prevention of cytomegalovirus infection in transplant patients, showing how regional drug makers are adding post-transplant care products. Cultural attitudes toward deceased donation and uneven access to specialist centers remain challenges that investment is gradually addressing. International manufacturers are partnering with hospitals to introduce perfusion and monitoring technology, which is gradually improving outcomes in higher-risk patients.
MEA & Latin America Kidney Transplant Market Insights
In Latin America, Brazil operates one of the largest public transplant systems in the world, followed by Mexico, Argentina and Colombia. Public financing of transplants and immunosuppressants supports access, and regional growth is expected to be 6.80% annually. Waiting lists remain long, and expansion of donor coordination and hospital capacity is a priority for health authorities across the region. Chile and Uruguay also report high donation rates relative to their population size, reflecting strong coordination. Mexico also operates large public transplant programs.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Turkey and South Africa lead activity through investment in transplant centers and national donation programs. Regional demand is expected to grow at 7.00% annually. Limited specialist capacity, high costs and low donation rates restrict access in much of Africa, while Gulf countries are building programs and training clinicians to serve their growing patient populations. Egypt has a large living donor transplant program, and several countries are working with international partners to train surgeons and nephrologists, which should expand the number of qualified programs in the coming years.
Market Dynamics
Growth Drivers: Rising Kidney Failure, Better Outcomes and Technology Advances
The growing number of patients with end-stage renal disease is the main driver of the Kidney Transplant Market. Diabetes, hypertension, obesity and aging populations are raising the incidence of chronic kidney disease worldwide, and transplantation is the preferred treatment because it improves survival and quality of life compared with long-term dialysis. Health systems also recognize that a successful transplant costs less over time than years of dialysis, which supports investment.
Advances in surgical technique, organ preservation, tissue matching and immunosuppression continue to improve graft survival and widen eligibility for older and higher-risk patients. Machine perfusion increases the use of organs that would once have been discarded, while biomarkers support earlier detection of rejection. Government campaigns to raise donor registration and programs that support living donors further expand the supply of organs. Better access to dialysis in emerging markets also uncovers more patients who can be referred for transplant evaluation, which increases demand for tissue-typing, surgical and follow-up services in the long term.
Restraints: Organ Shortage, Cost and Long-Term Complications
The shortage of donor organs is the most significant restraint, because waiting lists far exceed available kidneys in nearly every country. Deaths on the waiting list and organ discard limit realized volumes, and cultural, legal and logistical barriers hold back donation rates. Transplant centers also face capacity limits in operating rooms, staff and follow-up clinics.
The cost of surgery and lifelong immunosuppression is high, and lack of insurance or reimbursement restricts access in many emerging markets. Recipients face risks of rejection, infection, cancer and cardiovascular disease, and non-adherence to medication can cause graft loss. Generic competition also lowers average drug prices, which moderates spending on established immunosuppressants. Pricing pressure from payers adds to the challenge for manufacturers of preservation devices and diagnostic tests, particularly where reimbursement for new technologies is slow to be established.
Opportunities: Xenotransplantation, Perfusion and Emerging Markets
Xenotransplantation could ultimately remove the organ shortage if clinical trials confirm safety and durability. United Therapeutics has started its EXPAND trial of a gene-edited pig kidney, and eGenesis is advancing its own program, which would create entirely new product and service categories if successful. Even partial success would raise interest in donor screening, immunosuppression regimens and specialized monitoring.
Machine perfusion, biomarker testing and digital follow-up tools offer high-value opportunities for device and diagnostics companies, while growth in transplant capacity in Asia Pacific, Latin America and the Middle East expands the addressable base. Companies that combine devices with services, such as organ logistics and monitoring, can build recurring revenue and stronger relationships with transplant centers. Cell-free DNA tests and artificial intelligence tools for risk prediction can help clinicians individualize immunosuppression, creating opportunities for diagnostic companies to expand their role.
Recent Developments:
- In October 2025, Terumo completed its acquisition of OrganOx, a maker of normothermic machine perfusion systems, for nearly USD 1.5 Billion. The deal expands Terumo's presence in organ preservation technology for transplant centers.
- In March 2025, Zydus launched ANVIMO (letermovir) in India for prevention of cytomegalovirus infection in transplant patients. The launch broadens access to post-transplant antiviral care in the Asia Pacific region.
- In September 2024, eGenesis raised USD 191 Million in Series D financing to advance EGEN-2784, a gene-edited kidney for transplantation. The funding supports clinical development of its xenotransplantation program.
Kidney Transplant Market Key Players are:
- Novartis AG
- Astellas Pharma Inc.
- Sanofi
- Pfizer Inc.
- F. Hoffmann-La Roche Ltd
- Veloxis Pharmaceuticals
- Bristol-Myers Squibb Company
- Thermo Fisher Scientific Inc.
- BioLife Solutions, Inc.
- TransMedics Group, Inc.
- Terumo Corporation (OrganOx)
- XVIVO Perfusion AB
- Dr. Franz Köhler Chemie GmbH
- Teva Pharmaceutical Industries Ltd.
- Bio-Rad Laboratories, Inc.
- Immucor, Inc.
- Paragonix Technologies
- Organ Recovery Systems
- Bridge to Life Ltd.
- CareDx, Inc.
Kidney Transplant Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 9.70 Billion |
| Market Size by 2035 | USD 18.04 Billion |
| CAGR | CAGR of 6.40% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Donor Type (Living Donor and Deceased Donor) • By Type of Transplant (Non-Preemptive and Preemptive) • By End User (Hospitals and Transplant Clinics) • By Immunosuppressive Drug Class (Calcineurin Inhibitors, Antiproliferative Agents, mTOR Inhibitors, Corticosteroids, and Others) • By Organ Preservation Method (Static Cold Storage, Hypothermic Machine Perfusion, and Normothermic Machine Perfusion) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Novartis AG; Astellas Pharma Inc.; Sanofi; Pfizer Inc.; F. Hoffmann-La Roche Ltd; Veloxis Pharmaceuticals; Bristol-Myers Squibb Company; Thermo Fisher Scientific Inc.; BioLife Solutions, Inc.; TransMedics Group, Inc.; Terumo Corporation (OrganOx); XVIVO Perfusion AB; Dr. Franz Köhler Chemie GmbH; Teva Pharmaceutical Industries Ltd.; Bio-Rad Laboratories, Inc.; Immucor, Inc.; Paragonix Technologies; Organ Recovery Systems; Bridge to Life Ltd.; CareDx, Inc. |

Frequently Asked Questions
Key players include Novartis AG, Astellas Pharma Inc., Sanofi, Pfizer Inc., Bristol-Myers Squibb Company, Thermo Fisher Scientific Inc., TransMedics Group, Inc., Terumo Corporation (OrganOx) and XVIVO Perfusion AB.
Key opportunities include xenotransplantation, machine perfusion, biomarker-based monitoring and expansion of transplant capacity in Asia Pacific and other emerging regions.
The major growth factor is the rising number of patients with end-stage renal disease, driven by diabetes, hypertension and aging populations.
By Donor Type, the Living Donor segment dominated the market in 2025 with an estimated 53.00% share, supported by better graft survival and planned procedures.
North America dominated the market with a share of 42.00% in 2025, driven by high transplant volumes, insurance coverage and advanced transplant centers.
