
Clinical Trial Imaging Market Report Scope & Overview:
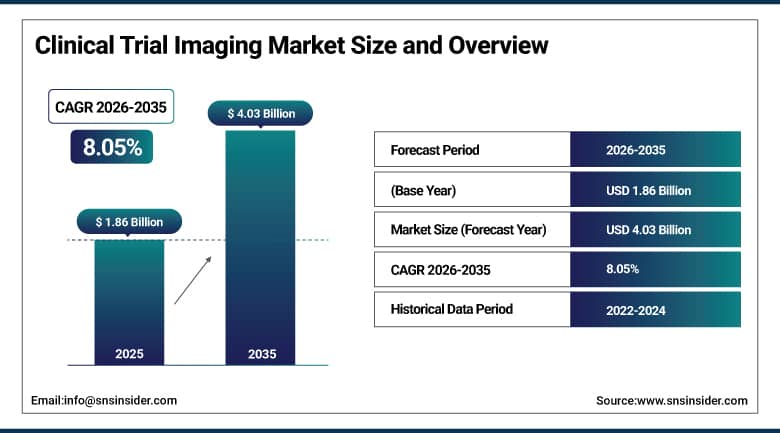
The Clinical Trial Imaging Market was valued at USD 1.86 Billion in 2025 and is expected to reach USD 4.03 Billion by 2035, growing at a CAGR of 8.05% from 2026-2035.
The Clinical Trial Imaging Market is growing as drug developers rely on imaging endpoints to measure whether a therapy works, especially in oncology, neurology and cardiovascular programs. Sponsors outsource image acquisition standards, quality control, central reading and quantitative analysis to specialist imaging core laboratories and contract research organizations (CROs). Services account for the largest share of spending, while cloud platforms and artificial intelligence (AI) software are gaining ground as trials generate larger image archives. Computed tomography (CT), magnetic resonance imaging (MRI) and positron emission tomography (PET) form the core of study protocols. North America leads the market through its concentration of sponsors and imaging CROs, while Asia Pacific is expected to grow fastest as trial activity expands.
⮞On September 9, 2025, the U.S. Food and Drug Administration (FDA) published the final ICH E6(R3) guideline on good clinical practice. The revision places greater weight on risk-based quality management and fit-for-purpose data systems, both of which affect how imaging data are collected and reviewed.
To Get More Information On Clinical Trial Imaging Market - Request Free Sample Report
Clinical Trial Imaging Market Trends
-
Use of artificial intelligence to extract quantitative imaging biomarkers and automate image quality checks
-
Shift toward cloud-based, end-to-end imaging platforms linked to electronic data capture systems
-
Growth of PET tracers for neurology and oncology trials, including tau and prostate-specific imaging agents
-
Consolidation of imaging CROs and core laboratories into larger clinical research platforms
-
Adoption of risk-based quality management under revised good clinical practice guidance
U.S. Clinical Trial Imaging Market Outlook
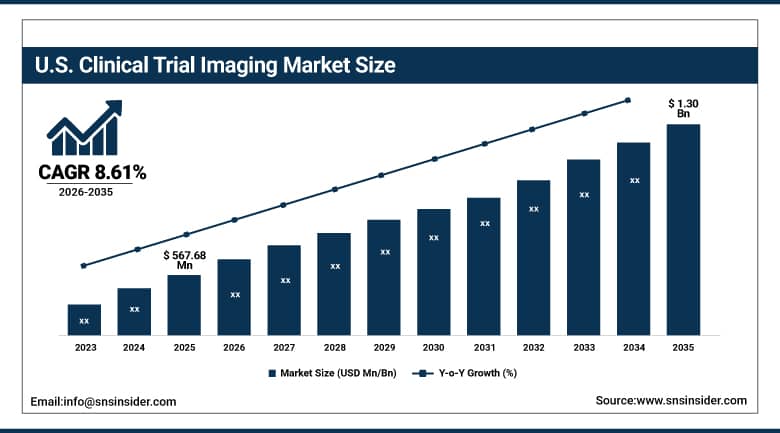
The U.S. Clinical Trial Imaging Market was valued at USD 567.68 Million in 2025 and is expected to reach USD 1.30 Billion by 2035, growing at a CAGR of 8.61% from 2026-2035.
The U.S. Clinical Trial Imaging Market is the largest national market for imaging services in drug development, supported by the concentration of pharmaceutical sponsors, biotechnology start-ups and academic medical centers. Oncology and neurology programs make heavy use of central imaging reads, and many specialist imaging core laboratories operate in the United States. The Food and Drug Administration has signaled openness to quantitative imaging endpoints and to the use of artificial intelligence in regulatory submissions. Radiopharmaceutical approvals are expanding the pool of PET tracers available to trials. Cloud-based imaging platforms now link sites, central readers and sponsors in one workflow. Demand is expected to rise as sponsors seek faster read turnaround, stronger audit trails and measurable endpoints.
⮞For instance, in January 2025 the FDA issued its first draft guidance on the use of artificial intelligence to support regulatory decision-making for drugs and biological products. The agency noted that it had reviewed more than 500 submissions with AI components since 2016.
Clinical Trial Imaging Market Segment Analysis
-
By Product, the Services segment dominated the Clinical Trial Imaging Market with approximately 69.30% share in 2025, and is also the fastest growing with a CAGR of approximately 8.48%.
-
By Modality, the Computed Tomography segment dominated the Clinical Trial Imaging Market with approximately 27.99% share in 2025, while the Positron Emission Tomography segment is the fastest growing with a CAGR of approximately 9.87%.
-
By Therapeutic Area, the Oncology segment dominated the Clinical Trial Imaging Market with approximately 34.18% share in 2025, while the Neurology segment is the fastest growing with a CAGR of approximately 9.05%.
-
By End User, the Pharmaceutical and Biotechnology Companies segment dominated the Clinical Trial Imaging Market with approximately 43.43% share in 2025, while the Contract Research Organizations segment is the fastest growing with a CAGR of approximately 9.66%.
-
By Trial Phase, the Phase III segment dominated the Clinical Trial Imaging Market with approximately 40.95% share in 2025, while the Phase I segment is the fastest growing with a CAGR of approximately 10.70%.
By Product, Services Dominates the Clinical Trial Imaging Market and Is Also the Fastest Growing
Services lead because sponsors rarely build imaging expertise in-house. Specialist providers design imaging charters, qualify sites and scanners, manage image transfer, perform quality control, run blinded independent central reviews and deliver analyzed data for regulatory filings. Each step requires radiologists, physicists and project managers, and the work recurs for every protocol amendment and trial phase. Regulators expect audit trails and reader training records, which pushes sponsors toward established core laboratories with validated procedures. Long-term partnerships also give providers visibility on workload and support investment in readers.
Services are also the fastest growing product group as trial designs grow more complex. Adaptive oncology protocols, multi-region neurology studies and rare disease programs depend on expert reads and endpoint adjudication, and imaging biomarker development has become a billable service in its own right. Software and cloud platforms form the second product group, with image management, workflow and AI analytics tools expanding quickly. Many providers bundle software with services, so platform adoption often follows a services contract rather than replacing it. Regulatory submissions often require documentation of reader variability, which only established core laboratories can supply.
⮞Flywheel reported on January 8, 2026 that 10 of the top 20 global pharmaceutical companies are customers of its imaging data platform. The platform launched a validated clinical trial imaging offering in December 2025.
By Modality, Computed Tomography Dominates the Clinical Trial Imaging Market and Positron Emission Tomography Grows Fastest
Computed tomography remains the leading modality because it is the standard tool for measuring tumor burden under response criteria such as RECIST, which anchor most oncology trials. Scans are widely available at investigator sites, acquisition is fast, and image quality is reproducible across scanner brands once protocols are harmonized. CT is also used in cardiovascular, pulmonary and musculoskeletal studies, which keeps volume steady across therapeutic areas. Central readers can measure lesions consistently, which supports its position in pivotal trials. Central readers also benefit from automated lesion tracking tools that speed repeat measurements.
Positron emission tomography is growing fastest as new tracers make it possible to measure biology rather than size. Amyloid and tau agents support Alzheimer's disease trials, prostate-specific membrane antigen tracers support prostate cancer programs, and FET and FDG tracers help in neuro-oncology and treatment response. Radiopharmaceutical therapies increase the need for dosimetry and quantitative uptake measurements. Magnetic resonance imaging follows closely, with growing use in neurology, liver disease and musculoskeletal programs, while ultrasound and X-ray support specialized studies. Contrast agents and new MRI sequences add further detail for body and brain studies.
⮞On September 14, 2026, Telix announced FDA approval of Pixclara (18F-FET), the first FDA-approved FET PET agent for glioma in adults and children aged one month and older. The approval widens the tracer options available to neuro-oncology trials.
By Therapeutic Area, Oncology Dominates the Clinical Trial Imaging Market and Neurology Grows Fastest
Oncology accounts for the largest share of imaging work because tumor response is judged by measurement on CT, MRI and PET, and cancer represents the largest part of the global drug pipeline. Immunotherapy and targeted therapy programs use standardized criteria that require central reads to limit variation between sites. Progression-free survival endpoints depend on timed scans and consistent interpretation, so sponsors commission blinded independent reviews for most registration studies. Specialist oncology imaging CROs have grown around this demand. Vendors have also built disease-specific reading protocols that shorten reader training time. Cardiovascular programs rely on plaque and ventricular function measurements, which broadens modality use.
Neurology is the fastest growing therapeutic area as Alzheimer's disease, Parkinson's disease, multiple sclerosis and stroke programs rely on imaging biomarkers. Amyloid and tau PET, volumetric MRI and perfusion imaging provide objective measures of disease progression and treatment effect. Antibody therapies for Alzheimer's disease introduced safety monitoring for imaging abnormalities, which adds scheduled MRI reads. Cardiovascular and metabolic programs also use imaging endpoints, particularly in liver fat and plaque assessment, which broadens the base of demand. Rare neurological disease studies also depend on specialized MRI protocols and reference centers.
⮞On August 14, 2026, Lantheus announced FDA approval of Tauklarify (MK-6240), a tau PET imaging agent. The approval adds a new agent for measuring tau pathology in Alzheimer's disease studies.
By End User, Pharmaceutical and Biotechnology Companies Dominates the Clinical Trial Imaging Market and Contract Research Organizations Grows Fastest
Pharmaceutical and biotechnology companies lead because they sponsor the trials and hold the budgets for imaging services. Large sponsors contract imaging core laboratories directly for pivotal programs, and many biotechnology start-ups rely on specialist providers because they lack internal imaging teams. Sponsors prefer vendors that can supply consistent reads across several studies, and master service agreements concentrate spending among a limited set of qualified providers. Pipeline growth in oncology and neurology keeps the number of imaging-dependent programs rising. Master agreements also allow sponsors to share image libraries across programs.
Contract research organizations are growing fastest as sponsors outsource entire trial operations, including imaging, to full-service partners. Large CROs have built or acquired imaging core laboratories, while specialist imaging CROs partner with them on complex programs. Medical device companies add a smaller stream of demand, because device trials often use imaging endpoints for structural and functional outcomes. Academic centers use central imaging for investigator-led studies, though budgets are smaller and procurement is more fragmented. Device makers and academic investigators together add steady but smaller volumes.
⮞Image Analysis Group and HeartcoR Solutions announced a strategic partnership on May 6, 2026 to deliver integrated cardiac safety and imaging core laboratory services for clinical trials.
By Trial Phase, Phase III Dominates the Clinical Trial Imaging Market and Phase I Grows Fastest
Phase III trials lead because they enroll the largest patient numbers and run at many sites, which multiplies the volume of images to acquire, check and read. Registration studies require blinded independent central reviews, rigorous site qualification and complete audit trails, all of which increase service content per trial. Long follow-up periods lead to repeated scanning, and regulatory expectations for endpoint consistency are highest at this stage. Sponsors therefore commit larger imaging budgets to late-stage programs than to early studies. Late-stage trials also trigger most requests for reader adjudication and data lock services.
Phase I is growing fastest as sponsors use imaging earlier to confirm target engagement, dosing and safety before committing to larger studies. Receptor occupancy PET, dynamic contrast MRI and quantitative biomarkers help teams make go or no-go decisions sooner. Faster review pathways for first-in-human studies in several countries are also bringing more early-phase trials to market regions such as China. Phase II studies remain an important middle stage, while Phase IV and post-marketing studies add smaller but steady demand for safety and effectiveness imaging.
⮞China's National Medical Products Administration published an announcement in October 2025 that adds a 30-day expedited review pathway for innovative drug trials, alongside the 60-day implied approval route. The change is intended to speed early-phase studies.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
71.83 |
|
Europe |
Germany |
22.37 |
|
Asia Pacific |
China |
31.76 |
|
Latin America |
Brazil |
43.29 |
|
Middle East & Africa |
Saudi Arabia |
34.82 |
North America Clinical Trial Imaging Market Insights
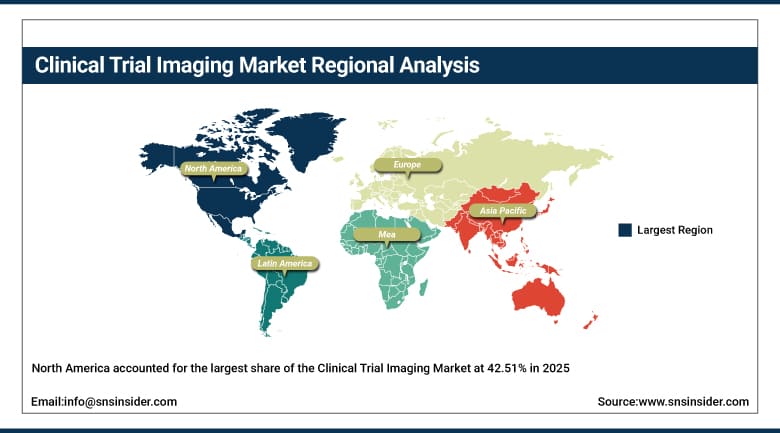
North America accounted for the largest share of the Clinical Trial Imaging Market at 42.51% in 2025, led by the United States and supported by Canada. The region hosts the largest group of pharmaceutical sponsors, biotechnology start-ups, imaging core laboratories and academic medical centers, and the FDA provides guidance that favors standardized imaging endpoints. Strong investment in oncology and neurology pipelines keeps imaging-dependent studies in steady supply. Venture-backed imaging software firms also cluster in Boston, San Francisco and Toronto, creating a deep talent pool.
Radiopharmaceutical approvals, new MRI contrast agents and AI-based reading tools are adding options for trial designers. Cloud platforms link sites, readers and sponsors, and several imaging providers have been acquired or merged into larger clinical research platforms. Canada contributes through hospital networks and cancer trial groups, while higher site costs and competition for experienced readers add to pricing pressure. Data privacy rules under HIPAA shape how images are transferred and stored. Large integrated delivery networks also supply real-world imaging archives that feed AI development and site selection.
⮞On June 15, 2026, Bayer announced FDA approval of Ambelvist (gadoquatrane), a low-dose gadolinium MRI contrast agent for central nervous system and body imaging, including in neonates.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Clinical Trial Imaging Market Insights
Europe is the second largest region, led by Germany, the United Kingdom, France, Italy and Spain. The region has a strong academic research base, well-established oncology and neurology trial networks, and imaging CROs headquartered in France and the United Kingdom. Harmonized review through the European Clinical Trials Regulation and the Clinical Trials Information System has made multi-country studies easier to run. Strong ethics review frameworks and long-standing cooperative oncology groups also contribute to a stable base of multinational studies. Rare disease networks add further depth.
Sponsors value European sites for high-quality data and access to patients in rare disease programs. Concerns over cost, complex data protection rules and varied national approvals add burden, but regulators are working to speed review times. AI developers in France, Spain and Belgium are building quantitative biomarker tools for trials, and partnerships between imaging CROs and device makers are common across the region. Imaging CROs in France, Germany and the United Kingdom also run reader panels that serve global pharmaceutical sponsors.
⮞The European Medicines Agency made the ICH E6(R3) good clinical practice guideline effective on July 23, 2025, setting updated expectations for trial quality management across the European Union.
Asia Pacific Clinical Trial Imaging Market Insights
Asia Pacific is projected to be the fastest growing region, with a CAGR of 8.89% during 2026-2035. China, Japan, South Korea, India and Australia are expanding their share of global trials, supported by large patient pools, faster regulatory review and rising domestic drug development. China is now a major source of oncology trials, and its research hospitals have invested in PET and MRI capacity. Hospital-based imaging investment and national policies that support local innovation also draw sponsors toward regional sites.
India is modernizing its clinical trial rules and attracting studies in oncology, diabetes and infectious diseases, while Australia is a popular site for early-phase trials because of its fast approval process. Global imaging CROs are opening regional offices and training local readers, and regional AI companies are entering trial imaging. Variation in scanner types, data transfer rules and reader qualifications still requires careful protocol standardization. Japan and South Korea add depth in neurology and cardiovascular trials with advanced scanner fleets.
⮞India's amended New Drugs and Clinical Trials Rules were reported on February 12, 2026, cutting test licence processing time from 90 to 45 days and removing prior permission for specified low-risk bioavailability and bioequivalence studies.
MEA & Latin America Clinical Trial Imaging Market Insights
In Latin America, Brazil, Mexico, Argentina and Colombia are the main trial locations, attracting sponsors with large treatment-naive populations and lower per-patient costs. Brazil has a national clinical research law, and Mexico is simplifying procedures to shorten authorization time. Imaging capacity is strongest in large private hospitals and university centers, and sponsors often rely on global core laboratories to standardize reads. Regulatory review queues remain a restraint in some countries. Several university hospitals also hold quality accreditations that support their use as imaging sites in global studies.
⮞In June 2026, Mexico's federal health regulator COFEPRIS announced a digital single window for 17 procedures, nine of them fully online, with trial authorization time reported to be cut to a maximum of 30 days.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Egypt and South Africa lead activity. Gulf governments are building research hubs and updating regulations to attract trials, and Saudi Arabia has an active medical device study review system. South Africa has long hosted multinational trials with solid hospital imaging infrastructure, while the creation of the African Medicines Agency is expected to harmonize review across the continent over time. Sponsors also use regional reference sites to supply patients for rare disease studies.
⮞On July 28, 2025, the Saudi Food and Drug Authority reported that it had evaluated 295 medical device clinical studies, approved 157 of them, and that 84 approved studies were underway.
Market Dynamics
Growth Drivers: Imaging Endpoints, Outsourcing and Complex Trial Designs Drive Growth in the Clinical Trial Imaging Market
Imaging endpoints are used more widely as drug developers look for objective, early measures of treatment effect. Oncology response criteria, amyloid and tau PET in neurology, and quantitative liver and cardiac measurements all give sponsors data that clinical symptoms cannot provide. As pipelines grow in oncology, neurodegeneration and metabolic disease, the number of studies that need standardized acquisition, central reads and quality control rises in step. Rising numbers of oncology and neurology agents in late-stage development also raise the number of imaging-dependent studies each year, which supports long-term growth.
Outsourcing and technology reinforce the trend. Sponsors prefer to buy imaging expertise from validated providers rather than maintain it in-house, and complex adaptive designs require fast, consistent reads. Cloud platforms shorten the time between scan and result, and artificial intelligence automates quality checks and measurement. Regulators have also encouraged risk-based oversight, which favors providers with integrated data systems and documented processes. Evidence that imaging biomarkers can shorten timelines also encourages sponsors to use them in earlier phases, where budgets were once limited.
⮞In November 2025, a report noted that the European Union Clinical Trials Regulation transition had ended on January 31, 2025, requiring all ongoing trials in the bloc to move into the Clinical Trials Information System.
Restraints: Regulatory Capacity, Data Variability and High Cost Restrain Growth in the Clinical Trial Imaging Market
Regulatory and operational hurdles slow growth in several regions. Review queues at some agencies lengthen the time before trials can start, and differing national rules on data transfer and patient privacy complicate multi-country imaging studies. Sponsors must also qualify scanners and train sites, which adds cost and time, particularly in emerging markets where equipment is older or inconsistent. Regulators in several markets have not yet issued detailed guidance on AI-derived endpoints, which makes some sponsors cautious about adopting them. Insurance rules in some regions also limit scan frequency.
Cost and variability add further pressure. Advanced PET tracers require access to cyclotrons or radiopharmacies, and not all sites can supply them. Image quality varies between scanners, so harmonization is needed before data can be pooled. Specialist radiologists and imaging scientists are in short supply, which raises labor costs. Smaller sponsors may limit imaging to a few key endpoints because budgets are tight, reducing the scope of services purchased. Competition among providers also compresses prices on standard reads, which limits margin growth for service firms.
⮞A November 2025 report said that Brazil's health regulator ANVISA would create a dedicated clinical trial review queue, after its staff fell 30% between 2014 and 2024.
Opportunities: Artificial Intelligence, New Tracers and Regional Harmonization Create Opportunities in the Clinical Trial Imaging Market
Artificial intelligence creates the clearest new value pool. Algorithms can measure tumor volume, brain atrophy or liver fat consistently across thousands of scans, and they can screen images for eligibility and safety during enrollment. Providers that validate these tools to regulatory standards can offer faster turnaround and richer biomarkers than manual reads. Sponsors are also interested in using trial images to build proprietary datasets for later programs. Providers that bundle tracer supply, site qualification and analysis could also win larger shares of radiopharmaceutical development programs.
New tracers and regional harmonization expand the addressable market. Radiopharmaceutical therapies need paired diagnostic imaging and dosimetry, and neurology agents widen PET use. Common review frameworks across Africa, Latin America and Southeast Asia could open more trial sites, creating demand for local imaging capacity and training. Partnerships between imaging CROs, device makers and AI developers offer further routes into emerging markets. Cross-border data platforms that comply with local privacy rules could also lower the barrier to multi-country studies. Data standards will help.
⮞On June 4, 2025, the African Medicines Agency named Dr. Delese Mimi Darko as its first Director General. The appointment advances efforts to harmonize medicines regulation across the continent.
Recent Developments:
-
2026: Thermo Fisher Scientific completed its acquisition of Clario Holdings, a provider of endpoint data and imaging services for clinical trials. The transaction adds a large imaging and endpoint platform to Thermo Fisher's clinical research offering.
-
2026: Medidata launched Medidata Imaging, an AI-based imaging solution for clinical trials, at the ASCO annual meeting. The product is designed to speed de-identification of patient data and anatomy verification in trial image workflows.
-
2025: Perspectum and InHealth announced a national MRI diagnostics partnership in the United Kingdom. The agreement adds capacity at the Oxford community diagnostic centre and creates a joint research network for multicentre studies.
-
2026: Altis Labs raised a USD 25 million Series A round backed by OrbiMed and Qiming to expand its AI quantitative imaging endpoints for oncology trials. The financing supports wider use of AI-derived endpoints in drug development.
Clinical Trial Imaging Market Key Players are:
-
Clario Holdings, Inc. (Thermo Fisher Scientific)
-
Calyx (Perceptive Imaging)
-
ICON plc
-
Medpace, Inc.
-
Imaging Endpoints
-
Median Technologies
-
WCG Intrinsic Imaging, LLC
-
Image Analysis Group
-
Medidata Solutions, Inc. (Dassault Systèmes)
-
Perspectum Limited
-
Flywheel
-
Altis Labs
-
Biotrial
-
Banook Group (Keosys)
-
QMENTA
-
Medical Metrics, Inc.
-
Brainomix Limited
-
Quibim
-
Invicro, LLC (Konica Minolta)
Clinical Trial Imaging Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.86 Billion |
| Market Size by 2035 | USD 4.03 Billion |
| CAGR | CAGR of 8.05% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Services and Software) • By Modality (Computed Tomography, Magnetic Resonance Imaging, Positron Emission Tomography, Ultrasound, X-Ray, and Others) • By Therapeutic Area (Oncology, Neurology, Cardiovascular, and Others) • By End User (Pharmaceutical and Biotechnology Companies, Contract Research Organizations, Medical Device Companies, and Others) • By Trial Phase (Phase I, Phase II, Phase III, and Phase IV) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Clario Holdings, Inc. (Thermo Fisher Scientific), Calyx (Perceptive Imaging), ICON plc, Medpace, Inc., Imaging Endpoints, Median Technologies, WCG Intrinsic Imaging, LLC, Image Analysis Group, Medidata Solutions, Inc. (Dassault Systèmes), Perspectum Limited, Flywheel, Altis Labs, Biotrial, Banook Group (Keosys), QMENTA, Medical Metrics, Inc., Brainomix Limited, Quibim, Invicro, LLC (Konica Minolta) |

Frequently Asked Questions
Key players include Clario, Calyx, ICON, Medpace, Imaging Endpoints, Median Technologies, WCG Intrinsic Imaging, Image Analysis Group, Medidata, Perspectum, Flywheel, Altis Labs, Biotrial, Banook, QMENTA, Medical Metrics, Brainomix, Quibim and Invicro.
Key opportunities include AI-derived imaging biomarkers, new PET tracers and radiopharmaceutical therapies, cloud-based imaging platforms, and regional harmonization of trial regulation in Asia Pacific, Latin America and Africa.
Growing use of imaging endpoints in oncology and neurology pipelines, together with outsourcing of imaging work to specialist providers, is the main growth factor, supported by cloud platforms and AI tools.
Services, Software are the sub segmBy Product, the Services segment dominated the market in 2025 with an estimated 69.30% share, supported by core laboratory reads, quality control and endpoint management.ents of Clinical Trial Imaging market.
North America dominated the market with a share of 42.51% in 2025, driven by the concentration of sponsors, imaging core laboratories and academic trial centers.
