
Stout Market Report Scope & Overview:
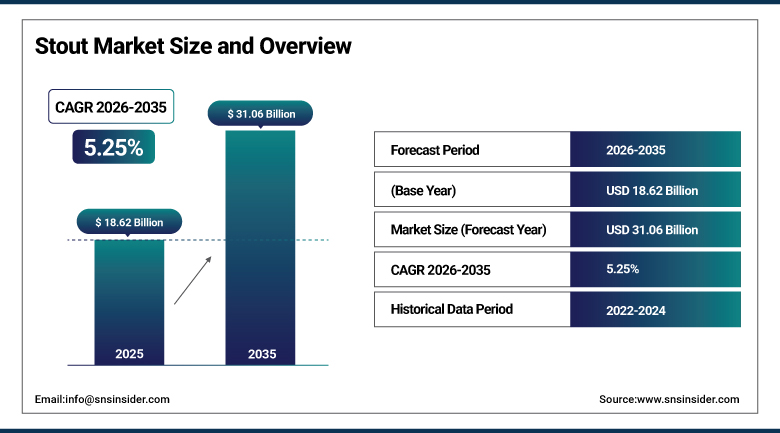
The Stout Market was valued at USD 18.62 Billion in 2025 and is expected to reach USD 31.06 Billion by 2035, growing at a CAGR of 5.25% from 2026 to 2035.
The Stout Market is showing signs of steady growth, thanks to the rising demand for dark beers due to increased preference for more flavors in beer such as chocolate, coffee, roasted malts, and caramel as opposed to light beers. The increased demand for craft and premium beers is also contributing to the rising demand for premium and flavorful stouts, especially new products such as coffee stouts and barrel-aged stouts. The growth in the hospitality sector and increasing disposable incomes among consumers are some of the additional factors that are leading to this trend. Apart from this, another factor that is supporting this trend is the growing popularity of the e-commerce channel for beverages, along with limited release or collector imperial stouts.
In May 2026, Diageo opened a new brewing facility near Newbridge, Ireland, representing an initial investment of approximately GBP 260 Million with plans for a second, adjacent brewery dedicated to producing Guinness and Guinness 0.0 for export, as part of a broader strategy to nearly double global Guinness production by 2029.
To Get more information Stout Market - Request Free Sample Report
Stout Market Trends
- Growing popularity of imperial stout, projected to grow at an 8.1% CAGR, is being driven by collector culture, limited releases, and barrel-aging innovation from craft breweries.
- Rising e-commerce beverage channel adoption, growing at an estimated 9.4% CAGR, is becoming one of the most transformative distribution trends for the category.
- Expanding non-alcoholic stout production is emerging as major brewers invest in zero-proof variants to capture moderation-focused consumers.
- Increasing brewery investment in nitrogen-infused dispensing technology, including consumer-oriented draught devices, is bringing pub-quality stout experiences into home consumption occasions.
- Growing milk stout and oat-based variant innovation is broadening flavor profile diversity beyond traditional barley-based dry stouts.
U.S. Stout Market Outlook
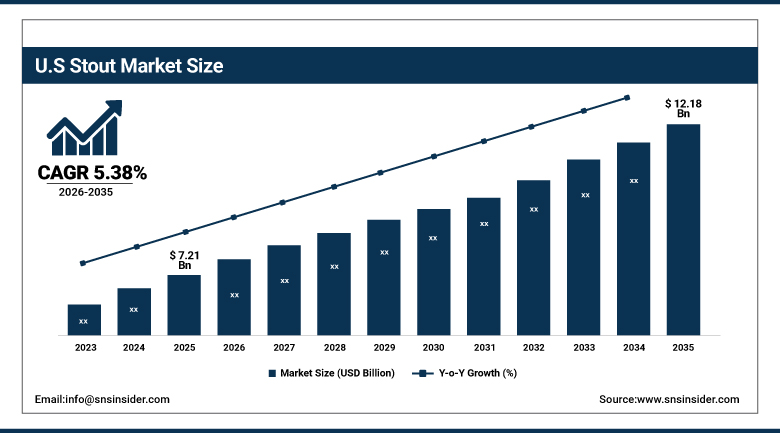
The U.S. Stout Market was valued at USD 7.21 Billion in 2025 and is projected to reach USD 12.18 Billion by 2035, growing at a CAGR of 5.38% during 2026-2035.
The U.S. Stout Market is expanding consistently because of the high popularity of craft beer among people and the growing tendency towards premiumization and flavoring among consumers. The craft breweries like Founders, Goose Island, and BrewDog keep fueling the trend of consumption of aged and special editions of imperial stouts. The e-commerce became one of the most revolutionary growth channels in terms of stout marketing. Thanks to such e-commerce platforms as Drizly, the websites of breweries and beer subscriptions, the craft breweries are able to sell their products to the widely distributed consumers. Such innovations as nitrogen canning technology and dry stout are continuing to expand the consumer options.
2025: Guinness expanded its U.S. retail presence with a limited-edition Draught Stout can featuring a redesigned toucan theme, targeting consumer demand for convenient packaged stout formats and supporting increased off-premise consumption.
Stout Market Segment Analysis
- By Product Type, dry stout segment dominated the stout market in 2025 with around 34.20% share; imperial stout segment is the fastest-growing segment.
- By Source, barley-based segment dominated the market in 2025; oat-based/others segment is the fastest-growing segment.
- By Packaging, canned segment dominated the market in 2025 with around 41.00% share; draft/kegs segment is the fastest-growing segment.
- By Distribution Channel, off-trade/retail segment dominated the market in 2025; online segment is the fastest-growing segment.
By Product Type, Dry Stout Dominates the Stout Market While Imperial Stout Registers the Fastest Growth
Dry Stout has the most share in the Stout Market, contributing 34.20% revenue in 2025, led by the popular Guinness style beers which have made names across more than 150 countries. Dry stout has benefited from the branding efforts made by brands during several decades and their wide presence in the trade segment. The brand equity and presence in the global distribution network make this segment continue to be dominant in the Stout Market.
Imperial Stout is the fastest growing segment, expected to grow at 8.1% CAGR throughout the forecast period, due to the influence of collectors’ culture, limited releases, and innovations in the segment such as barrel-aging of stouts by craft brewers like Founders, Goose Island, and BrewDog. Increased willingness of consumers to spend money for high-alcohol content and intense flavors makes the craft brewers produce more imperial stouts.
By Source, Barley-Based Dominates the Stout Market While Oat-Based Emerge as the Fastest-Growing Source
Barley-Based dominates the Stout Market in 2025, as barley malt remains the traditional and most widely used grain base for stout production, delivering the roasted, full-bodied character that defines the category. Barley-based stout benefits from established brewing infrastructure and centuries of traditional brewing expertise passed down through generations of brewers. The traditional brewing methodology and established grain supply chains for barley-based stout are reinforcing this segment’s continued market leadership.
Oat-Based is experiencing rapid growth driven by increasing consumer interest in milk stout and oat stout variants that offer smoother, creamier mouthfeel characteristics distinct from traditional dry stout profiles. Rising craft brewery experimentation with alternative grain bases and adjunct ingredients is compelling brewers to expand flavor profile diversity beyond conventional barley-based formulations. Growing consumer interest in novel texture and flavor experiences within the stout category is opening up substantial opportunities for commercial utilization in this segment.
By Packaging, Canned Dominates the Stout Market While Draft/Kegs Register the Fastest Growth
Canned dominates the Stout Market, accounting for 41.00% of revenue in 2025, due to its convenience, portability, and compatibility with modern retail and e-commerce distribution channels that have become increasingly important for craft breweries. Canned stout benefits from advances in nitrogen-infusion technology, including specialized widget devices that replicate draft-quality pours from a can. The convenience and retail-friendly format of canned stout are reinforcing this segment’s continued market leadership.
Draft/Kegs is experiencing rapid growth as the hospitality industry expansion and rising consumer interest in on-premise, freshly poured stout experiences drive demand for keg-based distribution. Rising investment in consumer-oriented nitrogen dispensing devices is extending the pub-quality draft experience into home consumption occasions. Growing brewery taproom and brewpub culture is opening up substantial opportunities for commercial utilization in this segment.
Regional Analysis
|
Region |
Country |
Share (2025) |
|
Europe |
United Kingdom |
26.40% |
|
North America |
United States |
85.60% |
|
Asia Pacific |
China |
32.20% |
|
Middle East & Africa |
UAE |
17.60% |
|
Latin America |
Brazil |
23.80% |
North America Stout Market Insights
North America is expected to register the fastest CAGR in the Stout Market during 2026–2035, driven by rising craft beer culture, premiumization trends, and expanding e-commerce beverage channels that are particularly strong across the United States and Canada. The United States dominated regional revenue in 2025, supported by strong craft brewery presence and collector-driven demand for imperial stout variants. Rising product innovation, including barrel-aged and limited-release formats, is further supporting market expansion. Rising demand for premium, flavor-forward stout products is also reinforcing North America’s above-average growth trajectory compared with more mature European markets.
The United States accounted for approximately 85.60% of the North American market in 2025, reflecting its strong craft beer culture and extensive brewery and e-commerce distribution infrastructure. Canada is contributing to regional growth through steady demand for craft and premium stout products.
Europe Stout Market Insights
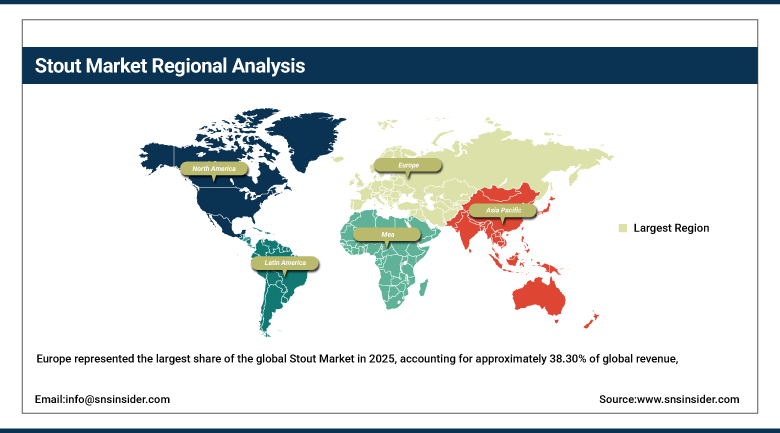
Europe represented the largest share of the global Stout Market in 2025, accounting for approximately 38.30% of global revenue, anchored by the United Kingdom and Ireland’s deep-rooted stout brewing tradition and Guinness’s status as a globally recognized brand originating from the region. Shifting consumer preferences, cultural factors, and continuous product innovation continue supporting growth across the UK stout market specifically. Rising demand for craft and premium stout variants across the region’s mature beer culture is reinforcing regional market leadership. Well-established brewing infrastructure and distribution networks across the United Kingdom, Ireland, and Germany are also improving product accessibility and sustaining regional market development.
The United Kingdom accounted for approximately 26.40% of the European market in 2025, supported by a combination of shifting consumer preferences, cultural factors, and product innovation driving growth. Ireland and Germany are also contributing meaningfully to regional growth, with Ireland home to Guinness’s iconic St. James’s Gate brewery and deep cultural stout heritage.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Stout Market Insights
Asia Pacific held a significant share of the Stout Market in 2025, supported by rising disposable incomes and growing western-influenced beer culture across major urban centers. Rising demand for premium and imported stout brands across China, Japan, and South Korea is supporting product innovation. Increasing craft beer culture adoption and growing consumer interest in diverse beer styles are further reinforcing the region’s market position.
China accounted for approximately 32.20% of the Asia Pacific market in 2025, supported by its expanding urban craft beer culture and rising demand for premium imported beer brands. Japan and South Korea are also contributing meaningfully to regional growth, with growing consumer interest in Western-style dark beer varieties.
Middle East & Africa and Latin America Stout Market Insights
The Middle East & Africa region is showing consistency in terms of growth in permissible markets, as the premium beer culture continues to spread in selected countries of the Gulf, along with the tourism-oriented hospitality sector. In the case of Latin America, there is growth due to increasing craft beer culture and interest in premium beer and imported stouts.
In the Middle East & Africa region, the UAE was at the forefront with a 17.60% regional share in 2025, aided by increasing investment in the hospitality and tourism sector. Brazil accounted for 23.80% of the Latin American market share in 2025, fueled by craft beer culture, whereas Mexico also contributed to growth in the region.
Market Dynamics
Growth Drivers: Craft Beer Culture and Premiumization Trends Driving Market Growth
The key drivers behind the expansion of the Stout Market are increased popularity of craft beers, along with increased consumer preference for better and flavorful beers. Since consumers nowadays want more flavor in their beer, like chocolate, coffee, roasted malts, and caramel flavors, there are immense opportunities for growth in both mainstream and craft stouts that have been identified by the breweries.
Growth in the hospitality industry, along with rising incomes of consumers, continues to fuel stout drinking habits across on-trade and off-trade avenues. Innovation in the form of barrel-aging, nitrogen-infusion, and flavored brewing processes has been instrumental in the development of new products.
Restraints: Health Consciousness and Premium Pricing Sensitivity Limiting Market Expansion
While there is favorable demand, some constraints arise owing to the trend towards health awareness and moderation among consumers which is making brewers develop non-alcoholic or low ABV beers in order to remain relevant. In addition, the high cost of premium and craft stout beer limits accessibility for consumers who are interested in value products especially in developing nations. Alcohol labeling and advertising policies in different regions are still affecting market entry plans for foreign brands.
Barrel aging, nitrogen injection and use of premium ingredients make the cost of production very high hence making it difficult for the craft brewers to be competitive price wise. There is stiff competition from multinational brewers and craft brands within the market which is putting pressure on prices.
Opportunities: E-Commerce Expansion and Non-Alcoholic Innovation Creating New Growth Avenues
There are many opportunities available through expanding the e-commerce beverage channel, developing new non-alcoholic and zero-proof stouts, and creating premium hospitality experiences. By developing subscription and brewery direct services via e-commerce channels, companies can take advantage of the growth rate of the channel as the fastest growing distribution channel. In addition, brewers can take advantage of the growth in demand for non-alcoholic stout types which would allow moderate consuming customers to keep enjoying their favorite brands. Another way is by developing premium hospitality experiences such as the brewery visitor centers and the taprooms.
The innovation in nitrogen dispensing technologies for home consumption would allow companies to build a differentiated and premium product position and attract consumers looking for pub-quality experiences out of pubs. Making investments in the capacity and production increase such as establishing new brewing facilities dedicated for exports can be an opportunity for companies. Increasing barrel-aged and collectible limited releases is another option for companies to build their differentiation.
Recent Developments:
- 2026: Diageo revealed plans to launch the Guinness Nitrosurge Tap, a consumer dispensing device, in Ireland, the UK, and the United States.
- 2025: Goose Island expanded its Bourbon County Stout portfolio with multiple limited-edition variants, including fruit-, chocolate-, nut-, and whiskey-influenced formulations, reinforcing product premiumization and flavor experimentation within the stout segment.
- 2024: Guinness introduced Fonio Stout in collaboration with Brooklyn Brewery as part of the Brewing for Impact initiative, incorporating the West African grain fonio and highlighting greater experimentation with heritage grains and culturally inspired stout formulations.
Stout Market key players are:
- Diageo plc (Guinness)
- Molson Coors Beverage Company
- Heineken N.V.
- Carlsberg Group
- Anheuser-Busch InBev SA/NV
- Boston Beer Company
- Sierra Nevada Brewing Co.
- Stone Brewing Co.
- Brooklyn Brewery
- BrewDog PLC
- Founders Brewing Company
- Deschutes Brewery
- Bell’s Brewery
- Left Hand Brewing Company
- Goose Island Beer Company
- Wells & Young’s Brewing Company
- Heineken Ireland (Murphy’s)
- Rogue Ales & Spirits
- Great Lakes Brewing Co.
- Guinness Ireland Group Limited
Stout Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 18.62 Billion |
| Market Size by 2035 | USD 31.06 Billion |
| CAGR | CAGR of 5.25% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Dry Stout, Imperial Stout, Milk Stout, and Others) • By Source (Barley-Based, and Oat-Based) • By Packaging (Canned, Draft/Kegs, and Bottled) • By Distribution Channel (Off-Trade/Retail, and Online) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Diageo plc (Guinness); Molson Coors Beverage Company; Heineken N.V.; Carlsberg Group; Anheuser-Busch InBev SA/NV; Boston Beer Company; Sierra Nevada Brewing Co.; Stone Brewing Co.; Brooklyn Brewery; BrewDog PLC; Founders Brewing Company; Deschutes Brewery; Bell’s Brewery; Left Hand Brewing Company; Goose Island Beer Company; Wells & Young’s Brewing Company; Heineken Ireland (Murphy’s); Rogue Ales & Spirits; Great Lakes Brewing Co.; Guinness Ireland Group Limited. |
Frequently Asked Questions
Key players include Diageo plc (Guinness), Molson Coors Beverage Company, Heineken N.V., Carlsberg Group, and Anheuser-Busch InBev SA/NV, among others.
Key opportunities include e-commerce beverage channel expansion, non-alcoholic and zero-proof stout innovation, premium hospitality experience development, nitrogen dispensing technology for home consumption, and expanding barrel-aged collector-oriented releases.
The market is driven by the growing popularity of craft beers and increasing demand for premium and flavorful beers among evolving beer enthusiast preferences.
The Dry Stout segment dominated the Stout Market in 2025, accounting for 34.20% of revenue share.
The Europe region dominated the Stout Market in 2025, accounting for approximately 38.30% of global market share, anchored by the United Kingdom and Ireland’s deep-rooted stout brewing tradition.
