
Subsea Well Access System Market Report Scope & Overview:
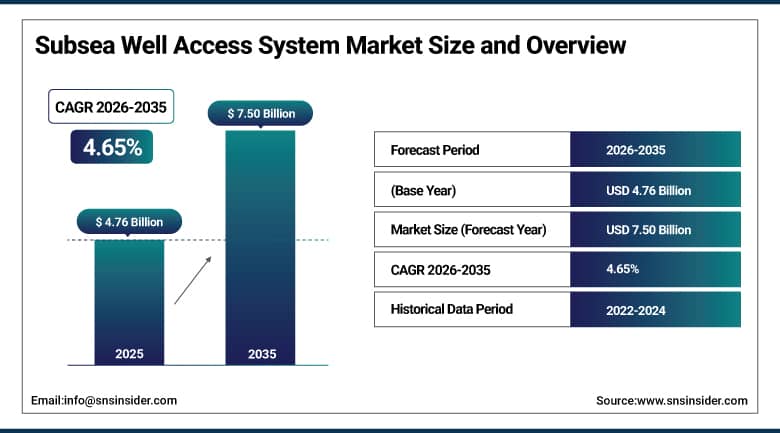
The global Subsea Well Access System Market was valued at USD 4.76 Billion in 2025 and is expected to reach USD 7.50 Billion by 2035, growing at a CAGR of 4.65% from 2026 to 2035.
Subsea well access is the term used to describe technologies and services which enable access to subsea wells drilled on the seafloor for purposes of intervention, monitoring, and maintenance activities, thus enabling the offshore oil and gas production without any surface facilities. With the trend of exploration moving into deeper waters, companies are increasingly adopting subsea architecture to keep costs under control and extend life of the fields, thus fueling the requirement of well access systems that are efficient and safe.
A contract had been awarded to Oceaneering International's Offshore Projects Group in 2025 by bp Exploration (Caspian Sea) Limited for providing riserless light well intervention services in the Azeri-Chirag-Deepwater Gunashli oilfield. This is going to be the first time when the RLWI technology will be utilized by bp in its Caspian Sea operations.
Market Size and Forecast
-
Market Size in 2026E: USD 4.98 Billion
-
Market Size by 2035: USD 7.50 Billion
-
CAGR: 4.65% from 2026 to 2035
-
Fastest Growing Region: Asia Pacific
-
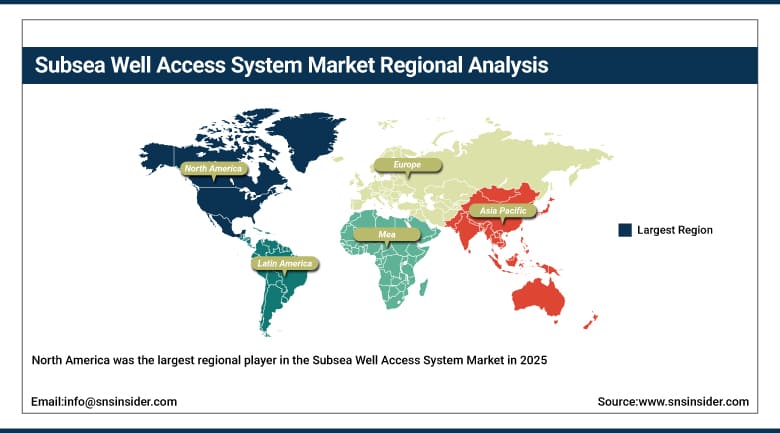
Largest Region: North America
To Get More Information On Subsea Well Access System Market - Request Free Sample Report
Subsea Well Access System Market Trends
-
Growing brownfield optimization and aging subsea infrastructure requirements are fueling sustained demand, with over 60% of Golden Triangle wells drilled between 2005 and 2015.
-
Rising zero-discharge regulatory requirements are driving adoption of closed-loop electro-hydraulic controls that prevent hydraulic fluid venting during tool disconnects.
-
Expanding vessel-based well access system adoption is gaining traction for cost efficiency and flexibility in shallow and mid-depth field applications.
-
Increasing use of advanced technologies in subsea intervention is enabling safer operations, enhanced productivity, and maximized performance in complex deepwater fields.
-
Growing riserless light well intervention adoption is reducing costs and complexity relative to conventional rig-based well access approaches.
U.S. Subsea Well Access System Market Outlook
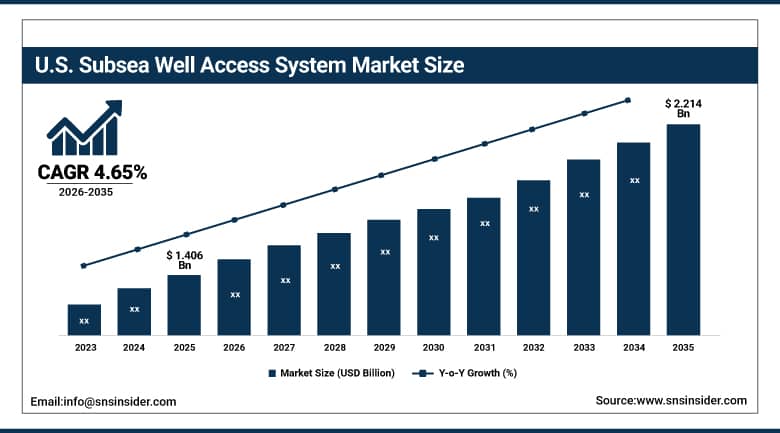
The U.S. Subsea Well Access System Market was valued at USD 1.406 Billion in 2025 and is projected to reach USD 2.214 Billion by 2035, growing at a CAGR of 4.65% during 2026-2035.
Strong Gulf of Mexico exploration and production activity continues to support robust market growth across the United States, reinforced by the country's leading position in the rig-based well access system segment. Leading operators continue to expand riserless light well intervention capability and digital control system deployment addressing rising deepwater asset integrity requirements. Growing decommissioning activity across aging Gulf of Mexico infrastructure continues to reinforce sustained subsea well access system demand nationwide.
Weatherford International won two contracts in 2026 with Constellation Oil Services to support offshore well intervention and managed pressure drilling operations in Brazil's Búzios Field and Campos and Espírito Santo Basins, reflecting the continued expansion of subsea well access service scope among leading U.S.-headquartered operators serving international deepwater markets.
Subsea Well Access System Market Segment Analysis
-
By Location, Deepwater led the Subsea Well Access System Market with a 43.50% share in 2025, while Ultra-Deepwater is the fastest-growing location segment with a CAGR of 8.60% from 2026-2035.
-
By Type, Rig-Based Well Access Systems led the Subsea Well Access System Market with a 62.40% share in 2025, while Vessel-Based Well Access Systems is the fastest-growing type segment with a CAGR of 7.20% from 2026-2035.
-
By Application, Well Intervention led the Subsea Well Access System Market with a 48.60% share in 2025, while Production Enhancement is the fastest-growing application segment with a CAGR of 8.20% from 2026-2035.
By Location, Deepwater Dominated the Market While Ultra-Deepwater Is the Fastest-Growing Segment
The Deepwater segment emerged as the front-runner in the Subsea Well Access System Market with a revenue share of 43.50% in 2025, on account of the ongoing trend of moving offshore operations into deeper waters that require special well access system technology. The Deepwater category continues to remain the largest and the most challenging sub-segment for the deployment of subsea well access systems, ensuring the dominance of this location segment within the overall market.
The Ultra-Deepwater segment is anticipated to exhibit the highest CAGR of 8.60% during the forecast period 2026-2035, owing to the increasing trend of shifting exploration activities towards deeper waters that need enhanced pressure and intervention capabilities. Growing pre-salt deepwater development in the offshore basins of Brazil continues to strengthen the growth prospects of this segment.
By Type, Rig-Based Well Access Systems Dominated the Market While Vessel-Based Well Access Systems Is the Fastest-Growing Segment
Rig-Based Well Access Systems dominated the Subsea Well Access System Market and accounted for a revenue share of 62.40% in 2025 owing to the reliability and wider applicability in challenging deepwater conditions on offshore rigs. The rig-based systems are still performing better in terms of efficiency and reliability in intervention and completion activities making this category the dominant one in the wider subsea well access system market.
Vessel-Based Well Access Systems are estimated to witness the highest CAGR of 7.20% from 2026-2035 fueled by the increasing need for cost-effective and more flexible options for shallow and mid-depth fields. Ongoing modernization efforts in vessels in the major North Sea and offshore basins have further fueled the above average growth of this segment in comparison to traditional rig-based systems.
By Application, Well Intervention Dominated the Market While Production Enhancement Is the Fastest-Growing Segment
The Well Intervention category topped the Subsea Well Access System Market with a share of 48.60% in 2025 owing to the high necessity of accessing and maintenance of offshore wells considering that the offshore industry as a whole is currently faced with a maturing inventory, where 60% of subsea wells in the Gulf of Mexico, Brazil, and West Africa were drilled and completed between 2005 and 2015. The application of well intervention remains overwhelmingly successful compared to well completion and decommissioning applications, ensuring its leading role within the overall subsea well access system market.
The Production Enhancement category is projected to witness the highest CAGR of 8.20% through 2026-2035 fueled by the growing number of operators who leverage subsea solutions in order to cut costs and prolong field lifetime in mature and maturing offshore assets. Growing demand for innovations that would help increase recovery and prolong production from existing wells remains the key driver behind the above-average growth rate of this category compared to well intervention applications.
Regional Insights
|
Region |
Country |
Share (2025) |
|---|---|---|
|
North America |
United States |
84.60% |
|
Europe |
Norway |
28.60% |
|
Asia Pacific |
China |
34.60% |
|
Middle East & Africa |
Saudi Arabia |
32.60% |
|
Latin America |
Brazil |
36.60% |
North America Subsea Well Access System Market Insights
North America was the largest regional player in the Subsea Well Access System Market in 2025 in terms of global market revenue, holding 34.90% of the same, aided by high levels of exploration and production in the Gulf of Mexico and the use of rig-based well access systems. North America's mature offshore industry services and presence of major subsea equipment manufacturers will continue to support the region's dominance in the subsea well access system market.
The US constituted nearly 84.60% of North America's market in 2025 owing to its large Gulf of Mexico offshore facilities and domination in the area of rig-based well access systems. Canada is helping to fuel regional growth with its investments in the offshore energy sector and increasing adoption of subsea intervention technology.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Subsea Well Access System Market Insights
Europe was one of the significant regions in the Global Subsea Well Access System Market in 2025, thanks to the development of operations in the North Sea as well as upgrades to vessels in various offshore regions. The growing zero discharge regulation is expected to keep the demand for closed-loop electro-hydraulic control systems stable in the region.
Norway dominated the European market in 2025, with a regional share of 28.60%, thanks to the presence of a large number of North Sea offshore assets and vessel upgrades within the country. Other regions that have made contributions include the United Kingdom, the Netherlands, and Denmark due to the high demand for well interventions in North Sea offshore assets.
Asia Pacific Subsea Well Access System Market Insights
The Asia Pacific region is expected to see the fastest growth during the forecast period 2026-2035 owing to the government-supported projects of deep sea exploration and offshore energy investment in China, India, and Southeast Asia. The ongoing trend of government-supported offshore energy exploration continues to propel the above-average growth of this region compared to more developed Western regions.
In 2025, China made up about 34.60% of the Asia Pacific region owing to the state-sponsored projects of deep sea exploration in the South China Sea and increased domestic subsea equipment manufacturing capabilities. India, Japan, and Malaysia are also playing a significant role in the growth of this region with India benefiting from deep water offshore energy development projects.
Middle East & Africa and Latin America Subsea Well Access System Market Insights
The Middle East & Africa segment continues to maintain strong market share, thanks to steady investment in deepwater activities and development of offshore drilling activities within the Gulf nations. In the Latin America region, the market is gaining from deepwater presalt activities in addition to the presence of significant offshore oil production facilities within the region.
Saudi Arabia was the leading country within the Middle East & Africa region, accounting for 32.60% regional share in 2025 due to steady investment in deepwater activities and offshore drilling activities. Brazil held 36.60% of the market share within the Latin American region in 2025 owing to deepwater presalt field activities, and so did Mexico.
Growth Drivers: Deepwater Exploration Expansion and Aging Infrastructure Requirements Driving Market Growth
Demand from deepwater exploration activities, high standards of safety operations, and the need for efficiency in existing mature offshore fields continues to lead the Subsea Well Access System Market. With the move towards offshore oil exploration activities, companies are depending more and more on subsea configurations in order to cut down costs and increase the life of the field, thus continuing to create demand for access systems which can minimize intervention risks and improve efficiency and safety.
Demand is continued to be fueled by growing needs for optimization in brownfields, and requirements of aging subsea infrastructure, with a large number of Golden Triangle wells already requiring interventions due to their aging nature. Growing zero-discharge regulations are pushing up the adoption of closed-loop electro-hydraulic controls. Growing adoption of well access systems on vessels is becoming popular among companies.
Restraints: High Capital Costs and Complex Regulatory Compliance Limiting Market Expansion
Despite favorable underlying demand, the market faces meaningful restraints related to substantial capital investment required for advanced subsea well access systems, particularly for ultra-deepwater applications requiring specialized pressure management capability. Stringent regulations for oil spill prevention and drilling tool management, following heightened awareness of offshore operation safety since the Deepwater Horizon oil spill accident, continue to add compliance complexity and cost for operators.
Complex engineering requirements for zero-discharge, closed-loop electro-hydraulic control systems continue to extend equipment development and certification timelines for manufacturers. Growing competitive intensity among an expanding roster of subsea equipment and service providers also continues to compress margins across mainstream well access system categories, adding pricing pressure for established operators.
Opportunities: Riserless Intervention Technology and Brownfield Optimization Creating New Growth Avenues
There is substantial room for growth in the riserless light well intervention technology that would reduce costs and complications compared to traditional methods of accessing wells through rig-based interventions. Companies which are successful in commercializing innovative riserless intervention systems can be able to gain substantial market share from the category growth driven by the need for efficient and cost-effective solutions.
The growing scope for brownfield optimization due to the aging infrastructure in offshore areas is another important avenue of growth, with over 60% of offshore wells in major basins requiring intervention due to their age. Growing pre-salt deepwater operations in Latin America and state-driven exploration operations in Asia Pacific represent another important untapped avenue of growth for subsea well access equipment providers.
Recent Developments:
-
2025: Oceaneering International's Offshore Projects Group was awarded a contract by bp Exploration (Caspian Sea) Limited for riserless light well intervention services in the ACG oilfield.
-
2026: Weatherford International won two contracts with Constellation Oil Services to support offshore well intervention and managed pressure drilling operations in Brazil.
-
2026: Proserv's Stavanger-based sampling division was awarded a contract by Aker Solutions to supply a Multiphase Sampling Unit for the Brage platform offshore Norway.
-
2025: Oceaneering secured a five-year inspection and asset integrity services contract with a Qatar-based oil company through its Integrity Management and Digital Solutions segment.
Subsea Well Access System Companies are:
-
Baker Hughes Company
-
Aker Solutions ASA
-
National Oilwell Varco, Inc. (NOV Inc.)
-
Weatherford International plc
-
Oceaneering International, Inc.
-
Dril-Quip, Inc.
-
Proserv Group Inc.
-
Helix Energy Solutions Group, Inc.
-
Saipem S.p.A.
-
Optime Subsea AS
-
TechnipFMC plc
-
Schlumberger Limited (SLB)
-
Trendsetter Engineering, Inc.
-
Forum Energy Technologies, Inc.
-
Expro Group Holdings N.V.
-
Enpro Subsea Ltd.
-
IKM Group
-
GE Vernova
Subsea Well Access System Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 4.76 Billion |
| Market Size by 2035 | USD 7.50 Billion |
| CAGR | CAGR of 4.65% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Rig-Based Well Access Systems, Vessel-Based Well Access Systems) • By Application (Well Intervention, Completion, Decommissioning, Production Enhancement) • By Location (Deepwater, Shallow Water, Ultra-Deepwater) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Baker Hughes Company, Aker Solutions ASA, National Oilwell Varco, Inc. (NOV Inc.), Subsea 7 S.A., Weatherford International plc, Oceaneering International, Inc., Dril-Quip, Inc., Proserv Group Inc., Helix Energy Solutions Group, Inc., Saipem S.p.A., Optime Subsea AS, TechnipFMC plc, Schlumberger Limited (SLB), Halliburton Company, Trendsetter Engineering, Inc., Forum Energy Technologies, Inc., Expro Group Holdings N.V., Enpro Subsea Ltd., IKM Group, GE Vernova |
Frequently Asked Questions
The Subsea Well Access System Market is expected to grow at a CAGR of 4.65% from 2026 to 2035.
The Subsea Well Access System Market was valued at USD 4.76 Billion in 2025.
The market is driven by increasing demand in deepwater exploration, high standards in safety operations, and efficiency requirements in old mature offshore fields.
The Rig-Based Well Access Systems segment dominated the Subsea Well Access System Market in 2025, accounting for approximately 62.40% market share.
The North America region dominated the Subsea Well Access System Market in 2025, accounting for approximately 34.90% market share.
