
Surgical Helmet Market Report Scope & Overview:
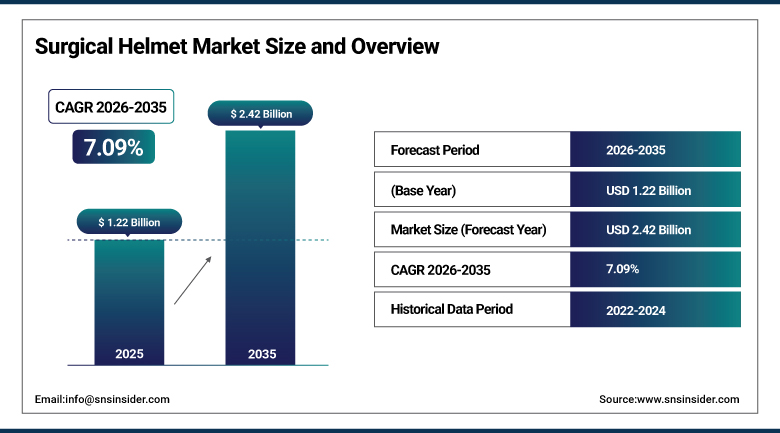
The Surgical Helmet Market was valued at USD 1.22 Billion in 2025 and is expected to reach USD 2.42 Billion by 2035, growing at a CAGR of 7.09% from 2026-2035.
Surgical helmets are powered personal protection systems worn by surgeons and operating room staff during procedures with a high risk of contamination or splash exposure, most commonly joint replacement and other orthopedic surgery. A helmet, integrated fan, battery, and disposable hood or toga together create a positive-pressure barrier that protects the wearer from bodily fluids while filtering exhaled air away from the sterile field, reducing the risk of surgical site infection for the patient. Roughly 15 million joint replacement procedures are performed globally each year, and an ageing population is expanding demand for orthopedic and neurosurgical intervention more broadly. Manufacturers continue to refine airflow, noise, weight, and field of vision, and hospitals are increasingly standardising on complete, reusable helmet systems rather than combining separate components.
In 2025, Stryker launched its Steri-Shield 8 personal protection system, offering a customisable helmet and three toga options. The system delivers a brighter helmet light, a 22 percent wider field of vision than the prior generation, and a fan design that targets the front and back of the wearer's neck to improve comfort during long procedures.
To Get more information Surgical Helmet Market - Request Free Sample Report
Surgical Helmet Market Trends
-
Rising adoption of complete, reusable helmet systems over separately purchased components.
-
Growing emphasis on wider field of vision and anti-fog visor technology during long procedures.
-
Expanding demand for lighter, quieter helmet designs that reduce surgeon fatigue.
-
Increasing standardisation of personal protection systems across hospital orthopedic departments.
-
Rising adoption of surgical helmets within ambulatory surgical centers performing joint procedures.
-
Growing supplier investment in customisable fit and integrated lighting for improved usability.
U.S. Surgical Helmet Market Overview
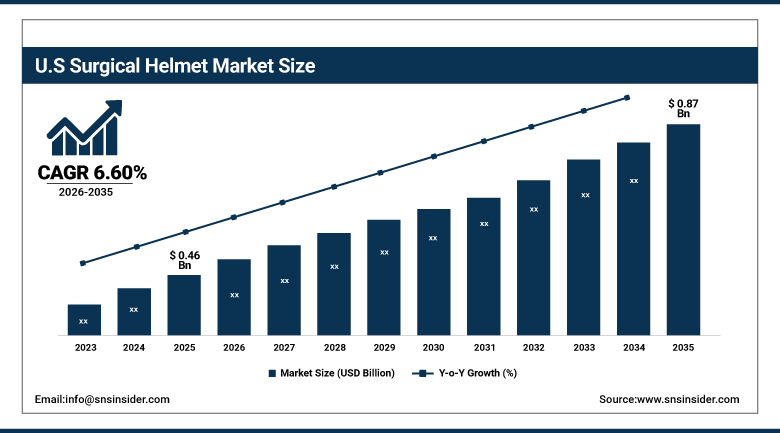
The U.S. Surgical Helmet Market was valued at USD 0.46 Billion in 2025 and is expected to reach USD 0.87 Billion by 2035, growing at a CAGR of 6.60% from 2026-2035.
The U.S. Surgical Helmet Market is characterized by advanced infrastructure of the healthcare industry, high volumes of surgeries, and growing consciousness regarding infection control and safety in the workplace among healthcare practitioners. Hospitals and ambulatory surgery centers in the country have been consistently emphasizing the use of personal protective equipment during orthopedic and neurosurgery procedures, while manufacturers of such devices located in the country have continued to offer fierce competition to each other in terms of comfort, vision, and noise. Standardizing on a single manufacturer for a full personal protection system has become a common practice among group purchasing organizations and value analysis committees of hospitals, resulting in high market concentration among a limited number of established vendors.
In 2025, Stryker described its Steri-Shield 8 personal protection system, launched in March, as the culmination of more than 30 years of continuous innovation in personal protection technology, with the company positioning itself as the personal protection system leader in the U.S. market.
Surgical Helmet Market Segment Analysis
-
By Product Type, the Complete Surgical Helmet Systems segment dominated the market with 51.65% share in 2025, while the Ventilated/Powered Surgical Helmets segment is fastest growing with a CAGR of 8.72% during 2026–2035.
-
By Application, the Orthopedic Surgery segment dominated the market with a 44.60% share in 2025, while the Neurosurgery segment is the fastest growing with a CAGR of 8.60% during 2026-2035.
-
By End Use, the Hospitals segment dominated the market with a 56.60% share in 2025, while the Ambulatory Surgical Centers segment is the fastest growing with a CAGR of 8.80% during 2026-2035.
-
By Distribution Channel, the Direct Sales segment dominated the market with a 54.60% share in 2025, while the Online segment is the fastest growing with a CAGR of 7.60% during 2026-2035.
By Product Type, Personal Protection Systems Dominates the Market and Helmet System Grows Fastest
Complete Surgical Helmet Systems remain dominant owing to the fact that they offer full body protection through head gear, protective barriers, ventilation, face shields, and even lights in some cases. These helmets are essential especially when it comes to orthopedic surgery, trauma, and surgeries where there is exposure to blood and other bodily fluids. Hospitals prefer to use complete systems as they offer standardized protection, but also help in controlling infections and adhering to occupational health standards.
Ventilated/Powered Surgical Helmets are expected to record strong growth as healthcare facilities increasingly prioritize surgeon comfort alongside infection protection during lengthy procedures. Integrated airflow systems help reduce heat accumulation, visor fogging, and discomfort, enabling clinicians to maintain concentration during extended operations. Product innovation involving lightweight construction, adjustable airflow, improved battery performance, ergonomic designs, and advanced filtration is also encouraging adoption. Demand is particularly supported by orthopedic and other high-risk procedures where enhanced protection is required. Growing awareness of occupational hazards and increasing adoption of advanced protective equipment further support segment expansion.
By Application, Orthopedic Surgery Dominates the Market and Neurosurgery Grows Fastest
Orthopedic surgery dominated the market in 2025. Approximately 15 million joint replacement procedures are performed globally each year, and these operations generate substantial bone debris and fluid splash that make powered personal protection systems a near-standard requirement. The sheer procedure volume, combined with the physically demanding, extended duration of many orthopedic cases, continues to anchor orthopedic surgery as the leading application for surgical helmets.
Neurosurgery is expected to be the fastest-growing application over the forecast period. An ageing population, projected to reach 2.1 billion people over the age of 60 by 2050, continues to expand demand for neurosurgical intervention, and these procedures similarly expose surgical staff to bodily fluids requiring comprehensive barrier protection. Rising neurosurgical case volumes are driving above-market growth for this application relative to the broader orthopedic-dominated market.
By End Use, Hospitals Dominates the Market and Ambulatory Surgical Centers Grows Fastest
Hospitals dominated the market in 2025. They perform the majority of complex orthopedic and neurosurgical procedures and maintain the capital budgets and sterile processing infrastructure required to support reusable personal protection systems across multiple operating rooms. This scale of surgical activity continues to sustain hospitals as the largest end-user category across the broader surgical helmet market.
Ambulatory surgical centers are projected to be the fastest-growing end-user category over the forecast period. The expansion of ambulatory surgical centers continues to shift a growing share of joint replacement and other orthopedic procedures toward outpatient settings, as these facilities offer lower costs and faster patient turnover. Rising specialisation in outpatient orthopedic surgery continues to drive above-market growth for this end-user category.
By Distribution Channel, Direct Sales Dominates the Market and Online Grows Fastest
Direct sales dominated the market in 2025. Manufacturers typically sell personal protection systems directly to hospitals and large surgical networks, supported by dedicated clinical education and fitting services that help ensure proper use and comfort. This close, consultative relationship continues to make direct sales the preferred channel for large-volume institutional purchasers.
Online distribution is projected to be the fastest-growing channel over the forecast period. Online channels are gaining increasing popularity, particularly among smaller clinics, individual practitioners, and healthcare facilities seeking greater convenience and a wider selection of consumable components such as replacement hoods and visors, supporting above-market growth for this distribution channel.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
North America |
United States |
88.60% |
|
Europe |
Germany |
27.60% |
|
Asia Pacific |
China |
38.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
North America Surgical Helmet Market Insights
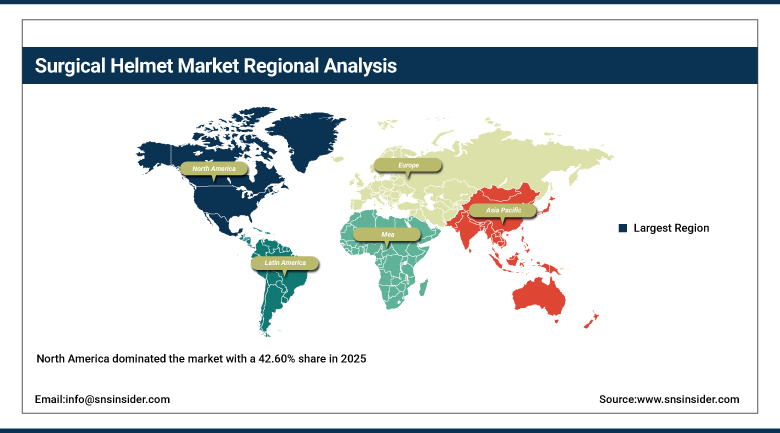
North America dominated the market with a 42.60% share in 2025. Advanced healthcare infrastructure, high surgical procedure volumes, and increasing adoption of technologically advanced surgical safety equipment across hospitals and ambulatory surgical centers continue to anchor this leadership position. The United States represents the largest contributor within the region, driven by rising awareness of infection prevention and occupational safety among healthcare professionals.
Canada contributes steady incremental demand as its own hospital and outpatient surgical infrastructure continues to expand. Continued investment in advanced personal protection system technology, combined with sustained joint replacement procedure growth, is expected to keep North America in the lead through the forecast period, even as growth in percentage terms trails faster-scaling Asia Pacific markets.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Surgical Helmet Market Insights
Asia Pacific is projected to be the fastest-growing region over the forecast period. Rapidly expanding hospital infrastructure, rising surgical procedure volumes, and growing healthcare expenditure continue to accelerate regional adoption of advanced surgical safety equipment. Increasing awareness of infection control standards among healthcare professionals is further reinforcing demand across the region.
China is the main driver of regional demand due to its rapidly increasing network of hospitals and increasing number of orthopedic surgeries performed annually. The Japan and South Korean markets add depth to the region in terms of already developed healthcare systems that are increasingly utilizing high-tech personal protection equipment. The Indian private hospitals are also adding incremental growth in the region.
Europe Surgical Helmet Market Insights
Europe holds a significant share of the global market, supported by mature healthcare systems and stringent occupational safety standards that have led to widespread adoption of surgical helmets, particularly in orthopedic and trauma surgery. Germany anchors regional demand through its substantial hospital sector and strong domestic medical device manufacturing base.
The United Kingdom, France, and Italy add consistent demand as national health systems continue to extend advanced personal protection system adoption across surgical departments. Continued regulatory emphasis on healthcare worker safety is expected to sustain steady growth across the broader European market through the forecast period.
MEA & Latin America Surgical Helmet Market Insights
The Middle East & Africa region is supported by growing healthcare infrastructure investment across the United Arab Emirates and Saudi Arabia, where regional governments continue to expand specialist surgical capacity and healthcare worker safety standards.
Latin America is anchored by Brazil, where a growing domestic healthcare sector sustains steady demand for surgical protection equipment. Mexico contributes further incremental growth as regional healthcare access continues to widen, though adoption of the most advanced personal protection systems across the broader region still lags more established global markets.
Market Dynamics
Growth Drivers: Rising Surgical Volumes and Infection Prevention Focus
Rising volumes of orthopedic and neurosurgical procedures stand as the primary growth driver. Approximately 15 million joint replacement surgeries are performed globally each year, and an ageing population, projected to reach 2.1 billion people over 60 by 2050, continues to expand demand for both orthopedic and neurosurgical intervention that requires comprehensive personal protection.
Heightened post-pandemic emphasis on personal protective equipment represents a second major driver, as healthcare facilities continue to prioritise infection prevention and occupational safety for surgical staff. Expansion of ambulatory surgical centers offering joint replacement and other procedures continues to broaden the customer base for surgical helmets beyond traditional hospital settings.
Restraints: High System Costs and Reprocessing Requirements
The high cost associated with having a total personal protection system is definitely a constraint, given that helmet systems with high levels of ventilation, visibility, and comfort are priced in a manner that makes it difficult for small institutions and markets to accommodate them within the capital equipment budget.
Re-processing and maintenance constraints associated with the reusability of such systems is another constraint, whereby the hospital needs to maintain the infrastructure and the know-how required to clean, check, and maintain the powered helmet system.
Opportunities: Comfort Innovation and Ambulatory Care Expansion
Continued innovation in comfort, weight, and noise reduction represents a substantial opportunity, as manufacturers that can deliver genuinely lighter, quieter, and more comfortable systems stand to capture demand from surgeons increasingly prioritising wearability alongside protection during physically demanding, extended procedures.
Continued expansion of ambulatory surgical center capacity for orthopedic procedures offers a further avenue for growth, as manufacturers that can supply cost-effective, easy-to-maintain systems suited to these smaller facilities are positioned to capture demand from a fast-growing customer segment beyond traditional hospital purchasing channels.
Recent Developments:
-
2025: Surgeons and hospital administrators publicly discussed the transition experience between competing personal protection systems, underscoring the importance of user trials and comfort validation before switching vendors for hospital-wide standardisation.
-
2024: Zimmer Biomet Holdings, Inc. continued expanding its surgical safety and personal protection equipment offerings to support orthopedic surgical teams.
-
2024: RevelAi Health and Zimmer Biomet Holdings, Inc. announced a collaboration relevant to the broader orthopedic surgical technology ecosystem that surgical helmet systems support.
Surgical Helmet Market Key Players are
-
3M Company
-
Medline Industries, LP
-
Kimberly-Clark Corporation
-
Alphatec Holdings, Inc.
-
Integra LifeSciences Holdings Corporation
-
De Soutter Medical Ltd.
-
Steris plc
-
CleanAir Systems, Inc.
-
AresAir
-
Kaiser Technology
-
Prodancy Pvt. Ltd.
-
Bio-Medical Devices International
-
Medisafe International Ltd.
-
Ecolab Inc.
-
Cardinal Health, Inc.
-
Owens & Minor, Inc.
-
Molnlycke Health Care AB
-
Ansell Limited
Surgical Helmet Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.22 Billion |
| Market Size by 2035 | USD 2.42 Billion |
| CAGR | CAGR of 7.09% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Complete Surgical Helmet Systems, Ventilated/Powered Surgical Helmets, Surgical Helmets with LED Lighting, Disposable Surgical Helmets, Others) • By Application (Orthopedic Surgery, Neurosurgery, Cardiovascular Surgery, General Surgery, Others) • By End Use (Hospitals, Specialty Clinics, Ambulatory Surgical Centers) • By Distribution Channel (Direct Sales, Distributors, Online) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Stryker Corporation, Zimmer Biomet Holdings, Inc., 3M Company, Medline Industries, LP, Kimberly-Clark Corporation, Alphatec Holdings, Inc., Integra LifeSciences Holdings Corporation, De Soutter Medical Ltd., Steris plc, CleanAir Systems, Inc., AresAir, Kaiser Technology, Prodancy Pvt. Ltd., Bio-Medical Devices International, Medisafe International Ltd., Ecolab Inc., Cardinal Health, Inc., Owens & Minor, Inc., Molnlycke Health Care AB, Ansell Limited |
Frequently Asked Questions
Key players include Stryker Corporation, Zimmer Biomet Holdings, Inc., 3M Company, Medline Industries, LP, and Kimberly-Clark Corporation, among other medical device and PPE manufacturers.
Continued innovation in comfort, weight, and noise reduction, and continued expansion of ambulatory surgical center capacity, represent the primary opportunities.
Growth is primarily driven by rising volumes of orthopedic and neurosurgical procedures, combined with heightened post-pandemic focus on infection prevention.
By Product Type, Personal Protection Systems dominated the market with a 47.60% share in 2025, reflecting hospital preference for complete, validated systems.
North America dominated the market with a 42.60% share in 2025, supported by advanced healthcare infrastructure and high surgical procedure volumes.
