
Aircraft Lighting Market Report Scope & Overview:
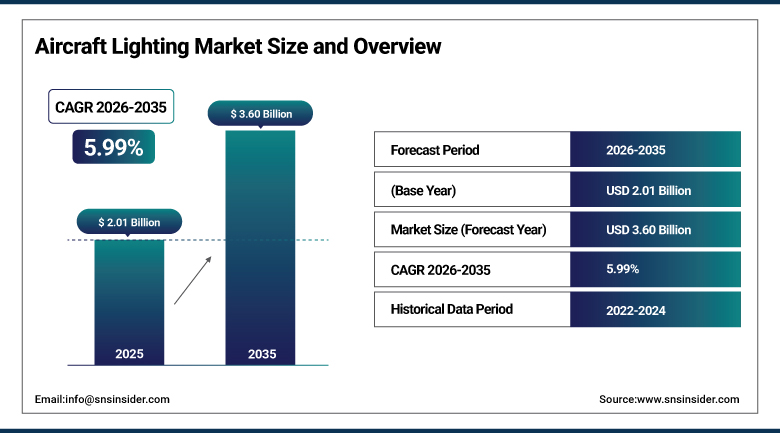
The Aircraft Lighting Market was valued at USD 2.01 Billion in 2025 and is expected to reach USD 3.60 Billion by 2035, growing at a CAGR of 5.99% from 2026-2035.
Aircraft lighting spans every illumination system aboard an aircraft, from interior reading and cabin ambience lighting through exterior navigation, anti-collision, and landing lights, to cockpit instrument and panel lighting that keeps flight crews informed under every operating condition. The industry has been moving decisively away from legacy incandescent, halogen, and fluorescent fixtures toward solid-state LED systems that cut weight, reduce power draw, and last dramatically longer between replacements, a shift that matters enormously to airlines chasing every possible fuel efficiency gain. Growth is supported by expanding commercial aircraft fleets, rising global air travel demand, and sustained retrofit and cabin modernization programs that continue to convert existing aircraft to LED lighting even as new aircraft increasingly ship with LED systems from the factory.
In 2025, Collins Aerospace introduced its Hypergamut cabin lighting technology into service. This was a new strategy of providing variable spectrum of aircraft lighting. This lighting system employs six LEDs with the inclusion of cyan light to produce a larger variety of colors and lighting than the conventional cabin lighting systems. This lighting system took seven years to develop. It is intended to improve the aircraft cabin ambience by providing greater flexibility and dynamics in terms of lighting. This innovation fits into the preference of airlines to have individualized passenger experience and mood lighting.
To Get more information Aircraft Lighting Market - Request Free Sample Report
Aircraft Lighting Market Trends
- Rising adoption of programmable, colour-changing ambient cabin lighting supporting circadian rhythm management.
- Growing retrofit demand as airlines convert legacy fluorescent and incandescent fixtures to LED systems.
- Expanding use of smart lighting panels enabling pre-programmed scenes synchronised with inflight entertainment.
- Increasing focus on weight reduction as airlines seek every available fuel efficiency improvement.
- Rising demand for NVIS-compatible cockpit and exterior lighting across military aircraft platforms.
- Growing distribution partnership activity supporting faster aftermarket lighting component availability.
U.S. Aircraft Lighting Market Overview
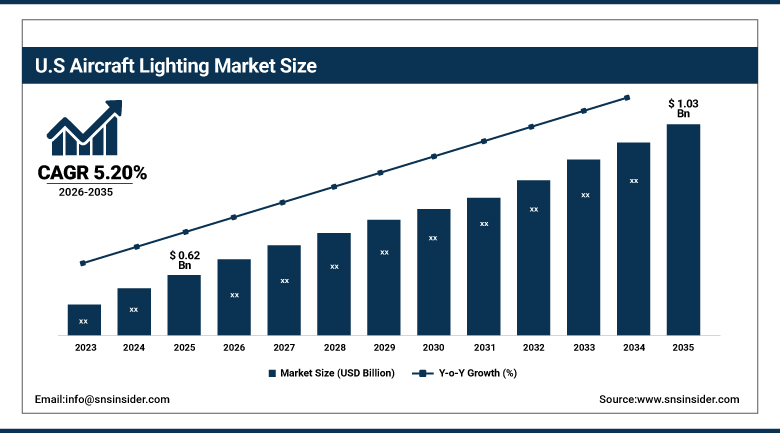
The U.S. Aircraft Lighting Market was valued at USD 0.62 Billion in 2025 and is expected to reach USD 1.03 Billion by 2035, growing at a CAGR of 5.20% from 2026-2035.
The U.S. Aircraft Lighting Market benefits from substantial commercial aircraft fleet, strong military aviation demand, and the presence of leading aerospace lighting suppliers headquartered in the country that continue to compete on innovation in solid-state, low-power lighting systems. Commercial transport demand continues to grow as airlines invest in cabin power, lighting, and safety upgrades, while military aircraft lighting demand has expanded meaningfully as defence programs prioritise NVIS-compatible and mission-critical lighting systems. Leading suppliers continue to report strong growth across their lighting and safety product lines, reflecting sustained airline demand for retrofit programs that convert older aircraft to modern LED systems without extensive structural rewiring. Continued growth in aviation and business jet demand broadens the addressable customer base for compact, lightweight lighting systems.
In 2025, U.S.-based Astronics Corporation achieved a total revenue of USD 797.3 million from its Aerospace segment, representing a 12.8% increase from the previous year. Sales of commercial transport reached USD 638.3 million, growing 14.2% due to high customer demand for power, lighting, safety, seat motion, and certification equipment. Sales for military aircraft stood at USD 116.3 million, reflecting 32.1% growth thanks to greater customer demand for lighting and safety equipment. This indicates a high U.S. demand for innovative aircraft lighting technology.
Aircraft Lighting Market Segment Analysis
- By Light Type, the LED segment dominated the Aircraft Lighting Market with a 52.60% share in 2025, while the LED segment is the fastest growing with a CAGR of 11.37% during 2026-2035.
- By Application, the Interior segment dominated the Aircraft Lighting Market with a 44.60% share in 2025, while the Exterior segment is the fastest growing with a CAGR of 8.60% during 2026-2035.
- By Aircraft Type, the Commercial segment dominated the Aircraft Lighting Market with a 51.60% share in 2025, while the Military segment is the fastest growing with a CAGR of 8.20% during 2026-2035.
- By End User, the OEM segment dominated the Aircraft Lighting Market with a 68.60% share in 2025, while the Aftermarket segment is the fastest growing with a CAGR of 8.40% during 2026-2035.
By Light Type, LED Dominates the Market and LED Grows Fastest
LED lighting dominated the market in 2025. Solid-state LED fixtures continue to displace legacy incandescent, halogen, and fluorescent lighting across virtually every aircraft system, offering dramatically lower power consumption, reduced weight, and far longer service life that directly supports airline fuel efficiency and maintenance cost goals, sustaining LED's position as the largest light type category.
LED lighting is also expected to grow fastest over the forecast period. Continued retrofit and cabin modernisation programs, combined with the fact that new aircraft increasingly ship with LED systems as standard equipment, continues to reinforce LED's already dominant position even further relative to legacy fluorescent, halogen, and HID lighting technologies still found in older aircraft.
By Application, Interior Dominates the Market and Exterior Grows Fastest
Interior lighting dominated the market in 2025. Cabin reading lights, ambient mood lighting, and general illumination continue to represent the largest and most visible lighting category to passengers, and airlines' growing focus on cabin customisation and passenger experience continues to sustain substantial investment in this application category.
Exterior lighting is projected to be the fastest-growing application over the forecast period. Growing demand for purpose-built exterior lighting, including those with greater visibility and safety-related components, will continue to be spurred by regulation favoring all-season visibility and accident prevention, thereby guaranteeing future above-average performance for exterior lighting against the backdrop of the interior-oriented product mix.
By Aircraft Type, Commercial Dominates the Market and Military Grows Fastest
Commercial aircraft dominated the market in 2025. The sheer scale of the global commercial fleet, combined with sustained new aircraft delivery volumes and extensive retrofit activity across in-service fleets, continues to anchor commercial aircraft as the largest aircraft type category across the broader aircraft lighting market.
Military aircraft are projected to be the fastest-growing aircraft type over the forecast period. Rising defence modernisation spending, combined with growing demand for NVIS-compatible and mission-critical lighting systems across next-generation military platforms, continues to drive above-market growth for this aircraft type relative to the broader commercial-dominated aircraft type mix.
By End User, OEM Dominates the Market and Aftermarket Grows Fastest
OEM installation dominated the market in 2025. Aircraft manufacturers continue to specify lighting systems directly into new aircraft during original design and manufacturing, and sustained new aircraft delivery volumes across both commercial and military segments continue to anchor OEM installation as the largest end-user category.
The aftermarket is projected to be the fastest-growing end-user category over the forecast period. Airlines' continued conversion of legacy fixtures to LED systems, supported by retrofit solutions requiring minimal ground time and no structural rewiring, continues to drive sustained above-market growth for aftermarket lighting relative to the broader OEM-dominated end-user mix.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
North America |
United States |
84.60% |
|
Europe |
France |
27.60% |
|
Asia Pacific |
China |
38.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
North America Aircraft Lighting Market Insights
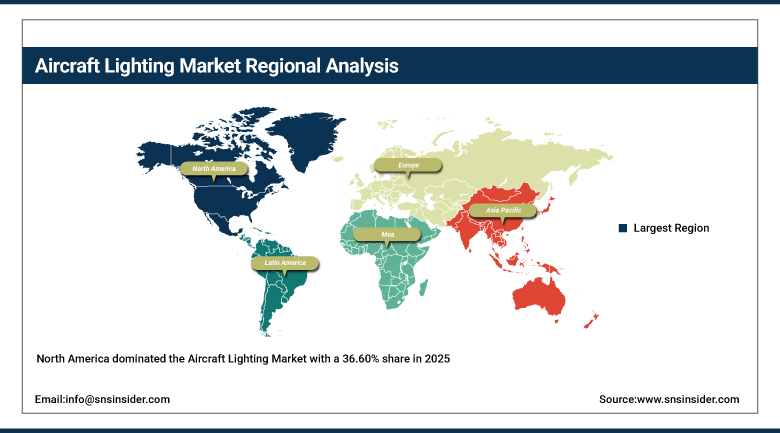
North America dominated the Aircraft Lighting Market with a 36.60% share in 2025, supported by its substantial commercial and military aircraft fleet, established aerospace manufacturing ecosystem, and presence of leading aircraft lighting suppliers. The United States represents the largest contributor, supported by extensive airline operations, defense aviation programs, aircraft production, and a mature aftermarket serving cabin, cockpit, exterior, and safety lighting applications.
Another addition of regional demand comes from Canada, owing to the presence of the aerospace industry and MRO (maintenance, repair, and overhaul) facilities in Canada. Fleet upgrades, cabin refurbishments, cabin lighting retrofits, and upgrading aging lighting systems have been driving steady regional demand. Growing adoption of LED lighting, programmable cabin lighting, and lighting controls is creating greater opportunities for the market. The region is anticipated to hold the leading market position in the forecast period.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Aircraft Lighting Market Insights
Asia Pacific is projected to be the fastest-growing region in the Aircraft Lighting Market, registering a CAGR of approximately 11.63% over the forecast period. Rapid expansion of commercial aircraft fleets, rising passenger air travel, increasing aircraft deliveries, and strengthening regional aerospace manufacturing capabilities are accelerating adoption of advanced lighting technologies. China anchors regional demand through its expanding commercial aviation sector, large airline fleet, and growing domestic aircraft manufacturing capabilities.
India represents another key growth area in terms of expansion of airlines’ fleet size, airport facilities, and growing traffic levels. Japan and South Korea add value to the region with their well-developed aircraft manufacture, efficient supply chain, and investment in modernization of aircrafts. Increasing use of LEDs for cabin lighting and energy-efficient lighting system in addition to programmable illumination and retrofits should be mentioned as factors enhancing market demand in Asia Pacific.
Europe Aircraft Lighting Market Insights
Europe holds a significant share of the global Aircraft Lighting Market, anchored by France's substantial aerospace manufacturing base and its central role in commercial aircraft production. The region's advanced aerospace engineering capabilities, established supplier networks, and large installed aircraft base sustain demand for interior, exterior, cockpit, and emergency lighting systems. Germany contributes through its strong aircraft manufacturing, component production, and engineering ecosystem, while the United Kingdom supports regional demand through established aerospace companies and maintenance capabilities.
Other European markets, including Spain and Italy, add further demand through aircraft production, airline operations, and MRO activities. Continued investment in cabin refurbishment, fleet modernization, energy-efficient LED systems, and advanced lighting controls is expected to support steady development of the European aircraft lighting market throughout the forecast period.
MEA & Latin America Aircraft Lighting Market Insights
The Middle East & Africa region is supported by expanding commercial aviation fleets, rising passenger traffic, and growing investment in premium cabin experiences across the United Arab Emirates and Saudi Arabia. Major regional airlines continue upgrading aircraft interiors with advanced ambient, mood, and energy-efficient lighting systems to enhance passenger comfort and cabin differentiation.
The region of Latin America comprises Brazil, which relies on its existing capabilities in aerospace manufacturing industry, fleet operations of the airlines, as well as maintenance to ensure continuous demand for aviation lighting equipment in the region. Mexico adds to the growth of the regional market owing to the presence of its own aerospace manufacturing industry and strong links within the North American aerospace supply chain.
Market Dynamics
Growth Drivers: Fleet Expansion and LED Retrofit Demand
Rising aircraft production and fleet expansion represent key growth drivers for the Aircraft Lighting Market, as increasing commercial air travel demand supports higher aircraft delivery volumes worldwide. Each new aircraft requires integrated interior, exterior, cockpit, emergency, and navigation lighting systems, creating sustained OEM demand. Growing aircraft retrofit and cabin modernization programs provide another significant growth opportunity, as airlines replace legacy fluorescent and incandescent fixtures with lightweight, energy-efficient LED technologies.
The retrofit segment will find additional momentum from the aging aircraft fleet and increased maintenance needs along with passenger demands for state-of-the-art cabins. The continual improvement in smart lighting, programmable illumination, adaptive controls, and LED-based systems will boost the demand for them. This segment will benefit greatly because of their ability to enhance energy efficiency, improve comfort levels of passengers, and increase design flexibility.
Restraints: Certification Complexity and High Development Costs
The rigorous demands of aviation certification definitely represent an actual constraint because new lighting systems have to pass through a long process of testing and certification, which not only increases the development period but also the cost of production compared with similar technology used in other areas.
High development and qualification costs present a further restraint, as advanced lighting systems incorporating smart controls and programmable colour capability continue to require substantial engineering investment, a cost profile that can challenge smaller suppliers competing against established aerospace lighting specialists with deeper research budgets.
Opportunities: Smart Lighting Integration and Retrofit Program Expansion
The further integration of advanced and programmable lighting systems offers an excellent chance for the Aircraft Lighting Market because of the growing demand from airlines to have distinct cabin interiors that ensure comfort and support luxury travel experience. Lighting technologies integrated into the inflight entertainment system, catering services, boarding process, and sleep cycles may offer a more personal cabin environment. Retrofitting offers yet another significant chance of market growth since airlines need to update their aging fleet without making any structural changes.
Suppliers who provide solutions for lightweight LED conversions, simple installation procedures, and reduced aircraft down time will be able to meet the increasing demands for efficient cabin modifications. Systems that will minimize the need for rewiring, installation complexity, and maintenance down time can make retrofitting even more economically feasible for airlines. The aging of fleets and continuing cabin renovation programs will thus ensure continued demand for such lighting systems.
Recent Developments:
- 2026: Safran S.A. expanded its aerospace technology activities across cabin systems and aircraft interiors, supporting next-generation aircraft programs and technologies for improved passenger experience and operational efficiency.
- 2026: Diehl Aerospace GmbH received Embraer’s Best Suppliers Award in the Interiors category, recognizing its cabin systems and integrated interior and aircraft-lighting solutions.
- 2026: Heads Up Technologies, Inc. continued its aircraft cabin-lighting portfolio through its broader group capabilities, providing lighting, switches, and cabin-management solutions for business aviation applications.
Aircraft Lighting Market Key Players are:
- Honeywell International Inc.
- Collins Aerospace (RTX)
- Safran S.A.
- Astronics Corporation
- STG Aerospace Ltd.
- Diehl Aerospace GmbH
- Heads Up Technologies, Inc. (Astronics)
- Luminator Technology Group
- Aveo Engineering Group s.r.o.
- Oxley Group Ltd.
- CMC Electronics Inc.
- Whelen Engineering Company, Inc.
- Leviton Manufacturing Co., Inc.
- Devtron Inc.
- Spectrolab, Inc. (Boeing)
- Bruce Aerospace Inc.
- Sicame Group
- STELIA Aerospace
- Bombardier Inc.
- Textron Aviation Inc.
Aircraft Lighting Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.01 Billion |
| Market Size by 2035 | USD 3.60 Billion |
| CAGR | CAGR of 5.99% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Light Type (LED, HID, Halogen, Fluorescent, Others) • By Application (Interior, Exterior, Cockpit) • By Aircraft Type (Commercial, Military, General Aviation, Others) • By End User (OEM, Aftermarket) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Honeywell International Inc., Collins Aerospace (RTX), Safran S.A., Astronics Corporation, STG Aerospace Ltd., Diehl Aerospace GmbH, Heads Up Technologies, Inc. (Astronics), Luminator Technology Group, Aveo Engineering Group s.r.o., Oxley Group Ltd., CMC Electronics Inc., Whelen Engineering Company, Inc., Leviton Manufacturing Co., Inc., Devtron Inc., Spectrolab, Inc. (Boeing), Bruce Aerospace Inc., Sicame Group, STELIA Aerospace, Bombardier Inc., Textron Aviation Inc. |
Frequently Asked Questions
Key players include Honeywell International Inc., Collins Aerospace, Safran S.A., Astronics Corporation, and STG Aerospace Ltd., among other aerospace lighting suppliers.
Continued integration of smart, programmable lighting systems and continued expansion of retrofit programs represent the primary opportunities for suppliers.
Growth is primarily driven by rising aircraft production and fleet expansion, combined with growing aircraft retrofit and cabin modernisation programs.
By Light Type, LED dominated the market with a 52.60% share in 2025, reflecting its lower power consumption, reduced weight, and longer service life.
North America dominated the market with a 36.60% share in 2025, supported by a substantial commercial and military aircraft fleet and leading aerospace lighting suppliers.
