
Helicopters Market Report Scope & Overview:
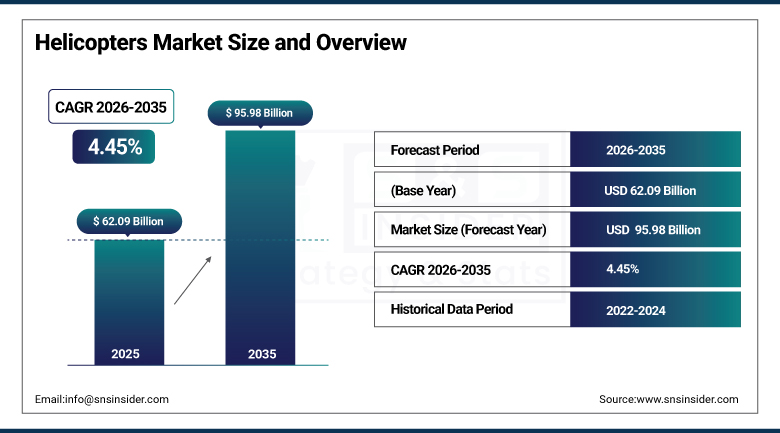
The Helicopters Market was valued at USD 62.09 Billion in 2025 and is expected to reach USD 95.98 Billion by 2035, growing at a CAGR of 4.45% from 2026-2035.
Helicopters remain one of the few aircraft types capable of vertical takeoff, hover, and precision manoeuvring in confined spaces, capabilities that make them indispensable across military operations, emergency medical services, offshore oil and gas transport, law enforcement, and corporate and VIP travel. The market spans from light single-engine training and personal-use helicopters to heavy-lift military and offshore transport platforms. Growth is supported by rising global military and defence spending that continues to fund next-generation attack, transport, and utility helicopter programs, sustained demand for emergency medical services and search-and-rescue capability, and continued fleet renewal as ageing civil and commercial helicopters reach the end of their service life. Advancements in urban air mobility and growing commercial helicopter operations continue to widen the category's addressable market.
In September 2025, Sikorsky, a Lockheed Martin company, received a nearly USD 10.8 billion contract from the U.S. Navy to produce up to 99 CH-53K King Stallion heavy-lift helicopters for the U.S. Marine Corps over five years. The agreement combines five separate aircraft orders into a multi-year procurement program intended to improve long-term affordability and production efficiency. The contract also provides greater visibility for Sikorsky’s manufacturing operations, supporting supply-chain stability and workforce planning while advancing the Marine Corps’ heavy-lift helicopter modernization requirements.
To Get more information On Helicopters Market - Request Free Sample Report
Helicopters Market Trends
- Rising global military and defence spending funding next-generation attack and transport helicopter programs.
- Growing tiltrotor development extending vertical-lift capability with fixed-wing-like speed and range.
- Expanding commercial helicopter demand for offshore energy transport, tourism, and corporate travel.
- Increasing fleet renewal activity as ageing civil and commercial helicopters reach end of service life.
- Rising emergency medical services and search-and-rescue demand supporting sustained civil helicopter orders.
- Growing international competition for major national medium-lift and utility helicopter procurement programs.
U.S. Helicopters Market Overview
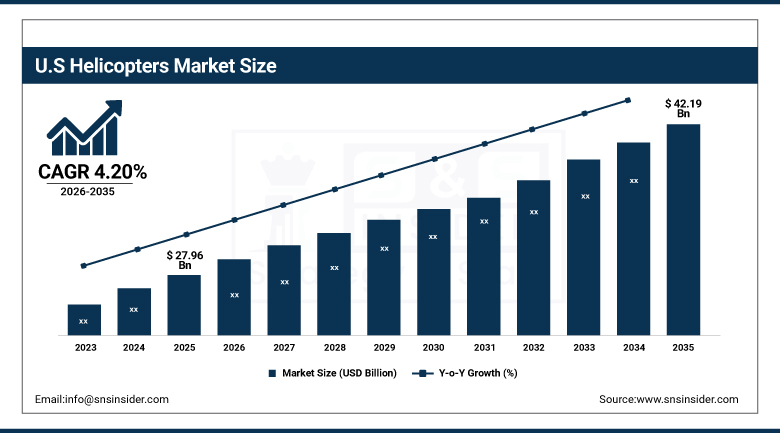
The U.S. Helicopters Market was valued at USD 27.96 Billion in 2025 and is expected to reach USD 42.19 Billion by 2035, growing at a CAGR of 4.20% from 2026-2035.
The U.S. Helicopters Market benefits from sustained defence spending supporting multiple concurrent military helicopter programs, a substantial and ageing civil and commercial fleet requiring ongoing renewal, and the presence of leading manufacturers headquartered in the country that continue to compete for major national and international procurement contracts. The U.S. Army's next-generation tiltrotor program continues to advance toward full-rate production, representing one of the most significant military rotorcraft investments underway anywhere in the world, while established manufacturers continue securing substantial orders for legacy platforms supporting ongoing military sustainment requirements. Commercial helicopter demand continues to be supported by steady emergency medical services, offshore transportation, and corporate aviation activity. Continued military modernisation spending and sustained civil fleet replacement activity are expected to support steady demand growth throughout the country through the forecast period.
In the fiscal year 2025 results, U.S.-based Textron reported that Bell’s military aircraft and support program revenues increased 28%, driven primarily by higher volume on the MV-75 tiltrotor program for the U.S. Army. Bell also received a USD 1.3 billion award for prototype testing and evaluation, supporting development of the next-generation military aircraft. The program strengthens U.S. defense aviation capabilities while sustaining domestic aerospace manufacturing and engineering activity. Bell delivered 169 commercial helicopters during 2025, further supporting the company’s U.S. helicopter operations and broader global customer base.
Helicopters Market Segment Analysis
- By Type, the Military segment dominated the market with a 59.60% share in 2025, while the Military segment is the fastest growing with a CAGR of 5.60% during 2026-2035.
- By Weight Class, the medium segment dominated the market with a proposed 36.40% share in 2025, while the Heavy-Lift segment is the fastest-growing with an estimated CAGR of 5.60% during 2026–2035.
- By Application, the Military & Defense segment dominated the market with a 54.60% share in 2025, while the Emergency Medical Services segment is the fastest growing with a CAGR of 5.80% during 2026-2035.
- By Number of Engines, the Twin Engine segment dominated the market with a 64.60% share in 2025, while the Single Engine segment is the fastest growing with a CAGR of 4.80% during 2026-2035.
- By End User, the Government & Defense Agencies segment dominated the market with a 59.60% share in 2025, while the Commercial Operators segment is the fastest growing with a CAGR of 5.60% during 2026-2035.
By Type, Military Dominates the Market and Military Grows Fastest
Military helicopters dominated the Helicopters Market in 2025 on the strength of consistent spending and purchases in both traditional and new military powers. The need for attack, transport, and utility helicopters will continue to boost revenues, while the significant costs associated with acquiring and operating such helicopters add to their significant market value. Modernization and readiness, coupled with spending on military aircraft, help consolidate their dominance over civil/commercial helicopters.
The military helicopter segment is anticipated to witness fastest growth due to increased defense budget and higher procurement demands. The development and acquisition of advanced aircrafts, including tilt rotor aircrafts, along with replacement programs for heavy lift will generate extra demand in military aviation. The modernization of aging fleet and operational requirements will fuel demand and ensure the future growth of the segment up to 2035.
By Weight Class, Medium Helicopters Dominates the Market and Heavy-Lift Helicopters Grows Fastest
The Medium category is forecast to be the dominant part of the Helicopters Market in 2025 due to their adaptability to various military, commercial and governmental uses. The helicopters combine the benefits of payload capabilities, range, operating costs, and flexibility, therefore can be used in transportation of troops, offshore services, utility roles, search and rescue, and emergency situations. Being flexible in performing various operations and having lower operating costs compared to the larger helicopters, they can satisfy the growing purchasing demands. Modernization and multi-role use will ensure further significant contribution to the world market.
The Heavy-Lift segment is estimated to register the fastest growth in the Helicopters Market during 2026–2035, supported by demand for aircraft capable of transporting oversized equipment, substantial cargo loads, and personnel in challenging operating environments. Military logistics, disaster relief, infrastructure development, and remote industrial operations create requirements for high-payload rotary-wing platforms. Their ability to transport equipment where ground access is limited supports specialized procurement. Modernization of defense logistics and increasing use in complex lifting missions may further encourage investment. However, high acquisition and operating costs can constrain adoption among some commercial and government operators.
By Application, Military & Defense Dominates the Market and Emergency Medical Services Grows Fastest
Military and defence applications dominated the market in 2025. Surveillance, combat, transport, and logistics missions continue to represent the largest and most consistent source of helicopter demand worldwide, reinforced by sustained government procurement budgets that civil and commercial applications simply cannot match in scale.
Emergency medical services are projected to be the fastest-growing application over the forecast period. Growing investment in air ambulance networks and rising demand for rapid patient transport across both urban and rural regions continues to drive sustained above-market growth for this application relative to the broader military-dominated application mix.
By Number of Engines, Twin Engine Dominates the Market and Single Engine Grows Fastest
Twin-engine helicopters dominated the market in 2025. The redundancy and safety margin twin-engine configurations provide continues to make them the preferred choice for military, offshore, and emergency medical service operations, where the consequences of a single-engine failure can be severe, sustaining twin-engine helicopters' position as the largest category by number of engines.
Single-engine helicopters are projected to be the fastest-growing category over the forecast period. Lower acquisition and operating costs continue to make single-engine platforms attractive for training, personal use, and light utility applications, positioning this category for sustained above-market growth relative to the broader twin-engine-dominated segment.
By End User, Government & Defense Agencies Dominates the Market and Commercial Operators Grows Fastest
Government and defence agencies dominated the market in 2025. Military services, law enforcement agencies, and other government bodies continue to represent the largest single source of helicopter procurement spending worldwide, reflecting the scale and consistency of defence and public safety budgets relative to private commercial demand.
Commercial operators are projected to be the fastest-growing end-user category over the forecast period. Rising demand for offshore energy transport, corporate aviation, tourism, and emergency medical services continues to expand commercial operator fleets, positioning this end-user category for sustained above-market growth relative to the broader government-dominated end-user mix.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
North America |
United States |
85.60% |
|
Europe |
France |
27.60% |
|
Asia Pacific |
China |
38.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
North America Helicopters Market Insights
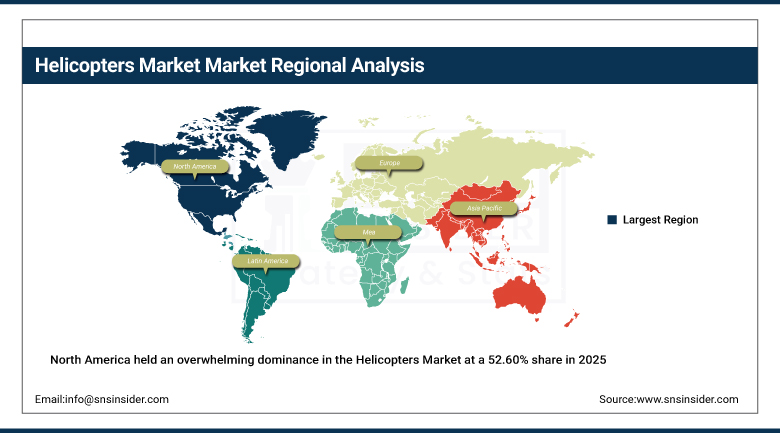
North America held an overwhelming dominance in the Helicopters Market at a 52.60% share in 2025, owing to the high expenditure on military and defense, strong civil and commercial helicopters fleet, and the existence of prominent helicopter makers in the region. The United States holds the major market due to military procurement, aerospace prowess, and vast commercial operations. This aids in fulfilling the demands for helicopters in several sectors such as military, emergency services, offshore, law enforcement, and others.
The involvement of Canada in the regional demand includes its use of military and commercial helicopters for transportation, emergencies, and business purposes. Continued investment in emergency medical services, fleet modernization, and aircraft technologies will help develop the market within the region. The rising demand for urban air mobility and commercial helicopter operations can lead to more opportunities in the future, along with existing suppliers and service centers maintaining the regional demand. North America is likely to continue being a large market share during the forecast period.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Helicopters Market Insights
Asia Pacific is projected to be the fastest-growing region in the Helicopters Market, registering a CAGR of approximately 4.44% over the forecast period, supported by rapid urbanization, infrastructure development, and increasing investments across civil and defense aviation. Expanding helicopter applications in emergency medical services, transportation, offshore operations, utility activities, and military missions are supporting regional demand. The growth of China is ensured by developing its domestic capabilities to produce helicopters and implementing further military modernization programs.
The role of Japan and South Korea will be played by their established defense aviation industry, commercial use of helicopters, and high development of the aerospace industry. India is another important factor ensuring growth due to growing defense budgets, fleet modernization, and development of civil aviation facilities. All these factors are going to make Asia Pacific an important growth market until 2035.
Europe Helicopters Market Insights
Europe holds a significant share of the global market, anchored by France's substantial helicopter manufacturing base and home to one of the world's leading civil and military helicopter producers. The region's deep aerospace engineering expertise continues to sustain steady demand across military, commercial, and emergency service applications.
Germany, Italy, and the United Kingdom add consistent regional demand as national defence ministries continue major helicopter procurement programs, including recent medium-lift helicopter competitions. Continued regional investment in fleet modernisation is expected to sustain steady growth across the broader European market.
MEA & Latin America Helicopters Market Insights
The Middle East & Africa region is supported by growing defence spending and commercial aviation investment across the United Arab Emirates and Saudi Arabia, where regional governments continue to expand both military and civil helicopter fleets as part of broader defence modernisation strategies.
Latin America is anchored by Brazil, where a substantial domestic aerospace manufacturing sector sustains steady demand for both military and commercial helicopters. Mexico contributes further incremental growth given its integration into broader regional aerospace and defence procurement activity.
Market Dynamics
Growth Drivers: Defence Spending and Emergency Medical Services Demand
Growth in military and defense spending is one of the key factors driving the Helicopter Market, as increased spending will boost the demand for helicopters which are used for purposes such as surveillance, combat, transportation of troops, and logistics operations. Increased military and defense budgets fuel the development of new helicopter fleets.
Growing demand for emergency medical services provides another significant driver, as governments and private operators expand air ambulance networks to strengthen rapid patient transportation. Meanwhile, urban air mobility initiatives and expanding commercial helicopter applications in tourism, corporate transportation, and offshore energy operations are further supporting sustained market demand globally.
Restraints: High Acquisition Costs and Long Procurement Cycles
High acquisition and operating costs remain a genuine restraint, as helicopters continue to command substantial upfront investment and ongoing maintenance expense relative to fixed-wing alternatives, a cost profile that can limit adoption among smaller commercial operators and budget-constrained government agencies.
Long procurement cycles present a further restraint, as major military helicopter programs often span years from initial requirement definition through contract award and delivery, a timeline that can delay fleet modernisation and expose programs to cost escalation and shifting strategic priorities over the course of development.
Opportunities: Tiltrotor Technology and Fleet Modernisation Programs
The further development of the tiltrotor technology could bring huge opportunities to the Helicopters Market, as companies that are able to combine the vertical lift capability with increased speed and range will be able to meet the new military demands. The increasing demand for the new generation of vertical lift capabilities drives investment in innovative technologies.
Fleet modernization and replacement programs provide another important opportunity, as aging civil, commercial, and military helicopter fleets require upgraded platforms. Manufacturers offering modern, cost-efficient, mission-flexible helicopters can benefit from multi-year procurement programs across established and emerging markets. Increasing requirements for improved payload capacity, reliability, and operational efficiency are further supporting long-term replacement demand and technology-driven fleet upgrades worldwide.
Recent Developments:
- 2026: Leonardo's AW149 was selected to fulfil the United Kingdom Ministry of Defence's New Medium Helicopter requirement, with the company set to deliver 23 aircraft and four training simulators to replace the Royal Air Force's Westland Puma fleet.
- 2026: The Boeing Company integrated the Active Parallel Actuator System (APAS) into the CH-47F Chinook production line, adding advanced flight-control functions that reduce pilot workload and improve maneuvering.
- 2026: Russian Helicopters JSC announced plans to begin serial deliveries of the domestically configured Mi-171A3 offshore helicopter, following completion of certification testing for operations over open water.
Helicopters Market Key Players are:
- Airbus Helicopters SAS
- The Boeing Company
- Lockheed Martin Corporation (Sikorsky)
- Leonardo S.p.A.
- Textron Inc. (Bell)
- Russian Helicopters JSC
- Robinson Helicopter Company
- MD Helicopters, Inc.
- Kaman Aerospace Corporation
- Enstrom Helicopter Corporation
- Hindustan Aeronautics Limited
- AVIC Helicopter
- Kawasaki Heavy Industries, Ltd.
- Korea Aerospace Industries, Ltd.
- Guimbal Helicopters
- Marenco Swisshelicopter AG
- Honeywell International Inc.
- GE Aerospace
- Safran S.A.
- Rolls-Royce Holdings plc
Helicopters Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 62.09 Billion |
| Market Size by 2035 | USD 95.98 Billion |
| CAGR | CAGR of 4.45% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Military, Civil & Commercial) • By Weight Class (Light, Intermediate, Medium, Heavy-Lift, Others) • By Application (Military & Defense, Emergency Medical Services, Oil & Gas, Law Enforcement, Search & Rescue, Corporate & VIP Transport, Tourism & Leisure, Others) • By Number of Engines (Single Engine, Twin Engine, Multi Engine) • By End User (Government & Defense Agencies, Commercial Operators, Private Owners, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Airbus Helicopters SAS, The Boeing Company, Lockheed Martin Corporation (Sikorsky), Leonardo S.p.A., Textron Inc. (Bell), Russian Helicopters JSC, Robinson Helicopter Company, MD Helicopters, Inc., Kaman Aerospace Corporation, Enstrom Helicopter Corporation, Hindustan Aeronautics Limited, AVIC Helicopter, Kawasaki Heavy Industries, Ltd., Korea Aerospace Industries, Ltd., Guimbal Helicopters, Marenco Swisshelicopter AG, Honeywell International Inc., GE Aerospace, Safran S.A., Rolls-Royce Holdings plc. |
Frequently Asked Questions
Key players include Airbus Helicopters SAS, The Boeing Company, Lockheed Martin Corporation, Leonardo S.p.A., and Textron Inc., among other aerospace manufacturers.
Continued development of tiltrotor technology and continued fleet modernization and replacement programs represent the primary opportunities for manufacturers.
Growth is primarily driven by increasing military and defence expenditures, combined with growing emergency medical services demand.
By Type, Military helicopters dominated the market with a 59.60% share in 2025, reflecting sustained global defence spending on attack, transport, and utility programs.
North America dominated the market with a 52.60% share in 2025, supported by sustained military spending and a substantial civil and commercial fleet.
