
Aircraft Seals Market Report Scope & Overview:
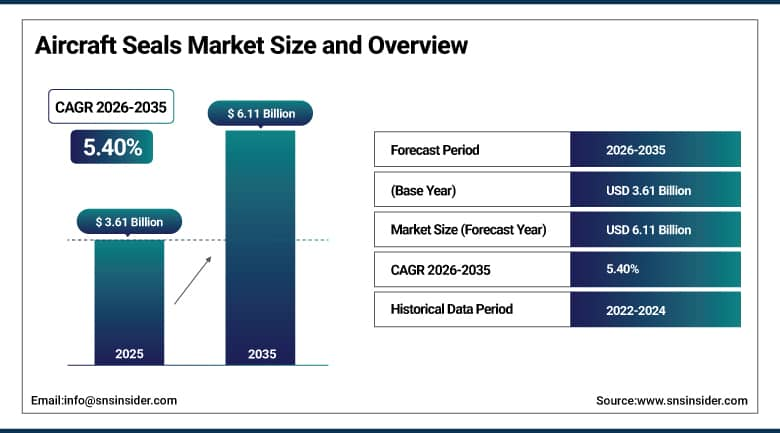
The Aircraft Seals Market was valued at USD 3.61 Billion in 2025 and is expected to reach USD 6.11 Billion by 2035, growing at a CAGR of 5.40% from 2026-2035.
The development of the Aircraft Seals Market is largely attributed to the steady growth in production of commercial and military aircraft, which contributes to growing demand for sealing systems from various aircraft parts including engines, airframe, landing gear, as well as flight control and hydraulic systems. Sealing systems are crucial for maintenance of the pressure of the aircraft structure and prevention of fluid leakages; moreover, relatively short lifetime of the systems as compared to airframe creates steady replacement pattern, supporting the need for original equipment, as well as after-sales products for the entire aircraft lifecycle. Growing maintenance, repair and overhaul services industry worldwide contribute to the growing demand for the products as aircraft are aging, gaining more flight hours and require constant replacement of seals. The steady growth in high-temperature polymer and spring-energized PTFE sealing technology opens up new possibilities of using sealing systems in more demanding conditions, ensuring the growing market in the future years.
In 2024, Freudenberg Sealing Technologies invested EUR 604.4 million in research and development, expanding its aerospace and battery seals manufacturing facilities in Germany and Costa Rica to cross-pollinate material science expertise between the aerospace and energy storage sectors.
Aircraft Seals Market Trends:
-
Growing adoption of spring-energized PTFE and high-temperature polymer sealing technology for demanding applications.
-
Rising use of fluorosilicone and advanced elastomer materials for improved chemical and temperature resistance.
-
Increasing demand for battery and hydrogen-resistant seals supporting electric and hybrid propulsion development.
-
Expanding unmanned aerial vehicle production creating new demand for compact, lightweight sealing solutions.
-
Continued industry consolidation as leading suppliers acquire complementary materials and manufacturing capabilities.
To Get More Information On Aircraft Seals Market - Request Free Sample Report
U.S. Aircraft Seals Market Outlook:
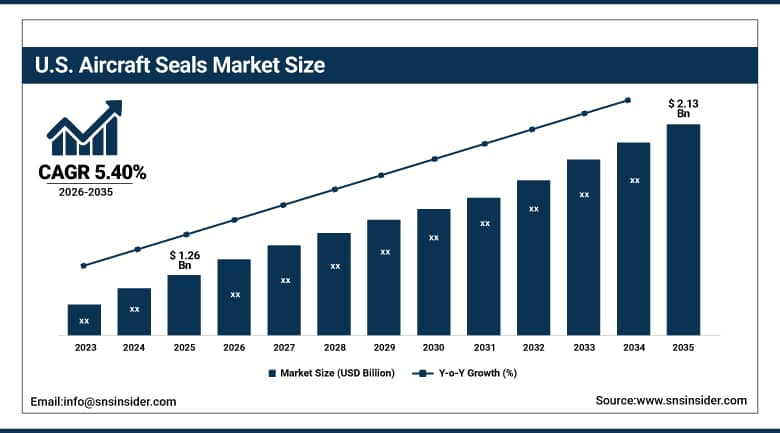
The U.S. Aircraft Seals Market was valued at USD 1.26 Billion in 2025 and is expected to reach USD 2.13 Billion by 2035, growing at a CAGR of 5.40% from 2026-2035.
The growth of the U.S. Aircraft Seals Market is being driven further by the consistent manufacturing of commercial and military aircraft, along with a robust network of maintenance, repair, and overhaul facilities that enable the biggest fleet of commercial aircraft in the world, along with the prevalence of leading manufacturers of sealing technologies and materials in the country. Demand is additionally helped by the ongoing spending on the modernization of the country’s defenses which involves unique high temperature and radar absorbing seals for their advanced military aircraft.
In January 2025, Parker Hannifin launched new BRE-FKM compound seals under product designations VP306-80 and VP316-90, offering enhanced chemical resistance and extended temperature flexibility for demanding aerospace sealing applications. The launch reflects continued domestic investment in advanced elastomer chemistry as leading U.S.-based sealing technology suppliers work to meet increasingly stringent performance requirements across engine, hydraulic, and fuel system applications spanning both commercial and military aircraft platforms.
Aircraft Seals Market Segment Analysis:
-
By Type, the Dynamic Seals segment dominated the Aircraft Seals Market with approximately 65.72% share in 2025, while the Static Seals segment is the fastest growing with a CAGR of approximately 6.12%.
-
By Application, the Engine Systems segment dominated the Aircraft Seals Market with approximately 46.10% share in 2025, while the Environmental Control & Fuel Systems segment is the fastest growing with a CAGR of approximately 6.78%.
-
By Material, the PTFE & Composite segment dominated the Aircraft Seals Market with approximately 36.22% share in 2025, while the Fluorosilicone segment is the fastest growing with a CAGR of approximately 7.01%.
-
By Aircraft Type, the Fixed-Wing segment dominated the Aircraft Seals Market with approximately 68.50% share in 2025, while the UAV segment is the fastest growing with a CAGR of approximately 8.56%.
By Type, Dynamic Seals dominates and Static Seals grows fastest
The Dynamic Seals segment will continue to be the leading segment in the Aircraft Seals Market on account of its indispensable nature for providing seal solutions to actuator, landing gear strut, and shaft interfaces where constant mechanical loading takes place during flights. The Dynamic Seals segment is bolstered by an increase in flight cycles and harsh conditions that cause faster wear in the moving parts and thereby generate a consistent replacement demand both in terms of OEM and aftermarkets. The constant improvement in spring-energized PTFE and PEEK seals adds further impetus to the dominance of this segment in the market through enhanced performance and cost-effectiveness in rod, piston, and shaft sealing applications.
Static seals have emerged as one of the fastest-growing segments in the Aircraft Seals Market owing to increasing requirements for leak-tight sealing solutions in various doors, windows, and nacelles that require better pressure integrity to improve fuel efficiency in aircrafts. Low-compression-set, low-friction seals are used in static seals where long linear runs and regular replacement is required. Commercial aircraft deliveries and airline plans for regular refurbishment of the cabin increase the demand for static seals in the aircraft seal market.
By Application, Engine Systems dominates and Environmental Control & Fuel Systems grows fastest
The Engine Systems account for the majority share of the Aircraft Seals market and are primarily attributed to the harsh temperatures and pressures encountered in the turbine engines, which mandate the use of specific seal products to prevent any fluid leakage and ensure the efficiency of combustion processes. The segment is positively influenced by the sheer volume of seals needed per engine, including those used in compressors, combustors, and turbines, as well as the recurring replacement needs owing to the extreme stress these seals are subjected to during hundreds of flight hours before engine overhauls.
The Environmental Control & Fuel Systems constitute the most rapidly growing application segment of the Aircraft Seals market and owe their popularity to the electrification of the aircraft and increasing adoption of alternative and sustainable fuels that need specific seals designed to be resistant to new fuel composition. The focus of this segment lies in creating elastomer-based materials that will not degrade when subjected to biofuel blends or hydrogen, which becomes more relevant amid the push towards decarbonization in the industry.
By Material, PTFE & Composite dominates and Fluorosilicone grows fastest
PTFE and composite material grades remain the dominant material segment within the Aircraft Seals Market, reflecting their exceptional chemical resistance, low friction characteristics, and proven performance across the widest range of aerospace operating temperatures and fluid exposure conditions. This segment benefits from decades of accumulated material science refinement and certification history, supporting continued specification across engine, hydraulic, and fuel system applications where reliability and regulatory compliance remain non-negotiable considerations for suppliers seeking to maintain long-term OEM qualification status across multiple aircraft platforms and programs.
Fluorosilicone is emerging as the fastest-growing material segment, driven by its superior performance in extreme temperature and fuel-resistant applications where conventional silicone materials fall short of aerospace requirements. This segment focuses on formulations capable of withstanding sustained exposure to jet fuel, hydraulic fluids, and de-icing chemicals while maintaining flexibility across wide temperature ranges from high-altitude cold soak conditions to hot engine bay environments. As aircraft manufacturers continue pursuing more demanding operating envelopes, fluorosilicone materials are positioned to capture a growing share of specialized sealing applications.
By Aircraft Type, Fixed-Wing dominates and UAV grows fastest
The Fixed Wing aircrafts will continue to dominate the Aircraft Seals Market due to the sheer magnitude of the number of the fixed wing aircrafts in the global market when compared to the rotary wing and the UAV aircrafts. The Fixed Wing aircraft type segment will continue to thrive owing to the large volume of seal replacement needed for the narrow body, widebody and the business jet aircrafts that need hundreds of seals for engine, airframe and system application in each aircraft and hence provide for a very stable and reliable revenue stream for the market.
The UAV platforms represent the fast growing aircrafts in terms of market share and this can be attributed to the increasing production of both the military and civilian unmanned aerial vehicles whose systems require small and light weight seals. The focus here is on providing miniaturized seals that work well in the systems of the unmanned platforms. As global production of UAVs continues to rise this segment is poised to capture an ever increasing market share.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.50% |
|
Asia Pacific |
China |
44.80% |
|
Europe |
France |
32.60% |
|
Latin America |
Brazil |
43.90% |
|
Middle East & Africa |
Israel |
39.60% |
North America Aircraft Seals Market Insights
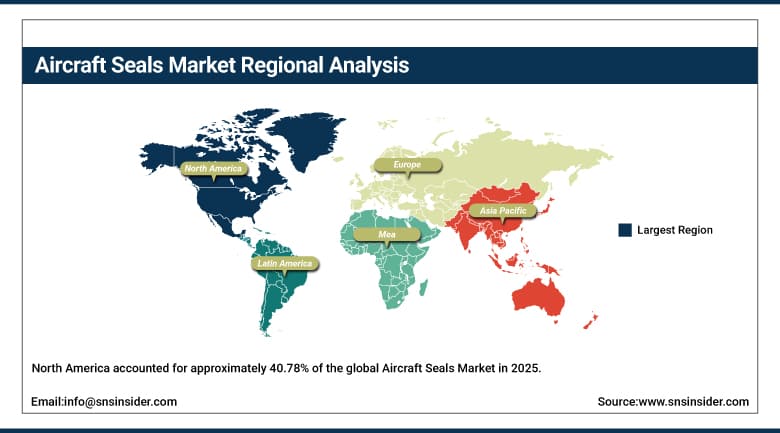
North America accounted for approximately 40.78% of the global Aircraft Seals Market in 2025, reflecting the region's robust aerospace manufacturing base, extensive maintenance and overhaul infrastructure, and concentration of leading sealing technology suppliers. The United States accounts for the substantial majority of regional demand, supported by its position as home to major commercial aircraft final assembly operations, a large domestic fleet requiring continuous replacement seal supply, and sustained defense modernization spending requiring specialized high-performance sealing solutions across military aircraft programs.
Canada contributes additional regional demand through its participation in North American aerospace supply chains and domestic regional aircraft manufacturing activity. Continued strong commercial aircraft order backlogs at major North American airframers, sustained defense procurement across next-generation combat and unmanned aircraft programs, and growing investment in advanced air mobility development further reinforce North America's position as the largest regional market for aircraft seals, with the region's deep aftermarket infrastructure sustaining consistent replacement demand throughout the extended forecast period.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Aircraft Seals Market Insights
Asia Pacific is projected to expand at the fastest CAGR of approximately 7.40% across the Aircraft Seals Market during the 2026-2035 forecast period, driven by rapidly growing commercial aircraft fleets and expanding domestic aerospace manufacturing capability across the region. China represents the largest single contributor within the region, supported by substantial government investment in indigenous commercial aircraft programs and a rapidly expanding domestic maintenance, repair, and overhaul sector requiring growing volumes of replacement sealing components across its rapidly maturing commercial fleet.
India and Japan contribute additional regional growth, with India's expanding commercial aviation sector and growing domestic aircraft maintenance capability supporting rising seal demand, while Japan's established materials manufacturing base contributes advanced sealing component development for both domestic and export markets. Continued regional investment in indigenous aerospace supply chain capability and growing unmanned aerial vehicle manufacturing activity further reinforce Asia Pacific's position as the fastest-growing global market for aircraft sealing solutions across both commercial and defense applications.
Europe Aircraft Seals Market Insights
Europe emerges as an important regional market for aircraft seals, owing to the fact that Europe is the home to the largest number of aerospace manufacturing plants in France and other assembly programs of both commercial and defense aircrafts. Europe’s share in the international market comes from the presence of commercial aircraft manufacturing companies and from research and development efforts of aerospace seal technology, which are made possible due to the presence of various material suppliers in Europe.
Germany and UK also contribute to regional demand through aerospace component manufacturers and defense modernization programs. Further, Europe continues to invest in advanced commercial aircraft programs and defense aerospace programs among the member countries of Europe, resulting in continued regional demand for aircraft seal technology, despite the fact that Europe is lagging behind North America and Asia Pacific in terms of its demand volumes and innovative aerospace materials science.
MEA & Latin America Aircraft Seals Market Insights
The Latin American region’s aircraft seals market is dominated by Brazil, accounting for the bulk of the regional demand on account of the strong commercial aircraft manufacturing industry in the country, in addition to an increasing number of maintenance and overhaul activities in the region. The aircraft manufacturing industry in Brazil, with the presence of aircraft manufacturing in the region and exports from the region, will help drive steady demand for seals for commercial and military aircraft programs, along with incremental demand on account of increasing defense procurement in the region.
The strategic importance of the Middle East and Africa region is rising, with demand being generated in regions like Israel, which has an established defense aerospace manufacturing industry that produces military aircraft programs and also exports to allied countries around the world. Additional regional demand will be driven by the GCC countries on account of increasing commercial aircraft fleet expansion and defense procurement in the region.
Market Dynamics:
Growth Drivers: Aircraft Production Growth and MRO Activity Expansion
Sustained growth in commercial and military aircraft production represents the primary growth driver for the Aircraft Seals Market, as each new aircraft delivered requires hundreds of individual sealing components spanning engine, airframe, and system applications. This dynamic is reinforced by expansion of maintenance, repair, and overhaul activity worldwide, as aircraft seals' comparatively short service life relative to the broader airframe drives a persistent replacement cycle that supports steady aftermarket demand throughout an aircraft's multi-decade operational lifespan, independent of new aircraft delivery volumes in any given year.
Rising use of organic elastomers and advanced polymer chemistry for hydraulic and fuel system sealing provides an additional significant source of demand, as manufacturers continue improving seal performance and durability to meet increasingly stringent aerospace certification requirements. Increased adoption of radar-absorbing materials for stealth applications and advancements in reinforced conducting fabric further support market growth, as defense programs continue prioritizing specialized sealing solutions that serve both mechanical and electromagnetic shielding functions simultaneously.
Restraints: Certification Complexity and Raw Material Cost Volatility
The arduous process of certifications involved in aerospace sealing material development poses a major limitation to the Aircraft Seals Market since any formulation needs to pass numerous qualification tests before getting approved for application in mission critical operations. This is more of an advantage to existing suppliers who have already gone through all the necessary qualifications to be able to provide their products to OEMs. New players in the market find it hard to penetrate the market and sell innovative sealing solutions.
Fluctuations in the prices of specialty polymers and fluoropolymers pose a major risk as far as the future manufacturing costs are concerned since one needs to invest in material formulations at a time when input prices keep fluctuating. Global supply chain network for elastomers and composites hinders manufacturers from easily expanding their production capacity amid a sudden rise in aircraft production levels or after market demand.
Opportunities: Sustainable Aviation Fuel Compatibility and UAV Market Expansion
Continued growth in sustainable aviation fuel adoption presents a substantial growth opportunity for the Aircraft Seals Market, as airlines and manufacturers pursuing decarbonization commitments require seals engineered for compatibility with alternative fuel chemistries that differ meaningfully from conventional jet fuel. Suppliers that can demonstrate validated, chemically compatible sealing solutions for biofuel blends and hydrogen exposure are well positioned to capture share as sustainable aviation fuel adoption continues to expand across both commercial and military aviation sectors worldwide.
Rapid growth in unmanned aerial vehicle production presents a longer-term opportunity for sealing technology suppliers to extend their expertise into an entirely new category of compact, lightweight aircraft platforms. As military and commercial UAV programs continue scaling production volumes, suppliers with established miniaturized sealing component capabilities are positioned to capture a disproportionate share of this emerging demand, particularly as these platforms increasingly require the same reliability standards traditionally reserved for manned aircraft applications.
Recent Developments:
-
In April 2025, Trelleborg acquired Aero-Plastics Inc., a supplier of high-performance polymer components for aircraft interiors, expanding the company's aerospace sealing and interior component portfolio.
-
In May 2024, Trelleborg announced a decision to invest in a new production facility in Morocco focused on sealing systems for the aerospace sector, expanding manufacturing capacity to serve the industry's robust worldwide demand near European assembly plants.
Aircraft Seals Market Key Players:
-
Parker Hannifin Corporation
-
Trelleborg AB
-
Eaton Corporation plc
-
Freudenberg Sealing Technologies GmbH & Co. KG
-
SKF AB
-
Hutchinson SA
-
Saint-Gobain Seals (Omniseal)
-
Technetics Group
-
Greene, Tweed & Co.
-
Bal Seal Engineering
-
Kirkhill (TransDigm Group)
-
Collins Aerospace Technologies Inc.
-
Eagle Industry Co., Ltd.
-
Garlock Sealing Technologies LLC
-
James Walker & Co. Ltd.
-
Precision Polymer Engineering Limited
-
DuPont de Nemours, Inc.
-
LORD Corporation (Parker Hannifin)
-
Marman Products (TransDigm Group)
-
AVIC Sanxin Co., Ltd.
Aircraft Seals Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.61 Billion |
| Market Size by 2035 | USD 6.11 Billion |
| CAGR | CAGR of 5.40% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Type (Dynamic Seals and Static Seals) • by Application (Engine Systems, Environmental Control & Fuel Systems, Airframe, Landing Gear, and Flight Control & Hydraulics) • by Material (PTFE & Composite, Fluorosilicone, Metals, and Others) • by Aircraft Type (Fixed-Wing, Rotary-Wing, and UAV) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Parker Hannifin Corporation, Trelleborg AB, Eaton Corporation plc, Freudenberg Sealing Technologies GmbH & Co. KG, SKF AB, Hutchinson SA, Saint-Gobain Seals (Omniseal), Technetics Group, Greene, Tweed & Co., Bal Seal Engineering, Kirkhill (TransDigm Group), Collins Aerospace Technologies Inc., Eagle Industry Co., Ltd., Garlock Sealing Technologies LLC, James Walker & Co. Ltd., Precision Polymer Engineering Limited, DuPont de Nemours, Inc., LORD Corporation (Parker Hannifin), Marman Products (TransDigm Group), AVIC Sanxin Co., Ltd. |
Frequently Asked Questions
Leading companies in the Aircraft Seals Market include Parker Hannifin, Trelleborg, Eaton, Freudenberg Sealing Technologies, and SKF, among others.
Key opportunities include continued growth in sustainable aviation fuel adoption requiring chemically compatible sealing solutions, and rapid growth in unmanned aerial vehicle production requiring compact, lightweight sealing components.
Sustained growth in commercial and military aircraft production, combined with expansion of maintenance, repair, and overhaul activity requiring frequent seal replacement, is the major factor driving market growth.
The Engine Systems segment dominated the Aircraft Seals Market with approximately 46.10% share in 2025.
North America dominated the Aircraft Seals Market in 2025 with approximately 40.78% share, reflecting the region's robust aerospace manufacturing base, led by the United States.
