
Anastomosis Devices Market Report Scope & Overview:
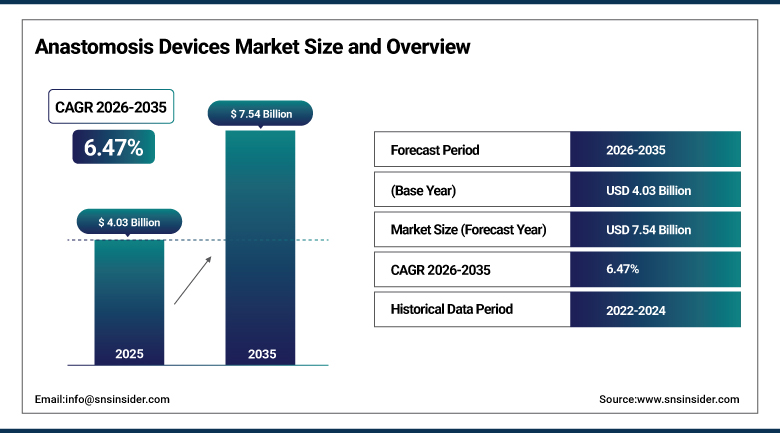
The Anastomosis Devices Market was valued at USD 4.03 Billion in 2025 and is estimated at USD 4.29 Billion in 2026. The market is projected to reach USD 7.54 Billion by 2035, expanding at a CAGR of 6.47% from 2026 to 2035. Anastomosis devices join two hollow structures, such as bowel segments or blood vessels, during surgery, and they include staplers, sutures, sealants, adhesives, and compression systems. Demand follows surgical volumes in colorectal, bariatric, cardiovascular, and transplant care, and it is supported by a steady move to minimally invasive and robotic procedures.
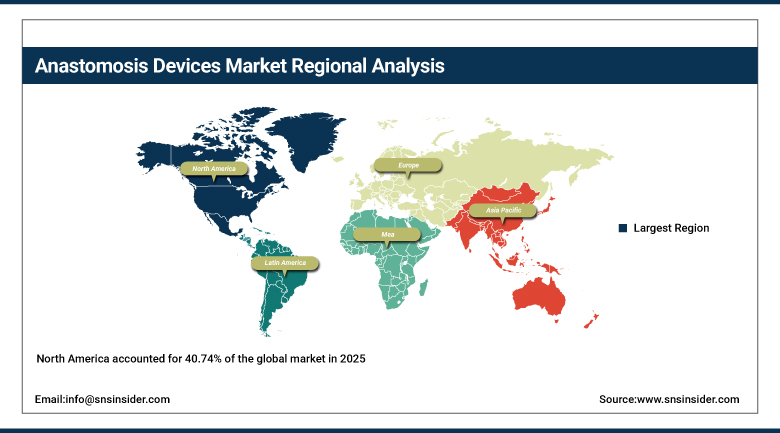
North America was the largest regional market in 2025, with a 40.74% share. The region has a high number of colorectal and cardiac operations, early adoption of powered and robotic staplers, and a large base of hospitals and ambulatory centers that purchase single-use devices. Surgeons increasingly ask for products that lower the risk of anastomotic leak, and manufacturers are responding with sensing staplers, magnetic compression systems, and tissue-specific reloads that give more predictable results across patient groups. Training programs for surgeons and clinical studies on leak rates also help new devices enter routine practice.
To Get more information Anastomosis Devices Market - Request Free Sample Report
Key Report Takeaways
-
By product type, surgical staplers held a 48.63% share in 2025, while surgical sutures are the fastest growing.
-
By usage, disposable devices held a 74.38% share in 2025, while reusable devices are the fastest growing.
-
By application, cardiovascular and thoracic surgery held a 49.36% share in 2025, while gastrointestinal surgery is the fastest growing.
-
By end user, hospitals held a 66.74% share in 2025, while ambulatory care centers and clinics are the fastest growing.
-
By region, North America held a 40.74% share in 2025, while Asia Pacific is the fastest growing.
Market Trends and Insights
Powered circular and linear staplers with sensors that guide compression and firing are replacing manual instruments in colorectal and bariatric operations, because they give surgeons more consistent staple lines.
Magnetic compression systems are emerging as a sutureless option for bowel anastomosis, and several have received regulatory clearance, which signals a wider interest in alternatives to stapled and hand-sewn joins.
Staplers designed for single-port and multiport robotic platforms are expanding, as hospitals add robotic capacity and ask suppliers for instruments that match the access and reach of those systems.
Hospitals and group purchasing bodies are measuring leak rates and length of stay, which is shifting buying decisions toward devices that can show a benefit in complication rates and not only a lower unit price.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Rising Colorectal and Gastrointestinal Disease Burden |
+2.41% |
Global |
Short term (2 years or less) |
|
Cardiovascular Disease and Transplant Procedures |
+1.98% |
North America, Europe |
Medium term (2 to 4 years) |
|
Growth in Bariatric and Obesity Surgery |
+1.53% |
North America, Middle East |
Medium term (2 to 4 years) |
|
Minimally Invasive and Robotic Surgery |
+1.74% |
North America, Asia Pacific |
Medium term (2 to 4 years) |
|
Aging Population |
+1.12% |
Global |
Long term (4 years or more) |
|
Rising Health Spending and Ambulatory Care Expansion |
+0.97% |
Asia Pacific, Latin America |
Long term (4 years or more) |
Rising Colorectal and Gastrointestinal Disease Burden
Colorectal cancer, diverticular disease, inflammatory bowel disease, and other digestive conditions often require resection followed by reconnection of the bowel, which makes anastomosis devices a routine part of the operating room. Earlier screening also leads to more planned surgeries. In February 2026, the World Health Organization reported about 1.9 million new colorectal cancer cases worldwide in 2022, which points to a large and growing pool of patients who will need surgical treatment over the forecast period. This supports long-term demand.
Cardiovascular Disease and Transplant Procedures
Coronary bypass, peripheral vascular reconstruction, and organ transplantation all depend on secure joins between vessels or between organs and vessels. Surgeons use sutures, vascular couplers, and sealants to achieve these joins, and demand tracks the number of cardiac and vascular operations. In 2026, the Organ Procurement and Transplantation Network reported 49,064 organ transplants in the United States in 2025, a record that sustains need for vascular anastomosis products. Growing numbers of older patients with vascular disease add further demand for these products.
Growth in Bariatric and Obesity Surgery
Gastric bypass and related metabolic operations create new connections between the stomach and small intestine, and these steps rely heavily on stapling devices. Obesity is a long-term driver of surgical activity, and many centers are expanding their programs. In May 2026, the American Society for Metabolic and Bariatric Surgery reported 177,297 metabolic and bariatric procedures in 2024, which keeps a large and steady base of operations for staplers and related products. Hospitals that run these programs usually purchase staplers in large quantities.
Minimally Invasive and Robotic Surgery
Laparoscopic and robotic approaches reduce pain, blood loss, and hospital stay, and they have become the preferred route for many colorectal and thoracic operations. These approaches need slim, articulating, and powered instruments that can be used through small ports, so suppliers are introducing new staplers designed for those platforms. As hospitals add robotic capacity, they replace older manual devices with more advanced and higher-priced products. Training programs and proctoring from manufacturers help surgeons adopt these tools safely and more quickly.
Aging Population
Older adults have a higher incidence of colorectal cancer, heart disease, and vascular disease, and they undergo a larger share of the operations that involve anastomosis. Longer life expectancy in Europe, North America, and East Asia therefore supports a stable flow of procedures. Surgeons also treat older and frailer patients, who benefit from devices that shorten operating time and give reliable seals, and this encourages use of advanced products. Hospitals serving this group value reliable and easy-to-use products with proven results.
Rising Health Spending and Ambulatory Care Expansion
Growing health budgets in emerging economies are improving access to surgery, and new hospitals and day-surgery centers are adding equipment for general and gastrointestinal procedures. Governments are investing in cancer care and cardiac programs, and private insurers are widening coverage. These changes increase the number of patients who can reach an operating room, and they open a larger market for both basic and advanced anastomosis products in Asia Pacific and Latin America. Rising private insurance coverage supports the same trend.
Restraints Impact Analysis
|
Restraints |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Anastomotic Leak Risk and Complications |
-1.35% |
Global |
Short term (2 years or less) |
|
High Device Cost and Reimbursement Pressure |
-0.98% |
Global |
Medium term (2 to 4 years) |
|
Strict and Changing Regulatory Requirements |
-0.62% |
Europe, North America |
Medium term (2 to 4 years) |
|
Surgeon Training Needs and Preference for Hand-Sewn Techniques |
-0.33% |
Global |
Long term (4 years or more) |
Anastomotic Leak Risk and Complications
Leakage at the join is a serious complication that can cause infection, repeat surgery, and longer hospital stay, and fear of this outcome makes surgeons cautious about changing devices or technique. Product recalls and malfunction reports also affect confidence in staplers. In July 2026, the U.S. Centers for Disease Control and Prevention reported a 4.00% decrease in colon surgery site infections in 2024 compared with 2023, which shows progress, but complication risk still shapes purchasing. This supports demand for safer devices.
High Device Cost and Reimbursement Pressure
Powered, sensing, and robotic-compatible staplers cost much more than manual instruments, and the reloads that go with them add to the price per procedure. Hospitals in low and middle income countries often cannot afford them, and in some systems payment does not rise when a more advanced device is used. Purchasing groups also push for lower prices, which limits the margin available for investment in new designs. Smaller hospitals therefore delay replacing older instruments, which slows adoption of premium products.
Strict and Changing Regulatory Requirements
Anastomosis devices are implanted or leave material in the body, so regulators ask for detailed clinical and quality evidence. In Europe, Regulation (EU) 2023/607 extended the Medical Device Regulation transition, with class III and class IIb implantable devices required to comply by 31 December 2027, and manufacturers must complete recertification of existing products. These steps raise cost and can delay launches, particularly for small suppliers. Compliance costs also fall on distributors, who must update labeling, records, and complaint handling systems.
Surgeon Training Needs and Preference for Hand-Sewn Techniques
Many surgeons are trained in hand-sewn anastomosis and trust it, particularly in vascular and pediatric surgery where precision matters. Newer devices require training on firing, compression, and tissue selection, and a learning curve can affect results at first. Hospitals with a limited number of procedures may see little reason to change, and this slows the spread of powered and sutureless products in smaller centers. Manufacturers therefore invest in simulation, proctoring, and clinical support, which raises the cost of expanding into new hospitals.
Anastomosis Devices Market Segment Analysis
By Product Type, Surgical Staplers Dominate Anastomosis Devices Market; Surgical Sutures to Register Fastest Growth.
The surgical staplers have gained leadership in the product axis since they offer fast and even joining of tissues in gastrointestinal, abdominal, and thoracic surgeries and account for 48.63% of the market in 2025. The circular staplers are employed in end-to-end anastomoses in colon rectum and esophagus surgeries, and the linear cutters perform cutting and stapling operations. The powered surgical staplers, along with their reloads, help in the generation of recurring revenues; hospitals prefer standardized products of reliable manufacturers. Hospitals also consider the extensive history of clinical practice, as well as availability of many sizes and lengths of staples.
The surgical sutures are forecast to witness a CAGR of 7.62% in the period of 2026 to 2035. The barbed, absorbable sutures, as well as automated suturing assistance, are gaining popularity in robotic and minimally invasive procedures. Moreover, vascular surgery involves fine sutures for precise stitching. Surgeons are using new suture designs owing to better material composition and reduced risk of infections. Improved materials for wound closure minimize tissue dragging and knotting, which supports continued purchase by cardiosurgery departments.
By Usage, Disposable Devices Dominate Anastomosis Devices Market; Reusable Devices to Register Fastest Growth.
Disposable devices hold the largest share, at 74.38% in 2025, because single-use instruments remove the need for cleaning and sterilization and lower the risk of cross infection. Hospitals prefer them for consistent performance, and manufacturers sell staplers together with matched reloads. The model also gives suppliers a predictable stream of repeat orders, which supports investment in new product generations. Large health systems also negotiate supply agreements that favor standardized disposable lines, which gives suppliers stable demand in each hospital.
Reusable devices are expected to register the fastest growth, at a CAGR of 7.11% over 2026 to 2035. Hospitals are looking for ways to cut waste and cost per case, and hybrid designs with a reusable handle and a disposable reload are gaining attention. Sustainability targets and pressure on operating room budgets are encouraging buyers to test instruments that can be used again. Manufacturers are responding by redesigning handles for longer service life and easier cleaning between uses.
By Application, Cardiovascular & Thoracic Surgery Dominates Anastomosis Devices Market; Gastrointestinal Surgery to Register Fastest Growth.
The share of cardiovascular and thoracic surgeries is 49.36% in 2025. Operations such as coronary bypass, vascular reconstruction, and lungs/esophagus surgeries need stable joins, and surgeons rely on various suture, coupler, and stapler techniques. High number of procedures in North America and Europe and also transplant surgeries provide a strong platform for this application type; however, some reports say whether this one or gastrointestinal surgery has more volume. Devices which have a good reputation for many years are preferred by surgeons in these areas.
The predicted CAGR of gastrointestinal surgery between 2026-2035 is 6.93%. Colorectal cancers resection, bariatric surgery, and inflammation bowel disease are all conditions which lead to surgical bowel anastomosis, and there are screenings that find the diseases early. Powered circular staplers and magnetic compression system are mostly introduced in this area; thus, the growth rate is higher compared to other applications. Also, surgeons gain more experience with robotic bowel surgery, and hospital develops recovery strategies which need fast and efficient joins and surgery time.
By End User, Hospitals Dominate Anastomosis Devices Market; Ambulatory Care Centers & Clinics to Register Fastest Growth.
Hospitals hold 66.74% of the market in 2025, since most anastomosis procedures are complex and need anesthesia, intensive care, and surgical teams. Large hospitals also run robotic programs and buy the most advanced instruments. Central purchasing departments sign supply contracts with major manufacturers, and these long-term agreements give leading suppliers a stable position with high-volume surgical departments and teaching centers. Teaching hospitals also train residents and run clinical studies, which exposes them early to every new stapler, suture, and sealant.
Ambulatory care centers and clinics are projected to grow at a CAGR of 7.58% during 2026 to 2035. Payers encourage lower-cost settings, and improved devices and anesthesia are allowing a wider set of gastrointestinal and vascular operations to be done as day cases. New surgical centers in the United States and Asia Pacific are equipping themselves with staplers and sealants. Specialty clinics focused on colorectal and vascular care are also expanding, and hospitals partner with them to shift cases.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.12% |
|
Europe |
Germany |
22.41% |
|
Asia Pacific |
China |
33.97% |
|
Middle East & Africa |
Saudi Arabia |
29.18% |
|
Latin America |
Brazil |
43.65% |
North America Anastomosis Devices Market
North America accounted for 40.74% of the global market in 2025, supported by high surgical volumes, wide use of powered and robotic staplers, and the presence of leading manufacturers. The United States market was valued at USD 1.40 Billion in 2025 and is projected to grow at a CAGR of 6.19% from 2026 to 2035. In 2026, the American Cancer Society estimated about 158,850 new colorectal cancer cases in the United States. These strengths keep the region well ahead of the others.
Regulatory activity is steady in the region. In August 2025, the U.S. Food and Drug Administration cleared a magnetic compression system for side-to-side small bowel anastomosis, which shows openness to sutureless methods. Canada adds demand through its public hospital system, and Mexico contributes through private hospital groups and growing medical device manufacturing near the border. Ambulatory surgery centers in the region are also taking on a larger share of gastrointestinal and vascular cases, and group purchasing organizations negotiate supply contracts that favor established suppliers.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Anastomosis Devices Market
Europe is the second-biggest player in terms of market share with Germany being the most significant country in the region, followed by the UK, France, Italy, and Spain. High rates of colorectal disease prevalence, aging populations, and well-developed public hospitals ensure consistent utilization of staplers, sutures, and sealants. Centralized procurement process results in competitive environment based on the quality of evidence and long-term contracts. In addition, several European countries witness increasing consolidation of healthcare systems that gives them additional leverage during tender processes for staplers and sutures, thus keeping pressure on prices.
The increase in demand in relation to surgical procedures is due to screening programs. For instance, beginning from January 2025, NHS England will roll out home testing kit for bowel cancer in all people over 50 years old making another 850,000 people to be screened annually. Medical Device Regulation will continue influencing product development strategy, and companies that are larger and have developed compliance teams have more opportunities to retain their product portfolio. Robotic surgery is actively developed in Germany and France while the Nordic countries implement enhanced recovery protocols.
Asia Pacific Anastomosis Devices Market
Asia-Pacific is the fastest-growing market, with CAGR forecasted to be at 7.77% between 2026-2035. The key countries in the region include China, Japan, India, South Korea, and Australia. Population growth, increase in cancer diagnosis, and investments in hospitals and surgical training are leading to more surgeries being performed. Manufacturers are developing in staplers and sutures, and provide cheaper substitutes to their international counterparts. Both Australia and South Korea generate stable demand due to their highly funded public hospitals and cancer screening programs, which lead to an earlier detection of disease.
Japan is a developed market that quickly adopts the most modern and innovative technologies like robotic and powered instrumentation, while India and Southeast Asian countries are growing because of the expansion of private hospital networks and medical tourism. In addition, governments invest in cancer centers and cardiac units in secondary cities; this helps create wider access to surgeries and increases demand for both low-end and high-end anastomosis devices. In March 2026, Singapore's Health Sciences Authority and Malaysia's Medical Device Authority have fully implemented the device regulatory reliance program.
Latin America Anastomosis Devices Market
Latin America is a smaller region, led by Brazil, followed by Mexico, Argentina, and Colombia. Rising cancer incidence, expanding private insurance, and investment in public hospitals support demand for staplers and sutures. In October 2026, Brazil's National Cancer Institute projected about 781,000 new cancer cases a year for 2026 to 2028, which indicates a large future need for oncologic surgery. Private hospital groups in Mexico and Brazil are adding laparoscopic capacity, which raises demand for staplers and related single-use disposables.
Mexico belongs to this region and benefits from private hospital networks and medical tourism. Purchasing in many countries depends on public tenders, so price is a key factor, and imported devices face currency risk and customs delays. Local distributors therefore play an important role in supplying hospitals and in training surgeons on newer instruments. Training programs run with international surgical societies and manufacturers are helping hospitals in major cities adopt laparoscopic techniques, which in turn increases use of modern stapling and compression devices.
Middle East & Africa Anastomosis Devices Market
The Middle East & Africa region holds the smallest share of the market, but health system investment in the Gulf is lifting demand. Saudi Arabia and the United Arab Emirates are the main buyers, while Qatar, Kuwait, and South Africa follow. The Saudi Cancer Registry's 2023 report recorded 2,680 colorectal cancer cases among Saudi nationals, ranking it second among cancers in the country. Government plans to build specialty hospitals and surgical centers are creating new buyers of surgical devices throughout the Gulf.
Large public hospitals and new cancer centers in the Gulf buy advanced staplers and sealants, often through international suppliers. In Africa, South Africa and Egypt are the leading markets, though limited funding and few trained surgeons restrict wider use. Training partnerships and imported equipment are the main routes for newer anastomosis devices. In April 2025, South Africa's health products regulator SAHPRA announced that it had joined the Medical Device Single Audit Program, which should help align local approvals with international standards.
Competitive Landscape
The Anastomosis Devices Market has a fairly concentrated market structure. Medtronic and Johnson & Johnson MedTech have an extensive product line of staplers, whereas Intuitive Surgical is competing by developing staplers that can be operated via its robotic platforms. The smaller companies like GI Windows and GT Metabolic Solutions concentrate their efforts on magnetic compression systems, which do not require staples or sutures at all. Competing on reduced leakage, usability, and robotic capability.
Strategies that vendors apply include development of powered and sensor-enabled staplers, obtaining regulatory approvals for sutureless devices, and establishing supply contracts for long terms with hospital networks. Clinical trials regarding leak rates serve as an evidence base for premium pricing, and collaboration with robotic platform providers enables suppliers to penetrate into hospitals that are launching minimally invasive programs.
Anastomosis Devices Market Industry Leaders
1. Medtronic: Signia Circular Stapler with Tri-Staple technology and EEA circular staplers.
2. Johnson & Johnson MedTech: ECHELON CIRCULAR Powered Stapler and the ETHICON 4000 Stapler.
3. Intuitive Surgical: SP SureForm 45 stapler for the da Vinci SP platform.
4. GI Windows: Flexagon magnetic compression anastomosis system.
5. GT Metabolic Solutions: MagDI magnetic compression anastomosis system.
Companies Covered in this Report
-
Medtronic
-
Johnson & Johnson MedTech (Ethicon)
-
Intuitive Surgical
-
GI Windows
-
GT Metabolic Solutions
Recent Industry Developments
-
June 2025: Johnson & Johnson MedTech launched the ETHICON 4000 Stapler with 3D Reloads in the United States.
-
June 2025: GI Windows received U.S. Food and Drug Administration clearance for its Flexagon magnetic compression anastomosis system.
-
April 2025: Intuitive Surgical received U.S. Food and Drug Administration clearance for the SP SureForm 45 stapler for the da Vinci SP.
-
November 2025: Medtronic introduced the Signia Circular Stapler with Tri-Staple technology in a limited launch.
-
June 2026: GT Metabolic Solutions received U.S. Food and Drug Administration clearance for the MagDI System.
Anastomosis Devices Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 4.03 Billion |
| Market Size by 2035 | USD 7.54 Billion |
| CAGR | CAGR of 6.47% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Surgical Staplers, Surgical Sutures, Automated Suturing Devices, Sealants and Adhesives, and Compression Devices) • By Usage (Disposable and Reusable) • By Application (Cardiovascular and Thoracic Surgery, Gastrointestinal Surgery, and Others) • By End User (Hospitals, Ambulatory Care Centers and Clinics, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Medtronic, Johnson & Johnson MedTech (Ethicon), Intuitive Surgical, GI Windows, GT Metabolic Solutions |

Frequently Asked Questions
The market was valued at USD 4.03 Billion in 2025 and is estimated at USD 4.29 Billion in 2026. It is projected to reach USD 7.54 Billion by 2035.
The market is projected to grow at a CAGR of 6.47% from 2026 to 2035, supported by colorectal, bariatric, and cardiovascular surgery.
North America leads, with a 40.74% share in 2025, owing to high surgical volumes and early adoption of powered and robotic staplers.
Asia Pacific is the fastest-growing region, with a CAGR of 7.77% from 2026 to 2035, driven by hospital investment and rising cancer detection.
Surgical staplers, disposable devices, cardiovascular and thoracic surgery, and hospitals lead their axes. Surgical sutures, reusable devices, gastrointestinal surgery, and ambulatory care centers and clinics are the fastest growing.
Medtronic, Johnson & Johnson MedTech, Intuitive Surgical, GI Windows, and GT Metabolic Solutions are the major players covered.
Anastomotic leak risk, high device cost, strict regulation, and surgeon preference for hand-sewn techniques restrain faster adoption.
