
Antiepileptic Drugs Market Report Scope & Overview:
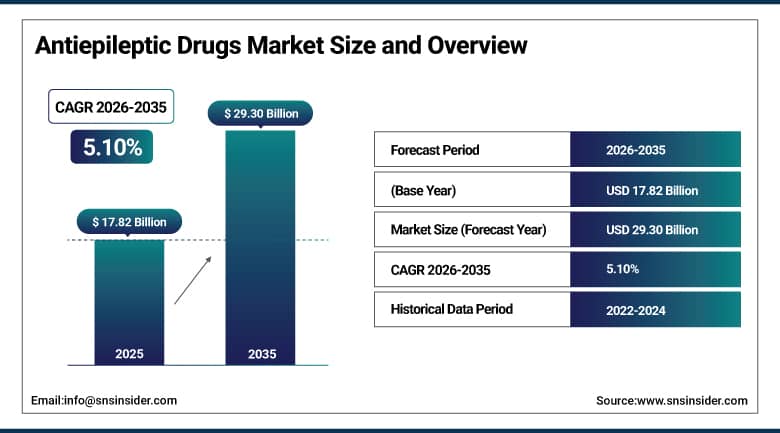
The Antiepileptic Drugs Market was valued at USD 17.82 Billion in 2025 and is expected to reach USD 29.30 Billion by 2035, growing at a CAGR of 5.10% from 2026-2035.
Antiepileptic drugs stabilize abnormal electrical activity in the brain to prevent or control seizures, and while they don't cure epilepsy, they meaningfully reduce seizure frequency and severity for the large majority of diagnosed patients when the right drug and dose are matched to the individual case. Third-generation antiepileptics have steadily displaced older first- and second-generation therapies as the clinical default, since their improved safety profiles, enhanced efficacy, and better tolerability translate directly into fewer side effects and better long-term patient adherence, a genuinely important consideration for a therapy class patients often need to take daily for years or decades. Rising global epilepsy prevalence, combined with growing diagnostic awareness and improving access to neurological care in historically underserved regions, continues to expand the diagnosed patient population these drugs treat.
A global health agency reported in 2025 that structured epilepsy treatment programs implemented across more than 150 public hospitals in developing regions improved early seizure control rates by 22% within monitored patient cohorts, a result that matters because it demonstrates how much of the epilepsy treatment gap in emerging markets stems from access and diagnosis limitations rather than drug availability alone. Separately, the integration of digital seizure-monitoring devices into treatment regimens has improved medication adherence by nearly 20% in monitored patient cohorts, suggesting that pairing antiepileptic drug therapy with connected monitoring technology may become an increasingly standard part of comprehensive epilepsy management rather than a niche add-on limited to the most complex cases.
To Get More Information On Antiepileptic Drugs Market - Request Free Sample Report
Antiepileptic Drugs Market Trends
-
Third-generation antiepileptics continue displacing older drug classes given their improved safety, tolerability, and side-effect profiles.
-
Digital seizure-monitoring device integration is improving medication adherence within monitored patient treatment regimens.
-
Online and specialty digital pharmacy channels are expanding rapidly, supported by growing tele-neurology adoption and home-delivery convenience.
-
Extended-release and precision neurology formulation research continues to receive substantial pharmaceutical manufacturer R&D investment.
-
Structured epilepsy treatment programs in developing regions are meaningfully improving early seizure control rates among previously underserved patient populations.
U.S. Antiepileptic Drugs Market Outlook
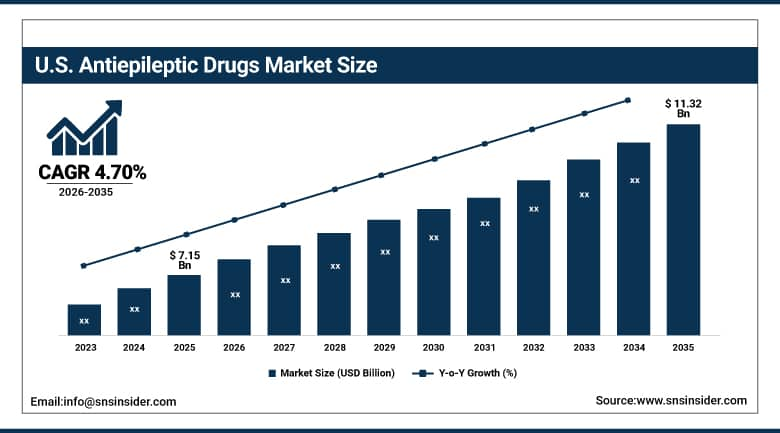
The U.S. Antiepileptic Drugs Market was valued at approximately USD 7.15 Billion in 2025 and is expected to reach approximately USD 11.32 Billion by 2035, growing at a CAGR of approximately 4.70%.
The U.S. market benefits from established neurology networks, dedicated epilepsy centers, strong insurance coverage, and widespread access to electroencephalography and neuroimaging diagnostic capability that supports both accurate diagnosis and ongoing treatment monitoring. The CDC estimates that approximately 2.9 million U.S. adults live with active epilepsy, a diagnosed population base that continues to sustain steady demand for both established and newer antiepileptic therapies across the full range of care settings from hospital neurology departments to community-based outpatient clinics.
U.S.-based pharmaceutical manufacturers continued allocating over 15% of neurology drug revenues to research and development in 2024 and 2025, accelerating innovation in extended-release formulations and precision neurology approaches that tailor drug selection to individual patient seizure type and genetic profile. This sustained R&D investment level, notably higher than many other therapeutic categories, reflects the pharmaceutical industry's continued view of epilepsy as a genuinely underserved neurological condition where meaningful clinical improvement remains achievable, unlike some more mature drug categories where incremental innovation has become increasingly difficult to differentiate commercially.
Antiepileptic Drugs Market Segment Analysis
-
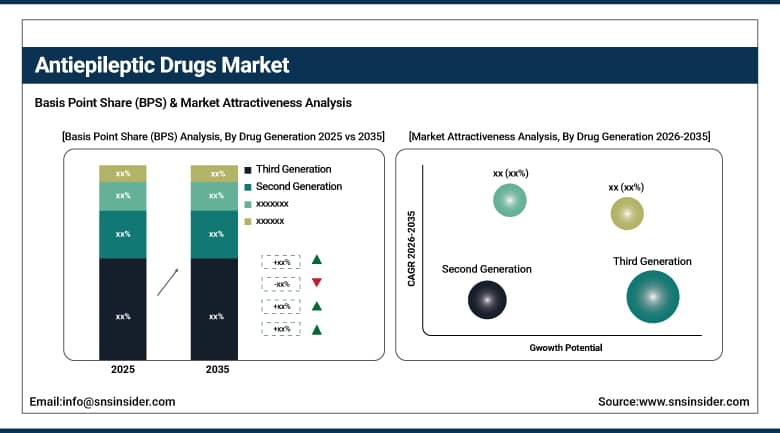
By Drug Generation, the Third Generation segment dominated the Antiepileptic Drugs Market with approximately 46.80% share in 2025, and is also the fastest growing with a CAGR of approximately 6.60%.
-
By Route of Administration, the Oral segment dominated the Antiepileptic Drugs Market with approximately 82.40% share in 2025, while the Intravenous/Parenteral segment is the fastest growing with a CAGR of approximately 6.80%.
-
By Distribution Channel, the Hospital Pharmacies segment dominated the Antiepileptic Drugs Market with approximately 52.00% share in 2025, while the Online/Specialty Pharmacies segment is the fastest growing with a CAGR of approximately 6.10%.
By Drug Generation, third generation dominates and grows fastest
Third generation antiepileptics dominated the drug generation segment in 2025 with approximately 46.80% share, and their improved safety profiles, enhanced efficacy, better tolerability, and reduced side effects continue to fuel both their dominant position and their above-market growth rate as physicians increasingly prescribe these newer therapies as first-line treatment. Growing physician confidence in these newer molecules, built on an expanding real-world evidence base beyond initial clinical trial data, continues to reinforce their position as the preferred first-line prescribing choice for newly diagnosed patients.
The same improved tolerability and reduced drug interaction profile that has made third-generation drugs the clinical default also continues to drive their fastest-growing status, as physicians increasingly transition existing patients from older first- and second-generation therapies toward these newer options, particularly for patients managing epilepsy alongside other chronic conditions requiring careful medication interaction management. Pharmaceutical companies continue directing the bulk of their epilepsy-focused research and development budgets toward this drug class, further reinforcing its growth advantage over older, more established generations.
By Route of Administration, oral dominates, intravenous/parenteral grows fastest
The oral administration was dominant in the route segment in 2025, accounting for about 82.40% share due to non-invasive nature, easy applicability, high patient compliance and general convenience offered by this form of drug administration which is generally required for the daily administration of drugs in the management of epilepsy, a condition requiring prolonged therapy over years or even decades. For children suffering from epilepsy, the preferred mode of drug administration still remains oral because it allows the use of liquid and chewable formulations suitable for children compared to injectable formulations.
The intravenous and parenteral route is the most rapidly growing route segment with a CAGR of 6.80% projected over the forecast period, due to the increasing demand for fast acting formulations that can manage seizure emergency and status epilepticus cases which are best managed through intravenous mode in hospitals and emergency departments. Increasing number of emergency department guidelines for the standardized intravenous administration of rapid-acting antiepileptics continue to boost this route segment.
By Distribution Channel, hospital pharmacies dominates, online/specialty pharmacies grows fastest
Hospital pharmacies dominated the distribution channel segment in 2025 with approximately 52.00% share, given their centralized procurement systems, specialist neurology oversight, and role as the first point of access for many antiepileptic drug therapies, particularly for newly diagnosed patients requiring inpatient stabilization or specialized epilepsy monitoring unit care. Academic medical centers and specialized epilepsy monitoring units also rely heavily on hospital pharmacy channels given the complex, closely supervised medication titration many newly diagnosed or treatment-resistant patients require.
Online and specialty digital pharmacies are the fastest-growing distribution channel, expanding at a CAGR of approximately 6.10% over the forecast period, supported by growing tele-neurology adoption and home-delivery convenience that particularly benefits patients managing a chronic condition requiring consistent, long-term medication refills. Growing chronic disease telehealth infrastructure continues to make online pharmacy channels increasingly viable even for patients requiring regular neurologist oversight, further supporting this channel's rapid growth.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
82.90% |
|
Europe |
Germany |
24.80% |
|
Asia Pacific |
China |
33.60% |
|
Latin America |
Brazil |
28.70% |
|
Middle East & Africa |
Saudi Arabia |
21.40% |
North America Antiepileptic Drugs Market Insights
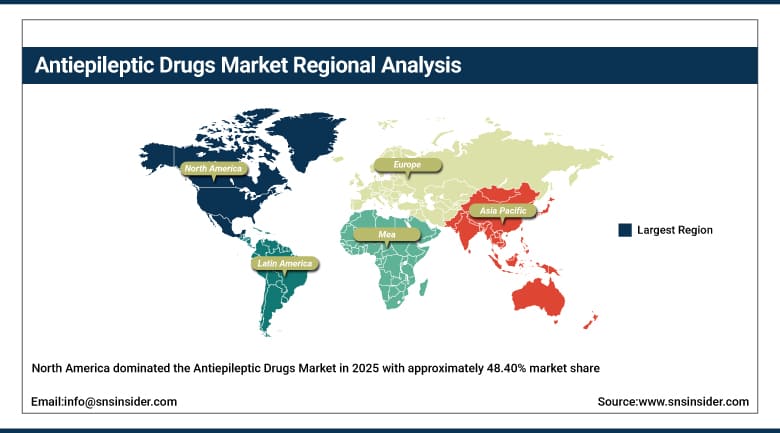
North America dominated the Antiepileptic Drugs Market in 2025 with approximately 48.40% market share, supported by higher diagnosis rates, strong reimbursement policies, and frequent regulatory approvals for novel epilepsy drugs across the region's well-established healthcare infrastructure. Extensive private insurance coverage across the region continues to support patient access to newer, higher-cost third-generation therapies that might otherwise remain financially out of reach for many patients.
The United States accounts for the substantial majority of regional demand, driven by established neurology networks and widespread diagnostic imaging access. Canadian healthcare systems continue to expand access to both established and newer antiepileptic therapies across provincial drug benefit programs. Growing telehealth-based neurology consultation access across both countries continues to improve treatment continuity for patients in geographically remote areas.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Antiepileptic Drugs Market Insights
Asia Pacific is the fastest-growing region in the Antiepileptic Drugs Market, expanding at a CAGR of approximately 7.90% over the forecast period, driven by increasing epilepsy prevalence, improving healthcare infrastructure, expanding access to neurological care, and rising healthcare expenditure across China, India, and Southeast Asian markets. Government epilepsy awareness and screening initiatives across several Asia Pacific countries continue to narrow the historical diagnosis gap between the region and more established Western healthcare markets.
China's expanding hospital neurology infrastructure continues to anchor regional demand, while India's large diagnosed and undiagnosed epilepsy patient population represents substantial untapped treatment demand as diagnostic access continues improving. Japan and South Korea continue contributing advanced formulation research supporting the broader regional therapeutic base. Southeast Asian markets continue expanding neurology specialist training programs, gradually building the clinical capacity needed to support growing diagnosed patient populations.
Europe Antiepileptic Drugs Market Insights
Europe is considered to be an advanced market for antiepileptic drugs; among the region’s countries, Germany plays the lead role with regard to the number of hospital neurology centers and local production of pharmaceutical products. The growth of the market is ensured through further regulatory approval, despite occasional difficulties with logistics in some drug forms. An increased availability of generics and biosimilars of antiepileptic drugs in the region helps ensure affordability for patients.
France and the UK contribute additional demand, both markets favoring newer third-generation therapies within their national health systems. Nordic countries continue to serve as an early proving ground for digital seizure-monitoring device integration pilots supporting broader European adoption. Eastern European markets continue gradually expanding access to newer therapy generations as regional healthcare spending capacity improves over time.
MEA & Latin America Antiepileptic Drugs Market Insights
The Middle East and Africa represent a smaller but growing market, with Saudi Arabia driving regional demand through substantial healthcare infrastructure investment tied to the country's broader economic diversification strategy and expanding neurological care access. Growing Gulf state investment in specialized neurology treatment centers continues to expand regional diagnostic and treatment capacity beyond what was previously available.
Latin America is a growing market led by Brazil, where an expanding private healthcare sector and improving epilepsy diagnosis rates continue to drive antiepileptic drug demand. Mexico contributes meaningful secondary demand through its growing public healthcare neurology infrastructure. Argentine and Colombian public healthcare systems continue to gradually expand antiepileptic drug access as national treatment protocol standardization efforts progress.
Market Dynamics
Growth Drivers: Rising epilepsy prevalence and improving diagnostic access fueling demand
The increase in the number of people around the world suffering from epilepsy, along with greater knowledge about neurological problems, will only serve to increase the number of diagnosed patients these medicines can treat, as better public health education increases awareness about seizures. Increasing efforts on the part of the public health system in schools and workplaces to screen for such conditions will help to diagnose such cases earlier, hence adding to the patient population that can be treated through the use of such medicines.
Continuous innovations in medicine and government funding of research programs on epilepsy will increase the capacity of the health care sector in developing countries, hence making the medicines more accessible to the affected population.
Restraints: Treatment resistance and drug interaction complexity limiting broader effectiveness
A meaningful share of epilepsy patients continue to experience drug-resistant seizures despite optimal antiepileptic therapy, requiring more complex, multi-drug treatment regimens or surgical intervention that conventional antiepileptic drugs alone cannot fully address. Developing more effective therapies for this treatment-resistant patient subgroup remains one of the field's most significant unmet clinical needs, representing both a persistent challenge and a substantial commercial opportunity for successful innovators.
Complex drug interaction profiles, particularly for patients managing epilepsy alongside other chronic conditions requiring multiple concurrent medications, continue to complicate treatment selection and require careful ongoing clinical management that can limit broader treatment optimization.
Opportunities: Precision neurology and digital monitoring integration widening addressable demand
Further development of precision neurology and the use of the right drug depending on patient seizure type and genetics represents a major opportunity for drug manufacturers to enhance efficacy of the treatment and create a unique competitive advantage in comparison to wider-spectrum standard drugs. The integration of genetic tests into the process of diagnosing epileptic seizures adds more clinical evidence to the choice of an individualized drug and not the usual "guessing" that has been traditionally used.
The increasing use of monitoring devices in the process of treatment represents a chance for pharmaceutical companies to combine the drug treatment and connected monitoring, which increases the adherence and outcome of the treatment.
Recent Developments:
-
2024- UCB Pharma Limited expanded its antiepileptic drug portfolio with continued investment in next-generation seizure management therapies targeting drug-resistant epilepsy populations.
-
2024- Eisai Co., Ltd. announced expanded clinical development of extended-release antiepileptic formulations aimed at improving long-term patient medication adherence.
-
2023- Jazz Pharmaceuticals plc expanded its neurology drug portfolio, targeting growing demand for precision-matched antiepileptic therapies across specialized epilepsy treatment centers.
Antiepileptic Drugs Market Key Players
-
UCB Pharma Limited
-
Sanofi S.A.
-
Pfizer Inc.
-
Novartis AG
-
GSK plc
-
Eisai Co., Ltd.
-
Johnson & Johnson Services, Inc.
-
Abbott Laboratories
-
Jazz Pharmaceuticals plc
-
Bausch Health Companies Inc.
-
Sun Pharmaceutical Industries Ltd.
-
Teva Pharmaceutical Industries Ltd.
-
Viatris Inc. (Mylan)
-
Hikma Pharmaceuticals PLC
-
Lupin Limited
-
Cipla Limited
-
Aurobindo Pharma Limited
-
Zogenix, Inc.
-
Supernus Pharmaceuticals, Inc.
-
SK Life Science, Inc.
Antiepileptic Drugs Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 17.82 Billion |
| Market Size by 2035 | USD 29.30 Billion |
| CAGR | CAGR of 5.10% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Drug Generation (First Generation, Second Generation, Third Generation) • By Route of Administration (Oral, Intravenous/Parenteral) • By Distribution Channel (Hospital Pharmacies, Retail Pharmacies, Online/Specialty Pharmacies) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | UCB Pharma Limited, Sanofi S.A., Pfizer Inc., Novartis AG, GSK plc, Eisai Co., Ltd., Johnson & Johnson Services, Inc., Abbott Laboratories, Jazz Pharmaceuticals plc, Bausch Health Companies Inc., Sun Pharmaceutical Industries Ltd., Teva Pharmaceutical Industries Ltd., Viatris Inc. (Mylan), Hikma Pharmaceuticals PLC, Lupin Limited, Cipla Limited, Aurobindo Pharma Limited, Zogenix, Inc., Supernus Pharmaceuticals, Inc., SK Life Science, Inc. |

Frequently Asked Questions
Key players in the Antiepileptic Drugs Market include UCB Pharma Limited, Sanofi S.A., Pfizer Inc., Novartis AG, and GSK plc, among others.
Key opportunities include continued advancement in precision neurology tailoring drug selection to individual patient profiles, and growing integration of digital seizure-monitoring devices into treatment regimens.
The market is driven by rising global epilepsy prevalence and increasing awareness of neurological disorders, alongside continuous advancements in drug development and expanding healthcare infrastructure in emerging markets.
The Third Generation segment dominated the Antiepileptic Drugs Market, accounting for approximately 46.80% market share, and is also the fastest-growing segment.
North America dominated the Antiepileptic Drugs Market in 2025 with approximately 48.40% share, supported by higher diagnosis rates and strong reimbursement policies.
