
Ascorbic Acid Market Report Scope & Overview:
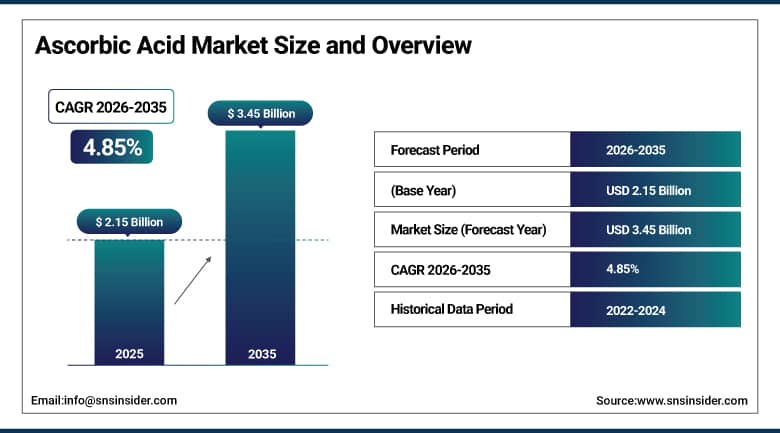
The Ascorbic Acid Market was valued at USD 2.15 Billion in 2025 and is expected to reach USD 3.45 Billion by 2035, growing at a CAGR of 4.85% from 2026–2035.
Ascorbic acid, better known as vitamin C, is produced mainly through large-scale fermentation of corn-derived glucose, with a smaller share coming from chemical synthesis. Food and beverage makers use it as both a nutrient and a preservative, supplement brands sell it as a standalone immune-health product, and pharmaceutical manufacturers rely on it as an active ingredient in formulations ranging from effervescent tablets to injectable solutions. Cosmetics brands add it for its brightening and antioxidant properties in serums and creams.
China's three largest ascorbic acid producers, CSPC Pharmaceutical, Northeast Pharmaceutical Group, and Shandong Luwei, together account for roughly 60% of global fermentation-based output, all built on corn-glucose feedstock. That concentration means a shift in Chinese production economics, whether from feedstock costs, energy prices, or environmental policy, tends to move global ascorbic acid pricing almost immediately.
To Get More Information On Ascorbic Acid Market - Request Free Sample Report
Ascorbic Acid Market Trends
-
Liposomal and other enhanced-bioavailability vitamin C formats are gaining ground in the supplement aisle, as brands look for ways to differentiate beyond standard tablets and capsules.
-
Branded, sustainability-certified ascorbic acid products are commanding real price premiums in pharmaceutical and premium supplement channels, as buyers pay for verified lower-emissions production and regulatory documentation.
-
Chinese producers, who account for the large majority of global fermentation-based output, continue to face periodic overcapacity, which keeps pricing volatile even as underlying demand grows steadily.
-
Clean-label and natural-source vitamin C, derived from acerola cherry and citrus rather than synthesized or fermented, is carving out a small but growing premium niche in cosmetics and specialty nutrition.
-
E-commerce is becoming a meaningful sales channel for both bulk ingredient buyers sourcing through B2B platforms and consumers buying finished vitamin C supplements directly online.
U.S. Ascorbic Acid Market Outlook
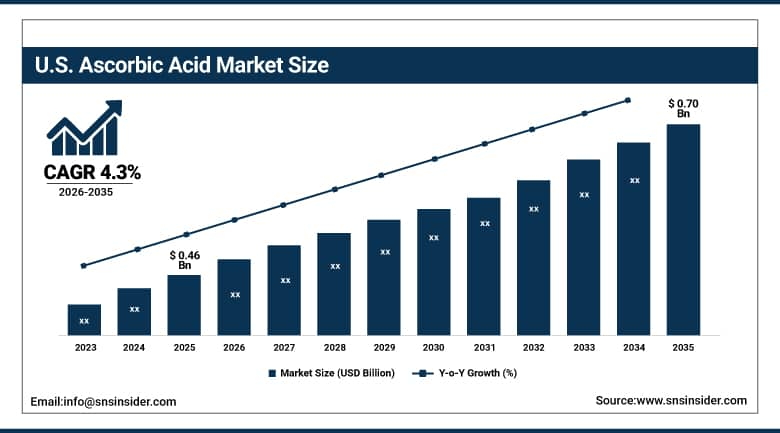
The U.S. Ascorbic Acid Market was valued at approximately USD 0.46 Billion in 2025 and is expected to reach approximately USD 0.70 Billion by 2035, growing at a CAGR of approximately 4.3%.
Demand in the United States is driven by a large dietary supplement industry, a well-established food and beverage fortification market, and pharmaceutical manufacturing that requires strict regulatory documentation most Chinese commodity suppliers can't easily provide. That documentation gap is a meaningful part of why branded, non-Chinese ascorbic acid continues to hold a premium position in the U.S. market despite its higher price. Domestic supplement brands and contract manufacturers add a further layer of steady demand, particularly for immune-health products that remain a consistent bestseller across U.S. retail and e-commerce channels.
DSM-Firmenich's Quali-C and BASF's ROVIMIX Stay-C 35 brands, both carrying United States Drug Master File filings, continue to command premium pricing in the U.S. market, where pharmaceutical and supplement manufacturers place a high value on the regulatory documentation and traceability that branded, non-Chinese sourced ascorbic acid provides.
Ascorbic Acid Market Segment Analysis
-
By Type, the L-Ascorbic Acid segment dominated the Ascorbic Acid Market with approximately 54.2% share in 2025, while the Sodium Ascorbate segment is the fastest growing with a CAGR of approximately 6.8%.
-
By Grade, the Food Grade segment dominated the Ascorbic Acid Market with approximately 46.3% share in 2025, while the Pharmaceutical Grade segment is the fastest growing with a CAGR of approximately 6.4%.
-
By Form, the Powder segment dominated the Ascorbic Acid Market with approximately 58.1% share in 2025, while the Granules segment is the fastest growing with a CAGR of approximately 6.2%.
-
By Application, the Food & Beverages segment dominated the Ascorbic Acid Market with approximately 34.4% share in 2025, while the Dietary Supplements segment is the fastest growing with a CAGR of approximately 7.1%.
-
By Packaging, the Bags segment dominated the Ascorbic Acid Market with approximately 42.5% share in 2025, while the Sachets segment is the fastest growing with a CAGR of approximately 7.4%.
-
By Distribution Channel, the Distributors & Wholesalers segment dominated the Ascorbic Acid Market with approximately 48.2% share in 2025, while the Online Retail segment is the fastest growing with a CAGR of approximately 8.2%.
By Type, L-ascorbic acid dominates, sodium ascorbate grows fastest
The standard form of ascorbic acid dominated the segment by type in 2025, serving as the basic variety for any application that just required a basic form of vitamin C. It remains the most economical form as compared to the mineral ascorbate salts and has many years of experience behind it; this makes it the key product line for both bulk customers and specialized manufacturers.
Sodium ascorbate has been showing the highest growth rate among products by type, thanks to increasing demand from the meat curing and processed foods sectors because of the neutral nature of this chemical and its ability to serve as an alternative to standard ascorbic acid in applications requiring neutral pH. The growth of sodium ascorbate is also being influenced by the need to reduce nitrites in processed meats because sodium ascorbate inhibits the creation of unwanted compounds and stabilizes color.
By Grade, food grade dominates, pharmaceutical grade grows fastest
Food grade ascorbic acid accounted for the largest share of the grade segment in 2025, reflecting its use across the largest end markets: food and beverage fortification and dietary supplements. Food grade material generally costs less to produce and certify than pharmaceutical grade, which keeps it the default choice anywhere strict pharmacopeia compliance isn't a hard requirement.
Pharmaceutical grade is the fastest-growing grade category as branded drug formulations, injectable vitamin C products, and clinical nutrition applications expand. Pharmaceutical grade material requires far more rigorous documentation, including drug master file filings in major markets, and that compliance burden keeps a meaningful price gap between pharmaceutical and food grade material even as both are chemically similar.
By Form, powder dominates, granules grow fastest
In 2025, powder continued to be the dominant physical form owing to its high stability and easy incorporation into dry mixes, along with reduced costs of transportation when compared to liquid products. Almost all food and beverages production companies utilize powder or crystalline products because they can be easily incorporated into existing dry product processing systems, and do not need additional liquid dosing systems.
Granules are expected to witness the fastest growth rate among the physical forms in terms of sales due to their superior flowability and compressibility during the process of high-speed manufacturing of tablets and capsules. Granulated ascorbic acid has an advantage over powder form, owing to its better flow characteristics and reduced dust formation in automation of the tableting process.
By Application, food & beverages dominates, dietary supplements grows fastest
Food and beverages accounted for the largest application share in 2025, spanning fortified juices, functional beverages, baked goods, and processed foods that use ascorbic acid as both a nutrient additive and a preservative. Its dual function, adding nutritional value while also protecting against oxidation and browning, makes it a particularly efficient ingredient for food manufacturers working with tight formulation budgets.
Dietary supplements are the fastest-growing application as consumer interest in immune health continues well beyond the pandemic-driven spike that first accelerated the category. Standalone vitamin C products, along with multivitamins and immune-support blends built around ascorbic acid, continue to sell steadily across both traditional retail and e-commerce channels, giving this application a broader and more durable growth base than a short-term health trend would typically produce.
By Packaging, bags dominate, sachets grow fastest
Bags held the largest packaging share in 2025, the standard format for bulk shipments to food, beverage, and supplement manufacturers who consume ascorbic acid in industrial quantities. Bulk bag packaging keeps per-unit shipping and handling costs low, which matters enormously to buyers purchasing metric tons of material at a time.
Sachets are growing fastest as single-serve and travel-friendly vitamin C formats gain popularity among consumers who want a precise, mess-free dose without a full bottle of tablets or powder. Direct-to-consumer supplement brands in particular have leaned into sachet packaging as a way to differentiate on convenience, even though sachets remain a small share of total packaging volume compared to bulk formats.
By Distribution Channel, distributors & wholesalers dominate, online retail grows fastest
Distributors and wholesalers occupied the biggest channel share in 2025 due to the extent of ascorbic acid business that goes through intermediation rather than direct manufacturer-buyer connections. Regional distributors manage inventory, handle import paperwork and offer technical assistance for mid-sized food producers and vitamin supplements makers which do not have enough purchase volumes to deal with manufacturers directly.
Online retail has been growing the fastest among other channels because of growth of both B2B ingredient marketplaces and direct consumer vitamin C supplements marketplace. Small purchasers of ascorbic acid prefer to buy the products via online industrial marketplaces rather than going through traditional distributor channels, while consumer-oriented e-commerce continues to take market shares of physical retail.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
58.0% |
|
North America |
United States |
79.0% |
|
Europe |
Germany |
24.0% |
|
Latin America |
Brazil |
41.0% |
|
Middle East & Africa |
Saudi Arabia |
27.0% |
Asia Pacific Ascorbic Acid Market Insights
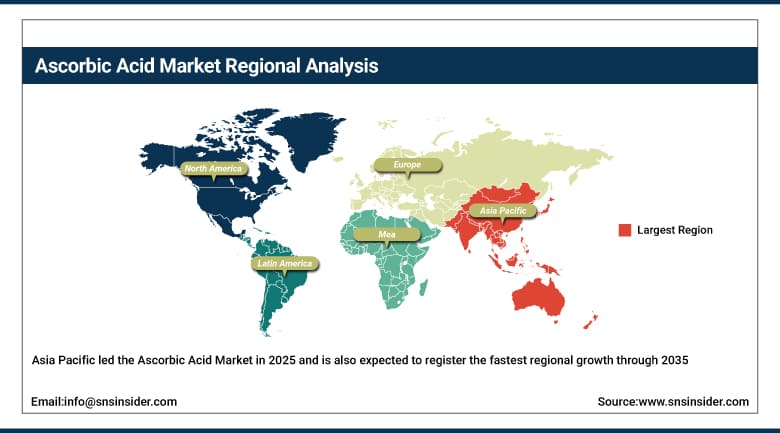
Asia Pacific led the Ascorbic Acid Market in 2025 and is also expected to register the fastest regional growth through 2035, a combination driven almost entirely by China's position as the world's dominant ascorbic acid manufacturing base. Chinese producers built on corn-glucose fermentation supply the large majority of global volume, and that manufacturing concentration alone gives the region its outsized share of both production and regional consumption.
India's expanding pharmaceutical and nutraceutical industries are adding meaningful demand growth on top of China's manufacturing scale, while Japan and South Korea contribute a smaller but more quality-focused market centered on premium supplements and cosmetics. Southeast Asian food and beverage fortification programs are a further growth driver, as regional governments push vitamin-fortified staple foods to address broader public health nutrition gaps.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Ascorbic Acid Market Insights
North America remains a significant ascorbic acid market, with the United States accounting for the large majority of regional demand across dietary supplements, food and beverage fortification, and pharmaceutical manufacturing. Strict regulatory documentation requirements for pharmaceutical-grade material give branded, non-Chinese suppliers a meaningful foothold in this region despite their higher price relative to Chinese commodity producers.
Canada contributes additional demand through its own food processing and supplement manufacturing base, while Mexico's market is expanding gradually alongside its packaged food and beverage sectors. Cross-border supply chains link much of North American demand together, with global ingredient producers typically serving all three markets through shared distribution networks.
Europe Ascorbic Acid Market Insights
Europe is characterized by a mature, steadily growing market for ascorbic acid, which is underpinned by a well-developed industry for food fortification and dietary supplements in Western Europe. Germany is the core market player with an active distribution network for ascorbic acid and significant manufacturing of foods and drugs, in which ascorbic acid is used as an ingredient.
France, Italy, and the UK account for considerable sales volumes too due to their food processing and dietary supplements manufacturing industries. Regulations regarding food additives labeling and pharmaceutical documentation in Europe influence supplier choices and create a preference for suppliers with the relevant certification capabilities.
MEA & Latin America Ascorbic Acid Market Insights
In the Middle East and Africa, there is a comparatively small but emerging ascorbic acid market, driven mainly by Saudi Arabia and the UAE due to their food processing and dietary supplement industries, both fueled by high levels of health awareness. The country that plays a central role in creating the demand for ascorbic acid in the whole region is South Africa due to the more developed food and pharmaceutical manufacturing industry than the neighboring countries.
Latin America is experiencing growing demand, and the leader in this regard is Brazil, thanks to the rising number of dietary supplements used along with the growing consumption of packaged foods among the urban population. Another factor that drives the demand for ascorbic acid in the region is its usage as an antioxidant by the manufacturers of beverages, such as juices and sports drinks.
Market Dynamics
Growth Drivers: Immune-health demand and food fortification expansion fueling adoption
Sustained consumer interest in immune health continues to be one of the clearest forces behind rising ascorbic acid demand, with vitamin C remaining one of the most recognized and trusted supplement ingredients across virtually every major market. That trust translates into steady repeat purchases, giving ascorbic acid a more durable demand base than many newer, less-established supplement ingredients enjoy.
Expanding food and beverage fortification programs, particularly in emerging markets working to address broader public health nutrition gaps, add a second major driver. Government-backed fortification initiatives in staple foods and beverages create a baseline level of institutional demand that isn't dependent on consumer purchasing decisions, giving ascorbic acid producers a more predictable revenue stream than pure consumer-market exposure would provide.
Restraints: Chinese production overcapacity and price volatility limiting margin stability
Overcapacity at Chinese fermentation-based manufacturers continues to cause price instability, hindering attempts by manufacturers to control supply to stabilize prices. The volatility of prices hinders both buyers and sellers from being able to plan ahead in anticipation of stability in long-term prices, and limits the ability of small-scale manufacturers to withstand low prices over extended periods of time.
In addition, the cost of corn/glucose as a feedstock becomes an additional factor contributing to volatility because economics of the manufacture of ascorbic acid depend heavily on agriculture commodities whose prices can change significantly depending on climatic and other factors. The absence of long-term agreements on feedstock is especially risky for manufacturers of ascorbic acid.
Opportunities: Branded sustainability positioning and emerging-market fortification programs opening new growth avenues
Branded, sustainability-certified ascorbic acid products offer producers a way to escape the commodity pricing pressure that dominates the Chinese-led segment of the market. Buyers in pharmaceutical and premium supplement channels are increasingly willing to pay a real premium for verified lower-emissions production, regulatory documentation, and supply chain traceability, giving Western producers a differentiated position worth defending.
Expanding food fortification programs across emerging markets represent a second significant opportunity, as governments in Asia, Africa, and Latin America push vitamin-fortified staple foods to address nutrition gaps in their populations. Producers that build strong relationships with fortification program administrators and government procurement channels early are positioned to capture a growing and relatively stable source of institutional demand as these programs scale.
Recent Developments:
-
August 2024: CSPC Pharmaceutical Group expanded its vitamin raw material export programs, targeting pharmaceutical customers across Southeast Asia and Europe.
-
November 2025: Seiwa Kasei launched iVC 3GA-green, a plant-derived 3-Glyceryl Ascorbate vitamin C derivative built on patented stabilization technology.
-
2024: Northeast Pharmaceutical Group, CSPC Pharmaceutical, and Shandong Luwei coordinated a series of production shutdowns aimed at stabilizing prices after a prolonged period of industry overcapacity.
-
2024: DSM-Firmenich and BASF expanded marketing of their sustainability-certified Quali-C and ROVIMIX Stay-C 35 product lines, citing significantly lower greenhouse gas emissions relative to standard fermentation-based production.
Ascorbic Acid Market Key Players
-
DSM-Firmenich N.V.
-
BASF SE
-
Northeast Pharmaceutical Group Co., Ltd.
-
CSPC Pharmaceutical Group Limited
-
Shandong Luwei Pharmaceutical Co., Ltd.
-
Merck KGaA
-
Glanbia plc
-
North China Pharmaceutical Co., Ltd.
-
Foodchem International Corporation
-
Henan Huaxing Pharmaceutical Co., Ltd.
-
Anhui Tiger Biotech Co., Ltd.
-
Shandong Tianli Pharmaceutical Co., Ltd.
-
Ningxia Qiyuan Pharmaceutical Co., Ltd.
-
Seiwa Kasei Co., Ltd.
Ascorbic Acid Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.15 Billion |
| Market Size by 2035 | USD 3.45 Billion |
| CAGR | CAGR of 4.85% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Type (Ascorbic Acid, Sodium Ascorbate, Calcium Ascorbate, Magnesium Ascorbate, Potassium Ascorbate, Others) • by Grade (Food Grade, Pharmaceutical Grade, Cosmetic Grade, Industrial Grade) • by Form (Powder, Granules, Crystals, Liquid, Others) • by Application (Food & Beverages, Dietary Supplements, Pharmaceuticals, Cosmetics & Personal Care, Animal Feed, Others) • by Packaging (Bags, Drums, Sachets, Others) • by Distribution Channel (Direct Sales, Distributors & Wholesalers, Online Retail) |
| Regional Analysis/Coverage | North America (US, Canada, Mexico), Europe (Eastern Europe [Poland, Romania, Hungary, Turkey, Rest of Eastern Europe] Western Europe] Germany, France, UK, Italy, Spain, Netherlands, Switzerland, Austria, Rest of Western Europe]), Asia Pacific (China, India, Japan, South Korea, Vietnam, Singapore, Australia, Rest of Asia Pacific), Middle East & Africa (Middle East [UAE, Egypt, Saudi Arabia, Qatar, Rest of Middle East], Africa [Nigeria, South Africa, Rest of Africa], Latin America (Brazil, Argentina, Colombia, Rest of Latin America) |
| Company Profiles | DSM-Firmenich N.V., BASF SE, Northeast Pharmaceutical Group Co., Ltd., CSPC Pharmaceutical Group Limited, Shandong Luwei Pharmaceutical Co., Ltd., Merck KGaA, Glanbia plc, North China Pharmaceutical Co., Ltd., Foodchem International Corporation, Henan Huaxing Pharmaceutical Co., Ltd., Anhui Tiger Biotech Co., Ltd., Shandong Tianli Pharmaceutical Co., Ltd., Ningxia Qiyuan Pharmaceutical Co., Ltd., Seiwa Kasei Co., Ltd. |
Frequently Asked Questions
The Ascorbic Acid Market is expected to grow at a CAGR of 4.85% from 2026 to 2035.
The Ascorbic Acid Market was valued at USD 2.15 Billion in 2025.
Sustained consumer demand for immune-health supplements and expanding food and beverage fortification programs, particularly across emerging markets.
Food & Beverages dominated with approximately 34.4% share in 2025, while Dietary Supplements is the fastest growing segment with a CAGR of approximately 7.1%.
Asia Pacific dominated the Ascorbic Acid Market in 2025 and is also the fastest-growing region.
