
Autonomous Vehicle ECU Market Report Scope & Overview:
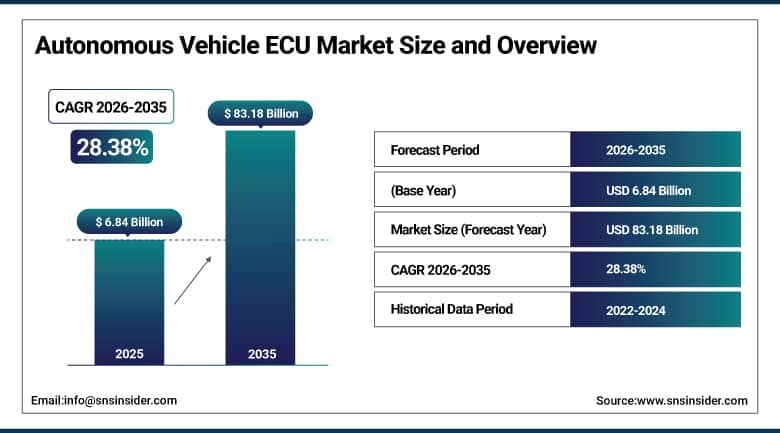
The Autonomous Vehicle ECU Market was valued at USD 6.84 Billion in 2025 and is expected to reach USD 83.18 Billion by 2035, growing at a CAGR of 28.38% from 2026-2035.
The Autonomous Vehicle ECU Market is undergoing architectural transformation as OEMs and semiconductors begin moving away from their current distributed and functional ECUs towards centralized and compute-heavy platforms, which will allow them to integrate autonomous driving, ADAS, digital cockpit, and infotainment functionalities into one system-on-chip. The reason for such a change is increasing computational requirements in light of the rising autonomy levels. Additionally, software payloads in these systems have reached hundreds of gigabytes due to advanced perception, planning, and control functionalities. Regional deployment differences occur because of China's fast march towards the adoption of Level 2 autonomy via urban Navigation on Autopilot systems while Europe is adopting ADAS systems through regulatory mandates for automatic emergency braking and driver monitoring.
In April 2025, NVIDIA launched its NVIDIA DRIVE AV Solution, an end-to-end Level 3 autonomous driving system unveiled at its GTC conference and internally codenamed Alpamayo, spanning model training, sensor simulation, traffic flow simulation, synthetic data generation, and model deployment within a single integrated software and hardware stack. The launch is followed by dual-Thor highway and urban Level 3 variants scheduled for 2027, illustrates how leading compute platform suppliers are increasingly competing on full-stack software and simulation capability.
To Get More Information On Autonomous Vehicle ECU Market - Request Free Sample Report
Autonomous Vehicle ECU Market Trends
- Accelerating shift from distributed, function-specific ECUs toward centralized, high-compute autonomous driving platforms.
- Rising automaker adoption of unified system-on-chip solutions integrating ADAS, cockpit, and infotainment functions.
- Growing vertical integration as OEMs including Tesla and XPeng develop proprietary autonomous driving chips.
- Expanding regulatory mandates in Europe requiring automatic emergency braking and driver monitoring on new vehicles.
- Increasing competition between full-stack compute platform suppliers offering integrated hardware and software solutions.
U.S. Autonomous Vehicle ECU Market Outlook
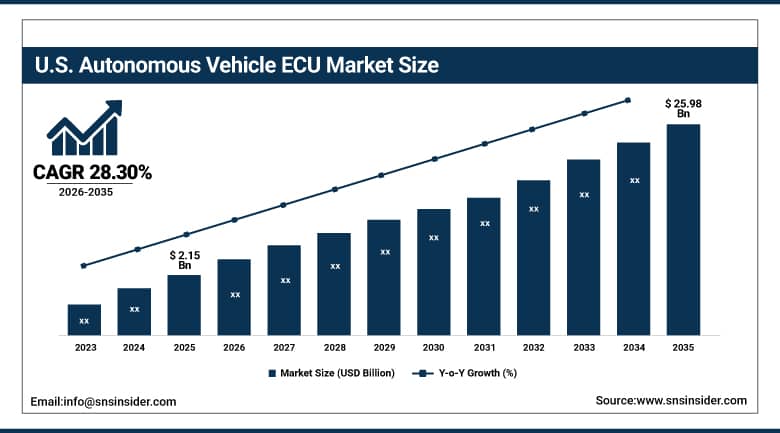
The U.S. Autonomous Vehicle ECU Market was valued at USD 2.15 Billion in 2025 and is expected to reach USD 25.98 Billion by 2035, growing at a CAGR of 28.30% from 2026-2035.
The U.S. Autonomous Vehicle ECU Market growth continues to be reinforced by substantial investment in smart transportation infrastructure and strong consumer acceptance of autonomous driving technology relative to other developed markets. Domestic demand is focused on highway pilot and driver assist, while both NVIDIA and Qualcomm have substantial domestic engineering efforts which are used to win designs at all the large automakers both domestically and internationally. Tesla’s vertically integrated strategy, where it uses its proprietary FSD computer hardware at scale across its car lineup, provides an alternative domestic competitive landscape compared to markets that have automakers dependent on third-party compute platforms.
In April 2026, Robert Bosch GmbH and Qualcomm expanded their strategic collaboration in the United States to develop production-ready ADAS vehicle computers. The companies are combining Bosch’s scalable ADAS integration platform with Qualcomm’s Snapdragon Ride platform, supporting sensor fusion, centralized computing, and advanced automated-driving functions. The collaboration has secured multiple customer programs, with the first vehicles from these programs expected on roads in 2028. The initiative supports the automotive industry’s shift toward consolidated vehicle-computing architectures and software-defined vehicles.
Autonomous Vehicle ECU Market Segment Analysis
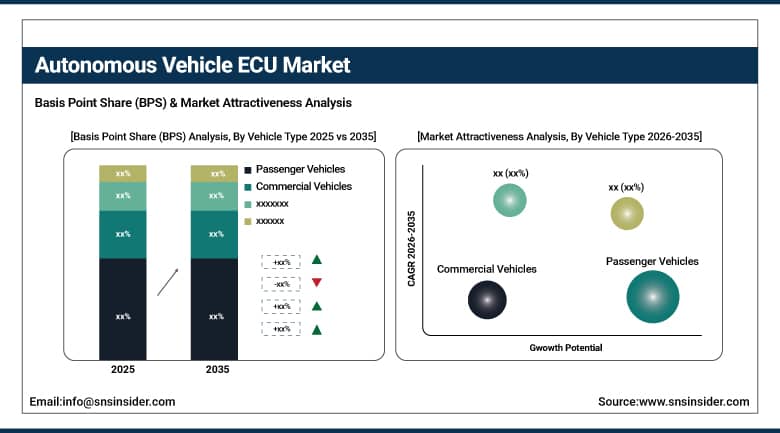
- By Vehicle Type, the Passenger Vehicles segment dominated the Autonomous Vehicle ECU Market with approximately 61.40% share in 2025, while the Commercial Vehicles segment is the fastest growing with a CAGR of approximately 30.85%.
- By ECU Type, the Advanced Driver Assistance Systems segment dominated the Autonomous Vehicle ECU Market with approximately 38.60% share in 2025, while the Autonomous Driving Systems segment is the fastest growing with a CAGR of approximately 31.50%.
- By Level of Automation, the Level 2 segment dominated the Autonomous Vehicle ECU Market with approximately 44.75% share in 2025, while the Level 4 segment is the fastest growing with a CAGR of approximately 34.20%.
- By Control Architecture, the Domain ECU segment dominated the Autonomous Vehicle ECU Market with approximately 56.80% share in 2025, while the Centralized ECU segment is the fastest growing with a CAGR of approximately 33.65%.
- By Distribution Channel, the OEM segment dominated the Autonomous Vehicle ECU Market with approximately 88.60% share in 2025, while the Aftermarket segment is the fastest growing with a CAGR of approximately 26.40%.
By Vehicle Type, Passenger Vehicles dominate, and Commercial Vehicles grow fastest
Passenger vehicles remain the dominant vehicle-type segment, characterized by significantly higher global production volumes than commercial vehicles and automakers' sustained investment in ADAS and autonomous driving features as a competitive differentiator across mass-market and premium vehicle lines alike.
Commercial vehicles are emerging rapidly as fleet operators and logistics companies pursue autonomous driving technology to address long-haul freight labor shortages and improve operational efficiency. As logistics operators prioritize hub-to-hub automation, this segment focuses strongly on high-compute ECU platforms engineered for the sustained highway operation and redundant safety systems that commercial freight applications demand.
By ECU Type, Advanced Driver Assistance Systems dominate, and Autonomous Driving Systems grow fastest
Advanced Driver Assistance Systems remain the dominant ECU type within the Autonomous Vehicle ECU Market, characterized by near-universal fitment of lane-keeping, emergency braking, and driver monitoring functions across mass-market vehicle models. This segment benefits from mandatory safety regulations and mature, cost-optimized 32-bit microcontroller architectures that balance performance against the price sensitivity of high-volume passenger vehicle platforms.
Autonomous Driving Systems are emerging rapidly as automakers pursue centralized, high-compute platforms integrating CPUs, GPUs, and neural processing units for end-to-end perception, planning, and actuation. As automakers prioritize over-the-air upgradability and cloud-based validation, this segment focuses strongly on positioning high-compute ECUs as the core enabler of Level 4 robo-taxi deployment and hub-to-hub freight pilot programs.
By Level of Automation, Level 2 dominates, and Level 4 grows fastest
Level 2 automation remains the dominant segment by level of automation, characterized by widespread deployment of combined adaptive cruise control and lane-centering functionality across mass-market vehicles, particularly as urban Navigation on Autopilot systems gain traction across price-competitive vehicle segments in China and beyond.
Level 4 automation is emerging rapidly as robo-taxi operators and hub-to-hub freight pilot programs deploy fully autonomous systems within defined operational domains. As mobility operators prioritize scalable, unsupervised operation, this segment focuses strongly on centralized compute platforms and redundant sensor architectures capable of meeting the safety validation requirements that unsupervised operation demands.
By Control Architecture, Domain ECU dominates, and Centralized ECU grows fastest
Domain ECU architectures remain dominant, characterized by their established presence across the current vehicle fleet, where individual electronic control units handle discrete functions connected via traditional vehicle communication networks refined over decades of automotive electronics development.
Centralized ECU architectures are emerging as the fastest-growing control architecture, driven by automakers' pursuit of lower bill-of-materials costs, reduced communication latency, and unified software platforms that support end-to-end foundation models and large language model integration. As vehicle software increasingly shares data and computing power across a single system-on-chip, this segment focuses strongly on chiplet-based scalability that allows a single compute platform to serve multiple vehicle trim levels.
By Distribution Channel, OEM dominates, and Aftermarket grows fastest
OEM remains the overwhelmingly dominant distribution channel, characterized by autonomous vehicle ECUs being deeply integrated into vehicle architecture at the point of original manufacture, a design constraint that makes aftermarket installation technically impractical for all but the most basic driver-assistance retrofits.
Aftermarket is emerging as the fastest-growing distribution channel, albeit from a small base, driven by fleet operators retrofitting older commercial vehicles with basic driver-assistance and telematics ECUs to improve safety without full vehicle replacement. As fleet operators prioritize incremental safety improvements, this segment focuses strongly on retrofit-compatible hardware that avoids the deep architectural integration required for full autonomous driving capability.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.60 |
|
Europe |
Germany |
30.40 |
|
Asia Pacific |
China |
48.75 |
|
Middle East & Africa |
United Arab Emirates |
33.90 |
|
Latin America |
Brazil |
42.60 |
North America Autonomous Vehicle ECU Market Insights
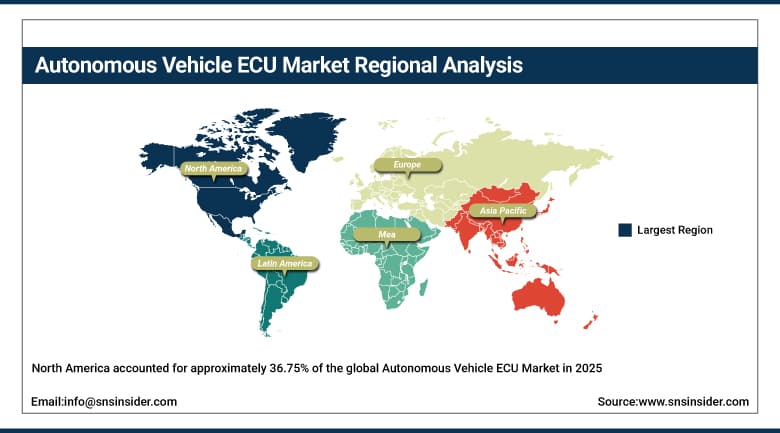
North America accounted for approximately 36.75% of the global Autonomous Vehicle ECU Market in 2025, remaining the largest regional market on the strength of substantial investment in smart transportation infrastructure and strong consumer acceptance of autonomous driving technology. The United States dominates regional demand, home to NVIDIA and Qualcomm, both of which maintain leading compute platform development operations, alongside Tesla's vertically integrated proprietary chip development.
The regional market is still highly profitable due to autonomous vehicles testing, highway pilots, and investment in advanced driver assistance and vehicle computing. But the growth of the market is slower compared to the Asia Pacific market where rapid expansion in urban autonomous driving takes place, especially in China. North America still gains due to technological development and commercialization in the US, whereas Canada is making its contributions through autonomous mobility pilots and connected transportations systems.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Autonomous Vehicle ECU Market Insights
Asia Pacific is projected to expand at a CAGR of approximately 33.10% from 2026 to 2035, the fastest of any region, driven by China's acceleration toward Level 2 dominance through urban Navigation on Autopilot systems and rapid design-win activity among both domestic and international compute platform suppliers. NVIDIA's Drive Thor platform secured design wins at Li Auto, ZEEKR, BYD, and XPeng, with the Lynk & Co 900 SUV becoming among the first vehicles equipped with the platform at its Q2 2025 China launch.
Local Chinese suppliers as well as Chinese OEMs, such as the Turing chip developed by XPeng in mass production from June 2025, represent a significant and growing portion of worldwide autonomous driving compute volumes. This is due to China’s efforts towards semiconductor independence in important automotive technologies. Japan and South Korea provide further regional demand due to their existing automotive electronics manufacturing capabilities.
Europe Autonomous Vehicle ECU Market Insights
Europe represents a significant Autonomous Vehicle ECU Market, shaped decisively by regulatory mandates requiring features such as automatic emergency braking and driver monitoring systems on new vehicles beginning in 2024 and 2025. Germany leads regional demand, anchored by its concentration of premium automakers and Tier 1 electronics suppliers, including Continental and ZF Friedrichshafen, both of which maintain extensive domestic ADAS engineering operations.
France and Italy contribute meaningful additional regional demand through their own vehicle manufacturing bases, while continued EU-wide enforcement of ADAS safety mandates is expected to sustain steady demand for compliant electronic control units throughout the forecast period.
MEA & Latin America Autonomous Vehicle ECU Market Insights
The Autonomous Vehicle ECU market in the Middle East & Africa region is seeing growth due to the GCC countries' investments in smart city and autonomous vehicle pilots; however, the UAE drives growth within the region due to its autonomous transportation plans for Dubai and smart infrastructure investments.
The Latin American autonomous vehicle ECU market is still in its initial stages of development, with Brazil being the main hub for this industry because of its existing automotive manufacturing capabilities and increased inclination toward importing vehicles that have advanced driver assistance systems.
Market Dynamics
Growth Drivers: Compute Platform Centralization and Regulatory ADAS Mandates
Increasing computation needs for increasingly automated vehicles represent the primary factor behind the growth of the Autonomous Vehicle ECU Market, since the trend towards shifting from separate and functionally-specific ECU systems to consolidated systems able to provide hundreds to thousands of tera-operations per second becomes evident in the automotive industry.
Regulatory mandates requiring specific ADAS safety features, including automatic emergency braking and driver monitoring systems now required on new vehicles across Europe, are reinforcing this driver by making ADAS-capable ECUs a mandatory rather than optional vehicle component. This regulatory-anchored baseline demand provides suppliers with predictable volume even independent of consumer demand for higher levels of autonomy.
Restraints: High Development Costs and Functional Safety Certification Complexity
The significant amount of investment in research and development necessary to develop and validate the high-compute autonomous driving platforms is still a relevant constraint as it has led to a limited number of potential suppliers that have the ability to afford development costs in the billions of dollars.
Functional safety certification complexity, including compliance with ISO 26262 automotive safety integrity levels, continues to extend development timelines and constrain how quickly new compute architectures can reach production, particularly for higher automation levels where the consequences of system failure carry substantially greater safety implications.
Opportunities: Software-Defined Vehicle Platforms and Commercial Freight Automation
The shift towards software-defined vehicles has been an immense opportunity for suppliers of compute platforms since the introduction of centralized ECUs that can be updated over the air enables automakers to earn software income throughout the vehicle’s lifetime instead of relying on initial hardware income only.
Continued development of hub-to-hub freight automation presents a further opportunity for suppliers offering high-compute ECU platforms engineered for sustained highway operation, as logistics operators facing persistent driver shortages increasingly view autonomous long-haul trucking as a viable near-term application for Level 4 automation technology outside the more complex urban operating environment.
Recent Developments:
- 2026: Qualcomm and Wayve announced a collaboration integrating Wayve AI Driver with Snapdragon Ride, creating a pre-integrated ADAS/automated-driving platform intended to support capabilities ranging from hands-off assistance toward eyes-off driving.
- 2026: TI introduced new automotive semiconductors for autonomous-driving applications, including TDA5 SoCs with up to 1,200 TOPS, an 8×8 4D imaging radar transceiver and 10BASE-T1S Ethernet PHY technology for vehicle edge nodes.
- 2026: XPeng announced plans to offer its electrical/electronic architecture, Turing AI chips, cockpit systems and advanced driver-assistance software to additional foreign automakers, expanding beyond its existing Volkswagen technology partnership.
Autonomous Vehicle ECU Market Key Players are:
- Tesla, Inc.
- NVIDIA Corporation
- Intel Corporation (Mobileye)
- Qualcomm Incorporated
- Aptiv PLC
- Robert Bosch GmbH
- Continental AG
- Denso Corporation
- Harman International Industries, Inc.
- ZF Friedrichshafen AG
- Renesas Electronics Corporation
- Hitachi Astemo, Ltd.
- Texas Instruments Incorporated
- Ambarella, Inc.
- Black Sesame Technologies
- XPeng Inc.
- Horizon Robotics
- Infineon Technologies AG
- Advanced Micro Devices, Inc.
- Waymo LLC
Autonomous Vehicle ECU Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 6.84 Billion |
| Market Size by 2035 | USD 83.18 Billion |
| CAGR | CAGR of 28.38% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By ECU Type (Advanced Driver Assistance Systems, Autonomous Driving Systems, Powertrain Control Systems, Telematics Systems, Others) • By Level of Automation (Level 1, Level 2, Level 3, Level 4, level 5) • By Control Architecture (Domain ECU, Distributed ECU, Centralized ECU, Hybrid Control) • By Vehicle Type (Passenger Vehicles, Commercial Vehicles, Public Transport, Last-Mile Delivery, Defense Vehicles) • By Distribution Channel (OEM, Aftermarket) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Tesla, Inc., NVIDIA Corporation, Intel Corporation (Mobileye), Qualcomm Incorporated, Aptiv PLC, Robert Bosch GmbH, Continental AG, Denso Corporation, Harman International Industries, Inc., ZF Friedrichshafen AG, Renesas Electronics Corporation, Hitachi Astemo, Ltd., Texas Instruments Incorporated, Ambarella, Inc., Black Sesame Technologies, XPeng Inc., Horizon Robotics, Infineon Technologies AG, Advanced Micro Devices, Inc., Waymo LLC |
Frequently Asked Questions
The escalating compute demands of higher vehicle automation levels, combined with regulatory ADAS mandates requiring automatic emergency braking and driver monitoring, is the major growth factor.
Key players in the Autonomous Vehicle ECU Market include Tesla, Inc., NVIDIA Corporation, Intel Corporation (Mobileye), Qualcomm Incorporated, and Aptiv PLC, among others.
Key opportunities lie in software-defined vehicle platforms that generate recurring software revenue through over-the-air updates, and in hub-to-hub freight automation addressing persistent commercial driver shortages.
By ECU Type, the Advanced Driver Assistance Systems segment dominated the Autonomous Vehicle ECU Market with approximately 38.60% share in 2025.
North America dominated the Autonomous Vehicle ECU Market with approximately 36.75% share in 2025, supported by substantial smart transportation infrastructure investment.
