
Brewing Enzymes Market Report Scope & Overview:
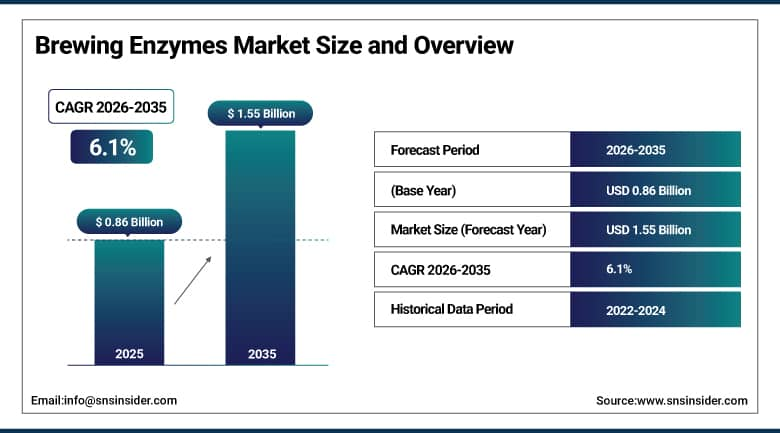
The Brewing Enzymes Market was valued at USD 0.86 Billion in 2025 and is expected to reach USD 1.55 Billion by 2035, growing at a CAGR of 6.1% from 2026-2035.
Brewing enzymes are specialized proteins added during mashing, fermentation, and filtration to break down starches, proteins, and beta-glucans faster and more predictably than natural malt enzymes alone can manage. Large breweries use them to raise fermentable extract yield and cut processing time, while craft brewers reach for them to hit specific flavor, clarity, or gluten-reduction targets that would otherwise require reformulating a recipe from scratch. Non-alcoholic and low-alcohol beer production leans on enzymes especially heavily.
In December 2025, Novozymes announced a partnership with a leading craft brewery to develop a new enzyme product aimed at enhancing flavor profiles in beer. The collaboration gives Novozymes direct feedback from brewers on how enzyme-driven flavor modification performs outside a lab setting, insight the company is using to refine its craft-focused product line.
To Get More Information On Brewing Enzymes Market - Request Free Sample Report
Brewing Enzymes Market Trends
-
Non-alcoholic and low-alcohol beer production is one of the fastest-growing draws on brewing enzymes, since removing alcohol without stripping flavor or body typically requires more precise enzymatic control than standard brewing.
-
Craft breweries are adopting enzyme blends to hit specific style targets, from hazy IPAs that need better protein stability to gluten-reduced beers that rely on protease to break down problematic proteins.
-
Enzyme suppliers are investing in temperature- and pH-tolerant formulations that hold up better across the wider range of grain bills and process conditions craft brewers experiment with compared to large industrial breweries.
-
Sustainability positioning is becoming a bigger part of how enzyme makers market their products, framing enzymatic processing as a way to cut water, energy, and raw material waste relative to older brewing methods.
-
Precision dosing and process-automation technology is spreading from large industrial breweries down into mid-size operations, letting more brewers fine-tune enzyme addition rather than relying on rule-of-thumb dosing.
U.S. Brewing Enzymes Market Outlook
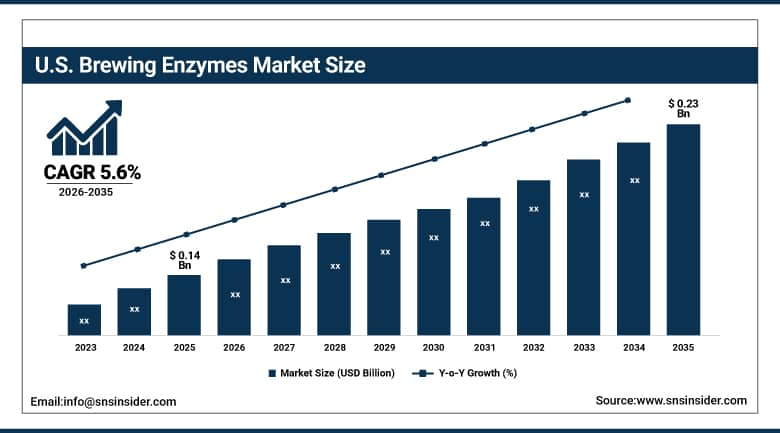
The U.S. Brewing Enzymes Market was valued at approximately USD 0.14 Billion in 2025 and is expected to reach approximately USD 0.23 Billion by 2035, growing at a CAGR of approximately 5.6%.
Craft brewing is the single biggest driver of U.S. enzyme demand, reflecting the country's unusually large and fragmented brewery base relative to more consolidated beer markets elsewhere. Thousands of small and mid-size breweries experiment constantly with new styles, and enzymes give them a faster, cheaper way to hit target flavor or clarity profiles than reformulating a recipe from the ground up. Rising interest in gluten-reduced and low-alcohol beer among U.S. consumers is adding a further layer of enzyme demand on top of the craft segment's baseline growth.
In November 2025, BASF launched a new line of brewing enzymes designed to improve fermentation efficiency and reduce waste, part of the company's ongoing investment in sustainable brewing solutions aimed at both large industrial customers and the growing U.S. craft segment.
Brewing Enzymes Market Segment Analysis
-
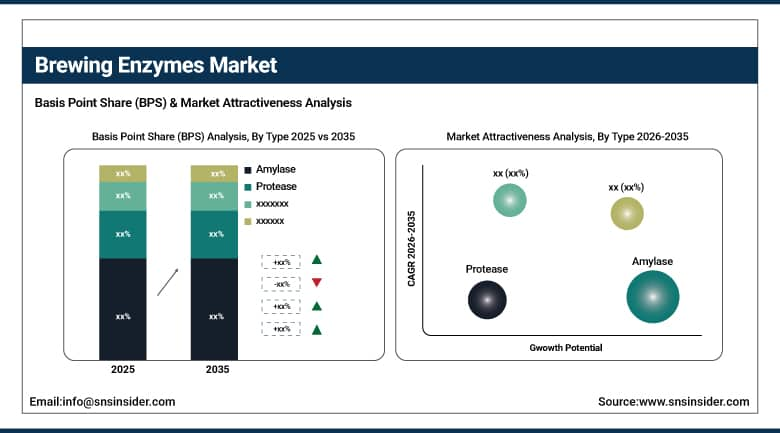
By Type, the Amylase segment dominated the Brewing Enzymes Market with approximately 34.2% share in 2025, while the Protease segment is the fastest growing with a CAGR of approximately 7.8%.
-
By Source, the Microbial segment dominated the Brewing Enzymes Market with approximately 78.4% share in 2025, while the Plant-Based segment is the fastest growing with a CAGR of approximately 7.4%.
-
By Process, the Wort Production segment dominated the Brewing Enzymes Market with approximately 36.5% share in 2025, while the Clarification & Filtration segment is the fastest growing with a CAGR of approximately 7.9%.
-
By Form, the Liquid segment dominated the Brewing Enzymes Market with approximately 63.8% share in 2025, while the Dry/Powder segment is the fastest growing with a CAGR of approximately 7.1%.
By Type, amylase dominates, protease grows fastest
Amylase held the largest share of the type segment in 2025, reflecting its central role in breaking down starches into fermentable sugars during mashing. It's especially valuable in regions where access to high-quality malt is limited, since amylase can help extract more fermentable sugar from a given grain bill than malt enzymes alone would manage. That efficiency gain matters across both large industrial breweries optimizing yield and craft operations working with unconventional grain bills.
Protease is growing faster than any other enzyme type as demand rises for haze-reduced and gluten-modified beer styles that require more precise protein breakdown than standard brewing achieves. Non-alcoholic and low-alcohol beer production, both expanding categories, also lean on protease to manage the protein and body characteristics that alcohol removal can otherwise disrupt. Brewers producing hazy or juice-forward styles are using protease in the opposite direction as well, carefully managing rather than eliminating haze-forming proteins.
By Source, microbial dominates, plant-based grows fastest
Microbial enzymes accounted for the large majority of the source segment in 2025, since microorganisms can be engineered and cultivated to produce specific enzymes at scale far more reliably than plant-based extraction allows. Microbial fermentation gives producers precise control over enzyme purity and activity levels, which matters to large breweries running standardized processes across multiple facilities and needing consistent performance batch after batch.
Plant-based enzymes are growing fastest as clean-label and traditional-process positioning gains traction among craft and specialty brewers marketing themselves around natural or heritage brewing methods. Though plant-based sources remain a small share of total volume, brewers targeting premium or artisanal positioning are increasingly willing to pay more for enzymes they can market as naturally derived, and that willingness is opening a growing niche for plant-based enzyme suppliers.
By Process, wort production dominates, clarification & filtration grows fastest
Wort production accounted for the largest process share in 2025, since mashing is where most enzyme activity, particularly amylase, does the heavy lifting of converting starch into fermentable sugar. Getting this stage right has an outsized effect on final beer quality and yield, which is why brewers of all sizes invest more heavily in wort-stage enzyme optimization than in any other single step of the process.
Clarification and filtration is the fastest-growing process category as demand rises for non-alcoholic and low-alcohol beers, which often need extra enzymatic help to maintain clarity and mouthfeel once alcohol content drops. Enzymes used at this stage break down haze-forming proteins and beta-glucans that would otherwise require more aggressive, flavor-altering filtration methods, giving brewers a gentler way to hit clarity targets without stripping out the character consumers expect.
By Form, liquid dominates, dry/powder grows fastest
Liquid formulations led the form segment in 2025, favored for their ease of handling and more precise dosing compared to dry powder. Most large-scale breweries are set up to handle liquid ingredients through existing dosing equipment, which makes liquid enzymes the path of least resistance for facilities that don't want to invest in new handling infrastructure just to switch enzyme formats.
Dry and powder formulations are growing fastest, largely on the strength of shelf stability and lower shipping costs, both of which matter more to craft breweries and export-oriented suppliers than to large domestic operations with steady liquid-handling infrastructure already in place. Powder formats also hold up better during long-distance shipping to regions with less developed cold-chain logistics, which is helping dry enzyme formulations gain ground in parts of Asia Pacific and Latin America.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.0% |
|
Europe |
Germany |
26.0% |
|
Asia Pacific |
China |
36.0% |
|
Middle East & Africa |
South Africa |
33.0% |
|
Latin America |
Brazil |
41.0% |
Europe Brewing Enzymes Market Insights
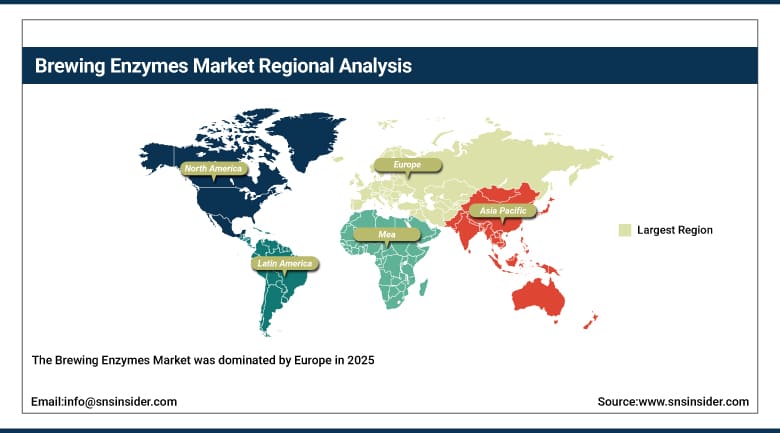
The Brewing Enzymes Market was dominated by Europe in 2025 owing to the rich brewing legacy of Germany, along with the presence of a large number of industrial and small breweries. Europe has been engaged in beer brewing since a very long time and the rise of craft beer market is driving the growth of enzyme suppliers in the market as they can sell their enzymes to a vast array of customers, ranging from old breweries to new ones trying out new forms of beers.
The demand in the UK, Belgium, and Czech Republic cannot be overlooked because these countries have a rich brewing culture and there has been an increased demand for process optimization using enzymes in these countries. Europe is ahead of others when it comes to regulation regarding enzyme use in food and beverage manufacturing industries.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Brewing Enzymes Market Insights
Asia Pacific is expected to post the fastest regional growth through 2035, powered by a rapidly expanding craft beer scene across China, India, and Southeast Asia alongside steady growth in large-scale industrial beer production. Rising disposable incomes and growing interest in Western-style beer among younger consumers are driving much of this expansion, particularly in urban centers where craft breweries have multiplied over the past several years.
China's large industrial brewing base gives the region substantial baseline demand on top of craft segment growth, while Japan and South Korea contribute a smaller but more mature market already accustomed to enzyme-assisted brewing. India's brewing industry is drawing growing interest from global enzyme suppliers looking to establish local distribution and technical support ahead of expected demand growth.
North America Brewing Enzymes Market Insights
North America remains a substantial brewing enzymes market, with the United States accounting for the large majority of regional demand thanks to its unusually large and fragmented craft brewery base. Thousands of small and mid-size breweries across the country create a level of enzyme demand diversity that few other markets can match, since each brewery tends to have its own specific style and process requirements.
Canada contributes additional demand through its own growing craft brewing sector, while Mexico's market is expanding gradually alongside its large industrial beer producers. Cross-border supply relationships mean many enzyme suppliers serve the U.S., Canadian, and Mexican markets through shared distribution networks rather than fully separate regional operations.
MEA & Latin America Brewing Enzymes Market Insights
The Middle East and Africa represent a smaller, more concentrated brewing enzymes market, with South Africa anchoring regional demand through its well-established commercial brewing industry. Growth elsewhere in the region remains limited by cultural and regulatory restrictions on alcohol production and sale in several markets, which keeps the addressable base narrower than in most other regions.
Latin America is seeing steady adoption led by Brazil, where both large industrial breweries and a growing craft segment are turning to enzymes to improve yield and consistency. Argentina and Colombia contribute smaller but growing shares of regional demand, tied to expanding craft brewing scenes in each country's major urban centers.
Market Dynamics
Growth Drivers: Non-alcoholic beer growth and craft brewing expansion fueling enzyme adoption
The rapid growth of non-alcoholic and low-alcohol beer is one of the clearest forces behind rising enzyme demand, since producing a beer that tastes and feels like a full-strength product without the alcohol typically requires more precise enzymatic control over fermentation and clarity than standard brewing does. As more mainstream and craft breweries add non-alcoholic lines to meet growing consumer demand, that enzyme intensity is spreading well beyond the specialty producers who pioneered the category.
Continued growth in craft and specialty brewing adds a second major driver, as smaller breweries use enzymes to hit specific flavor, clarity, and style targets without the cost and time of reformulating recipes from scratch. Rising raw material costs are pushing both large and small brewers toward enzymes that improve fermentable extract yield, since getting more usable sugar out of the same amount of malt directly improves margins in a cost environment that keeps getting tighter.
Restraints: Regulatory complexity and consumer skepticism around processing aids limiting broader adoption
Enzyme approval and labeling requirements vary considerably across markets, and that regulatory patchwork adds cost and delay for suppliers trying to introduce new formulations globally rather than market by market. Smaller enzyme producers in particular can struggle to absorb the compliance costs required to enter multiple regulatory jurisdictions at once, which limits how quickly new products reach brewers outside a supplier's home market.
A segment of consumers and traditionalist brewers also remain skeptical of processing aids generally, associating enzyme use with a departure from traditional brewing methods that some regard as central to a beer's authenticity. That perception is strongest in regions with strong brewing heritage and purity-law traditions, and it can limit enzyme adoption among brewers marketing themselves around traditional or heritage positioning even when enzymes could genuinely improve their process.
Opportunities: Expanding non-alcoholic and precision fermentation applications opening new growth avenues
The continued global expansion of non-alcoholic and low-alcohol beer gives enzyme suppliers a large and still-growing application that barely existed as a meaningful category a decade ago. As more breweries of every size add alcohol-free lines to their portfolios, the enzyme intensity required to make those products taste right should keep pulling demand well ahead of overall beer volume growth.
Precision fermentation and next-generation enzyme engineering offer a second avenue, letting suppliers develop enzyme blends tailored to specific grain bills, beer styles, or processing conditions rather than selling one-size-fits-all formulations. Enzyme makers that build genuine technical partnerships with craft brewers, rather than just selling a commodity product, are positioned to capture premium pricing and longer-term customer relationships as the craft segment continues to mature.
Recent Developments:
-
August 2025: DSM-Firmenich launched "BREWCATALYST Pro," a new enzyme solution built for higher sugar extract yield and reduced mash time.
-
August 2025: AB Enzymes upgraded its glucanase portfolio with a high-performance liquid formulation aimed at filtration improvements for craft brewers.
-
September 2025: Novozymes expanded its Asia Pacific portfolio with eco-friendly mashing enzyme kits aimed at craft brewers across China and India.
-
October 2025: Amano Enzyme released a specialized hemicellulase for sake-and-beer hybrid brewing in Japan, aimed at improving yield and clarity.
Brewing Enzymes Market Key Players
-
Novozymes A/S
-
DSM-Firmenich
-
BASF SE
-
DuPont de Nemours, Inc.
-
AB Enzymes GmbH
-
Lallemand Inc.
-
Kerry Group plc
-
Advanced Enzyme Technologies Limited
-
Amano Enzyme Inc.
-
Chr. Hansen Holding A/S
-
Enzyme Development Corporation
-
SternEnzym GmbH & Co. KG
-
Angel Yeast Co., Ltd.
-
MetGen Oy
-
Sunson Industry Group Co., Ltd.
Brewing Enzymes Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 0.86 Billion |
| Market Size by 2035 | USD 1.55 Billion |
| CAGR | CAGR of 6.1% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Type (Amylase, Beta-Glucanase, Protease, Xylanase, Others) • by Source (Microbial, Plant-Based) • by Process (Wort Production, Fermentation Process, Clarification & Filtration, Others) • by Form (Liquid, Dry/Powder |
| Regional Analysis/Coverage | North America (US, Canada, Mexico), Europe (Eastern Europe [Poland, Romania, Hungary, Turkey, Rest of Eastern Europe] Western Europe] Germany, France, UK, Italy, Spain, Netherlands, Switzerland, Austria, Rest of Western Europe]), Asia Pacific (China, India, Japan, South Korea, Vietnam, Singapore, Australia, Rest of Asia Pacific), Middle East & Africa (Middle East [UAE, Egypt, Saudi Arabia, Qatar, Rest of Middle East], Africa [Nigeria, South Africa, Rest of Africa], Latin America (Brazil, Argentina, Colombia, Rest of Latin America) |
| Company Profiles | Novozymes A/S, DSM-Firmenich, BASF SE, DuPont de Nemours, Inc., AB Enzymes GmbH, Lallemand Inc., Kerry Group plc, Advanced Enzyme Technologies Limited, Amano Enzyme Inc., Chr. Hansen Holding A/S, Enzyme Development Corporation, SternEnzym GmbH & Co. KG, Angel Yeast Co., Ltd., MetGen Oy, Sunson Industry Group Co., Ltd. |

Frequently Asked Questions
The Brewing Enzymes Market is expected to grow at a CAGR of 6.1% from 2026 to 2035.
The Brewing Enzymes Market was valued at USD 0.86 Billion in 2025.
Rapid growth in non-alcoholic and low-alcohol beer production, alongside continued expansion of craft and specialty brewing.
Wort Production dominated with approximately 36.5% share in 2025, while Clarification & Filtration is the fastest growing segment with a CAGR of approximately 7.9%.
Europe dominated the Brewing Enzymes Market in 2025, while Asia Pacific is the fastest-growing region.
