
Dehydrated Potato Market Report Scope & Overview:
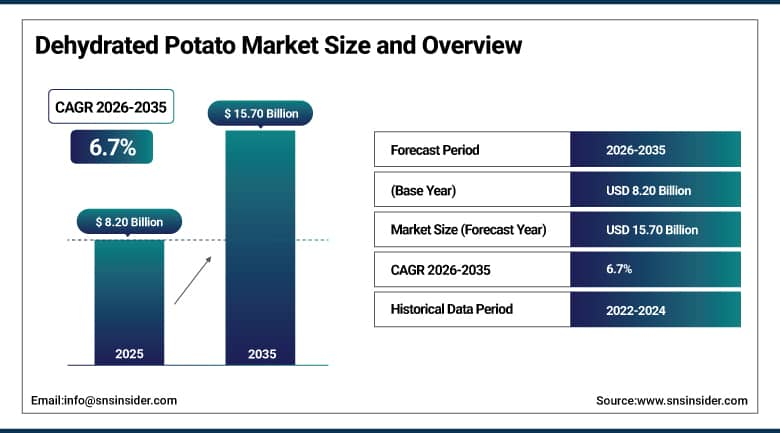
The Dehydrated Potato Market was valued at USD 8.20 Billion in 2025 and is expected to reach USD 15.70 Billion by 2035, growing at a CAGR of 6.7% from 2026–2035.
Fresh potatoes are washed, cooked, and stripped of nearly all their moisture, then reduced to flakes, granules, powder, or diced pieces that hold for months without refrigeration. Foodservice kitchens use dehydrated potato as a labor-saving base for soups, gravies, and bakery fillings, while packaged food manufacturers rely on it to keep texture consistent across production runs that fresh input can't match. Rising raw potato costs and seasonal supply gaps are steering more processors toward dehydration each year.
In June 2024, McCain Foods expanded its network of innovation hub farms across North America, part of a broader push to apply regenerative agriculture practices across its full potato-growing footprint by 2030. The initiative doesn't target dehydrated potato specifically, but it illustrates how upstream sourcing decisions at the largest processors are increasingly shaped by sustainability commitments rather than yield alone.
To Get More Information On Dehydrated Potato Market - Request Free Sample Report
Dehydrated Potato Market Trends
-
Foodservice chains are replacing scratch-made mashed potato and soup bases with dehydrated formats to cut prep labor and reduce waste, a shift that has accelerated as minimum wage increases in several major markets made in-house peeling and cooking noticeably more expensive.
-
Clean-label and non-GMO positioning is moving from a niche claim toward standard practice among mid-size processors, as retailers push ingredient lists that consumers can read without a food science background.
-
Manufacturers are investing in gentler drying methods, including vacuum microwave and pulsed electric field dehydration, to preserve texture and nutrient content that older drum-drying processes tend to strip away.
-
Private label retailers are expanding their own dehydrated potato lines, particularly in instant mashed potato and soup mix categories, putting pricing pressure on established branded players.
-
Demand for organic dehydrated potato ingredients is growing faster than the conventional base, though it remains a small share of total volume, as bakery and snack formulators look for cleaner-label alternatives to conventional starches.
U.S. Dehydrated Potato Market Outlook
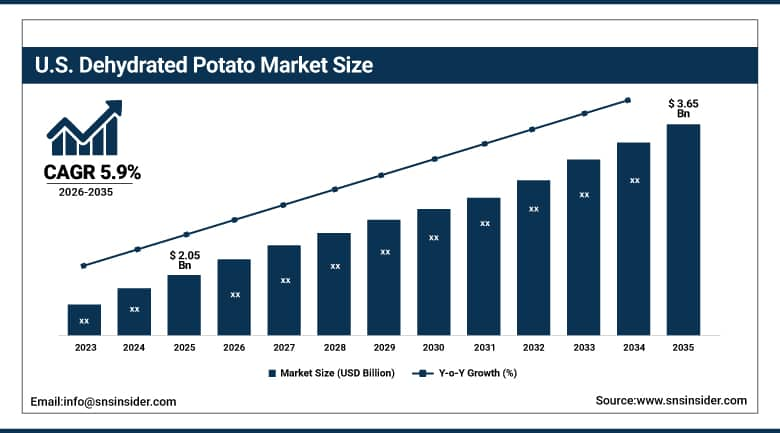
The U.S. Dehydrated Potato Market was valued at approximately USD 2.05 Billion in 2025 and is expected to reach approximately USD 3.65 Billion by 2035, growing at a CAGR of approximately 5.9%.
The United States anchors global dehydrated potato supply, backed by Idaho and the broader Pacific Northwest's concentration of potato acreage and processing infrastructure built up over decades. Large-scale foodservice chains and institutional buyers, from school districts to hospital systems, rely on dehydrated formats for menu consistency and long shelf life, and that institutional demand tends to hold steady even when consumer grocery spending softens. Domestic private-label growth and steady export volumes to Latin America add further support, while a mature grower-processor network keeps supply reliable through seasonal swings in fresh potato pricing.
In 2025, Idahoan Foods introduced a new line of organic dehydrated potato flakes aimed at retail shoppers looking for a cleaner ingredient panel, extending a brand best known for its instant mashed potato cups into a segment it had largely left to smaller natural-foods players.
Dehydrated Potato Market Segment Analysis
-
By Form, the Flakes segment dominated the Dehydrated Potato Market with approximately 38.4% share in 2025, while the Granules segment is the fastest growing with a CAGR of approximately 7.9%.
-
By Application, the Food Processing segment dominated the Dehydrated Potato Market with approximately 41.2% share in 2025, while the Foodservice segment is the fastest growing with a CAGR of approximately 8.1%.
-
By Nature, the Conventional segment dominated the Dehydrated Potato Market with approximately 85.6% share in 2025, while the Organic segment is the fastest growing with a CAGR of approximately 9.6%.
-
By Distribution Channel, the Direct/Institutional Sales segment dominated the Dehydrated Potato Market with approximately 46.8% share in 2025, while the Online Retail segment is the fastest growing with a CAGR of approximately 9.3%.
By Form, flakes dominate, granules grow fastest
Flakes held the largest share of the form segment in 2025, built on decades of use in instant mashed potato products, bakery mixes, and as a thickening base in soups and sauces. Their appeal comes down to rehydration behavior: flakes reconstitute quickly into a smooth, familiar texture that home cooks and foodservice kitchens alike can work with without much technique, which keeps them the default choice across a wide range of applications. Established supply relationships between flake producers and large packaged food buyers also reinforce this lead, since switching a formulation to a different form usually means re-testing texture and cost across an entire product line.
Granules are growing faster than any other form as foodservice operators and ready-meal producers favor their coarser, more distinct texture over the smoother finish flakes provide. That texture holds up better in dishes meant to look and feel closer to freshly mashed potato, and granules tend to blend more predictably into large-batch cooking equipment, which matters to institutional kitchens producing hundreds of servings at once. Ready-meal and quick-service menus built around a homestyle mashed potato offering are increasingly specifying granules by name, and that preference is filtering down from national chains to smaller regional operators as well.
By Application, food processing dominates, foodservice grows fastest
Food processing, covering packaged soups, sauces, snack coatings, and bakery inputs, accounted for the largest share of application demand in 2025. Manufacturers favor dehydrated potato here because it behaves consistently batch after batch in a way fresh potato simply can't, which matters once a product is running on an automated line rather than being cooked to order. Formulators also value how easily dehydrated potato blends with other dry ingredients, letting them build finished mixes that need only water or a short cook step before reaching the consumer.
Foodservice is the fastest-growing application as restaurant chains and institutional caterers look to cut prep labor and standardize output across locations. Rising minimum wages in several major markets have made in-house peeling, boiling, and mashing meaningfully more expensive relative to a dehydrated base that a line cook can reconstitute in minutes, and that math is pushing adoption further into mid-size regional chains that previously stuck with fresh potato. Menu consistency across multi-location chains is a further factor, since a dehydrated base removes the variability that comes from different kitchens cooking fresh potato to slightly different standards.
By Nature, conventional dominates, organic grows fastest
Conventional dehydrated potato continues to account for the overwhelming majority of volume, reflecting both cost sensitivity among large-volume buyers and the fact that organic potato acreage remains a small fraction of total planted area worldwide. Bulk buyers in foodservice and food processing are generally more focused on consistent supply and price than on organic certification, and most large-scale contracts are still written and priced around conventional raw material. That pricing gap alone keeps organic a secondary consideration for buyers running on thin processing margins.
Organic is growing off a small base but at a noticeably faster clip, driven by bakery and snack brands positioning themselves around cleaner labels and by a subset of retail shoppers willing to pay a premium for instant mashed potato and soup products without conventional inputs. Supply remains the binding constraint here more than demand, since certified organic potato acreage takes years to scale, and processors that have secured reliable organic sourcing are using that as a genuine point of differentiation against larger conventional competitors.
By Distribution Channel, direct/institutional sales dominate, online retail grows fastest
Direct and institutional sales, meaning bulk contracts between processors and food manufacturers, foodservice distributors, and large retail private-label programs, made up the largest distribution channel in 2025. Most dehydrated potato never reaches a store shelf as a standalone product; it arrives at a manufacturing plant or a distribution center as a bulk ingredient headed into someone else's finished product. These contracts tend to run on multi-year terms with pricing tied to raw potato costs, which gives large buyers and established processors a level of planning certainty that smaller, spot-market channels can't offer.
Online retail is expanding faster than any other channel, though still from a modest base, as direct-to-consumer brands sell shelf-stable mashed potato and soup mixes through e-commerce platforms and as long-term-storage food retailers build dedicated online storefronts. The category benefits from dehydrated potato's long shelf life, which removes much of the logistics friction that otherwise limits online grocery for perishable goods. Subscription-based emergency food and outdoor recreation brands have also embraced the channel, giving dehydrated potato a retail presence well beyond the traditional supermarket aisle.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
78.0% |
|
Europe |
Germany |
24.0% |
|
Asia Pacific |
China |
41.0% |
|
Middle East & Africa |
Saudi Arabia |
28.0% |
|
Latin America |
Brazil |
38.0% |
North America Dehydrated Potato Market Insights
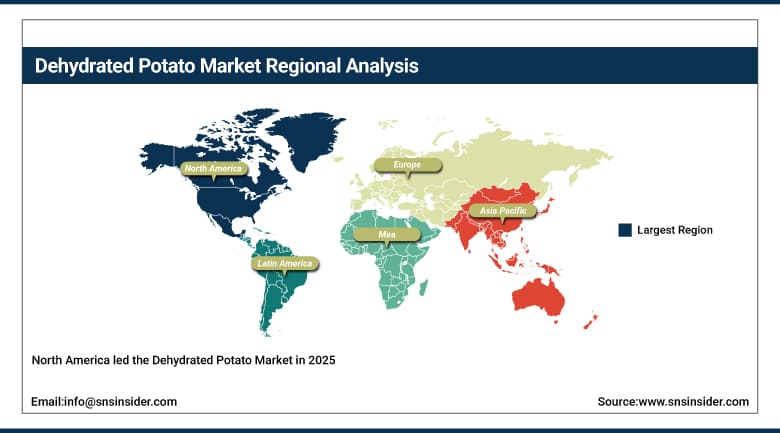
North America led the Dehydrated Potato Market in 2025, anchored by the United States' deep processing base in Idaho, Washington, and the broader Pacific Northwest. Well-established relationships between growers, processors, and major foodservice and packaged-food buyers give the region a level of supply-chain maturity that newer producing regions haven't matched yet, and that stability keeps large buyers loyal even when input costs rise. Multi-year contract structures common across the region further reduce the price volatility that can otherwise disrupt production planning for large food manufacturers.
Canada contributes a meaningful share through its own processing capacity and close trade ties with the U.S. market, with several Canadian facilities feeding both domestic foodservice demand and cross-border exports. Mexico's demand is growing steadily as its packaged food and foodservice sectors expand, much of it still served through imports from north of the border rather than domestic dehydration capacity, though that balance is expected to shift gradually as local processing investment increases.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Dehydrated Potato Market Insights
Asia Pacific is expected to post the fastest regional growth through 2035, powered by China and India's position as two of the largest raw potato producers in the world alongside rapidly growing processed-food sectors. Rising urban incomes and busier lifestyles are pushing more households toward packaged and convenience foods that lean on dehydrated potato as a standardized ingredient, and that shift is happening across a much larger population base than in mature Western markets.
India in particular is drawing fresh investment from global processors setting up local capacity rather than relying on imports, a shift tied to contract farming arrangements that give companies more control over raw potato quality and price. Japan and South Korea round out regional demand with more mature, quality-focused markets already well accustomed to processed potato products, while Southeast Asian foodservice chains are adopting dehydrated formats at a pace that mirrors earlier growth in North America and Europe.
Europe Dehydrated Potato Market Insights
Europe remains a substantial, if slower-growing, market for dehydrated potato, supported by a long-established potato-processing industry and a foodservice sector that has used dehydrated ingredients for decades. Germany is the largest single market in the region, home to major processors with deep roots in potato starch and flake production, and its manufacturing base supplies both domestic demand and a significant volume of exports to neighboring countries.
The Netherlands, Belgium, and France contribute meaningful volume as well, given their concentration of potato processing infrastructure built originally around frozen potato exports, much of which has extended naturally into dehydrated product lines. Regulatory attention to clean-label claims and additive use shapes product formulation across the region more than it does in most other markets, pushing European processors toward simpler ingredient lists earlier than their counterparts elsewhere.
MEA & Latin America Dehydrated Potato Market Insights
The Middle East and Africa represent a smaller but steadily developing market, with Saudi Arabia and the UAE driving demand through growing foodservice and hospitality sectors tied to tourism and urban development, while South Africa anchors demand across the rest of the continent through its more established food-processing base. Import dependence remains high across most of the region, since local potato processing infrastructure is still limited outside a handful of markets.
Latin America is seeing rising adoption led by Brazil, where packaged food manufacturers are increasingly turning to dehydrated potato to manage costs and shelf life across a large and logistically challenging domestic market. Argentina, with its own strong potato-growing tradition, contributes a secondary but growing share of regional demand, and both markets are drawing gradual interest from global processors looking to establish a foothold ahead of broader regional growth.
Market Dynamics
Growth Drivers: Foodservice labor costs and demand for shelf-stable convenience ingredients fueling adoption
Rising labor costs across foodservice and institutional catering are one of the clearest forces behind dehydrated potato adoption, since a dehydrated base cuts out the peeling, boiling, and mashing labor that fresh potato requires without much sacrifice in final texture once reconstituted properly. That math becomes more compelling every time minimum wages move higher in a major market, and it's pushing adoption further down into mid-size regional chains that once considered dehydrated potato a lower-quality shortcut.
Extended shelf life and simplified storage add a second layer of appeal, particularly for buyers managing supply chains across large geographies or through seasons when fresh potato quality and pricing swing considerably. Packaged food manufacturers also value the batch-to-batch consistency dehydrated potato offers, something fresh input can't reliably match once a production line is running at scale. Growing demand for ready-to-eat and semi-prepared meals across both developed and emerging markets is reinforcing this shift, giving processors a broader base of buyers than the category has historically served.
Restraints: Consumer preference for fresh and frozen formats limiting further penetration
A meaningful share of households and even some foodservice operators continue to prefer fresh or frozen potato for direct meal preparation, associating dehydrated products with a processed, less authentic eating experience. That perception is slow to shift, and it caps how far dehydrated potato can penetrate categories where fresh potato remains culturally and commercially entrenched, particularly in markets with strong home-cooking traditions.
Raw potato price volatility also weighs on processor margins, since dehydration plants generally can't pass sudden input cost swings through to buyers locked into fixed-price contracts. Energy-intensive drying processes add a further cost pressure, especially in regions where electricity and natural gas prices have risen sharply in recent years, and smaller processors without long-term energy contracts are the most exposed to these swings.
Opportunities: Expanding processed-food and organic segments opening new growth avenues
The continued global expansion of packaged and convenience foods, especially across Asia Pacific and Latin America, gives dehydrated potato processors a growing base of manufacturers to sell into as more households shift away from cooking every meal from scratch. That shift is happening earlier in the income curve than it did in Western markets, giving processors a longer runway of growth to work with.
Organic and clean-label positioning offers a second avenue, letting processors capture a premium from brands and retailers competing on ingredient transparency even as that segment remains a small share of total volume today. Newer drying technologies that improve texture and nutrient retention also open the door to premium, quality-differentiated products that can command better margins than commodity flakes and powder, giving established processors a way to compete on something other than price alone.
Recent Developments:
-
2025: Royal Avebe completed its acquisition of Solan, extending its ingredient portfolio beyond potato starches into flakes and granules and adding processing assets in Poland and Sweden.
-
2025: Emsland Group entered a distribution partnership with UniBourne Food Ingredients to expand availability of its dehydrated potato ingredients across India.
-
2025: Lamb Weston commissioned a new dehydration facility in Washington State with an annual processing capacity of approximately 300,000 metric tons.
-
2025: McCain Foods committed close to USD 480 million toward a new food-processing facility in Madhya Pradesh, India, built around long-term contract farming arrangements with regional growers.
Dehydrated Potato Market Key Players
-
McCain Foods Limited
-
Lamb Weston Holdings, Inc.
-
The J.R. Simplot Company
-
Aviko B.V.
-
Emsland Group
-
Idahoan Foods, LLC
-
Basic American Foods
-
Idaho Pacific Corporation
-
Agrana Group
-
Augason Farms
-
Pacific Valley Foods Inc.
-
Farm Frites International B.V.
-
Intersnack Group
-
Royal Avebe
-
Rixona B.V.
Dehydrated Potato Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 8.20 Billion |
| Market Size by 2035 | USD 15.70 Billion |
| CAGR | CAGR of 6.7% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Form (Flakes, Granules, Powder, Dices & Slices, Others) • by Application (Food Processing, Foodservice, Retail & Household, Snacks & Bakery, Others) • by Nature (Conventional, Organic) • by Distribution Channel (Direct/Institutional Sales, Supermarkets & Hypermarkets, Convenience Stores, Online Retail) |
| Regional Analysis/Coverage | North America (US, Canada, Mexico), Europe (Eastern Europe [Poland, Romania, Hungary, Turkey, Rest of Eastern Europe] Western Europe] Germany, France, UK, Italy, Spain, Netherlands, Switzerland, Austria, Rest of Western Europe]), Asia Pacific (China, India, Japan, South Korea, Vietnam, Singapore, Australia, Rest of Asia Pacific), Middle East & Africa (Middle East [UAE, Egypt, Saudi Arabia, Qatar, Rest of Middle East], Africa [Nigeria, South Africa, Rest of Africa], Latin America (Brazil, Argentina, Colombia, Rest of Latin America) |
| Company Profiles | McCain Foods Limited, Lamb Weston Holdings, Inc., The J.R. Simplot Company, Aviko B.V., Emsland Group, Idahoan Foods, LLC, Basic American Foods, Idaho Pacific Corporation, Agrana Group, Augason Farms, Pacific Valley Foods Inc., Farm Frites International B.V., Intersnack Group, Royal Avebe, Rixona B.V. |
Frequently Asked Questions
The Dehydrated Potato Market is expected to grow at a CAGR of 6.7% from 2026 to 2035.
The Dehydrated Potato Market was valued at USD 8.20 Billion in 2025.
Rising foodservice labor costs and growing demand for shelf-stable, batch-consistent convenience ingredients across packaged food manufacturing.
Food Processing dominated with approximately 41.2% share in 2025, while Foodservice is the fastest growing segment with a CAGR of approximately 8.1%.
North America dominated the Dehydrated Potato Market in 2025, while Asia Pacific is the fastest-growing region.
