
Diesel Exhaust Fluid Market Report Scope and Overview
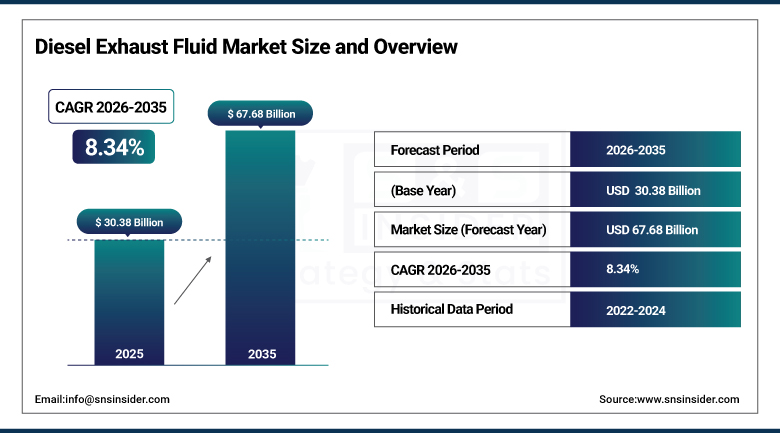
The Diesel Exhaust Fluid Market was valued at USD 30.38 Billion in 2025 and is estimated at USD 32.91 Billion in 2026. The market is forecast to reach USD 67.68 Billion by 2035, registering a CAGR of 8.34% from 2026 to 2035. Growth reflects stricter nitrogen oxide limits for trucks, buses, and off-highway machines, expanding selective catalytic reduction fleets, and wider bulk and dispenser networks, partly offset by electrification of heavy trucks in China. North America led the market with a share of 37.18% in 2025, while Asia Pacific is expected to expand fastest.
To Get more information Diesel Exhaust Fluid Market - Request Free Sample Report
Key Market Trends & Insights
-
By supply mode: Bulk held the largest market share of 52.43% in 2025.
-
By vehicle type: Heavy Commercial Vehicles held the largest market share of 47.62% in 2025.
-
By distribution channel: OEM held the largest market share of 61.38% in 2025.
-
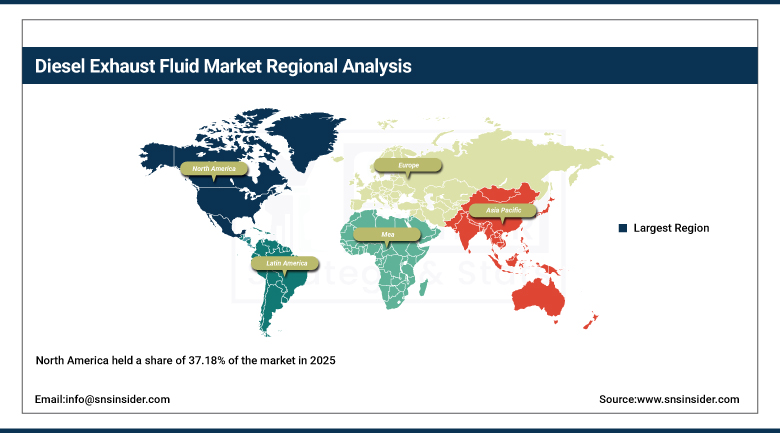
By region: North America held the largest regional share of 37.18% in 2025, followed by Asia Pacific at 27.84% and Europe at 24.61%.
-
Asia Pacific is projected to register the fastest regional CAGR of 10.21% from 2026 to 2035.
-
The U.S. is the leading country market in North America, supported by a large heavy truck fleet and strict nitrogen oxide limits that start with the 2027 model year.
Growth Outlook
In July 2026, the U.S. Environmental Protection Agency proposed revisions to its heavy-duty engine rule that keep the model year 2027 nitrogen oxide standard of 0.035 g/bhp-hr, more than 80.00% below the earlier limit, while replacing severe power derates for empty tanks with visible and audible alerts. Because the standard can only be met with selective catalytic reduction, every new heavy truck sold from 2027 will depend on diesel exhaust fluid. The proposal softens warranty and enforcement terms, but it leaves the technology requirement in place and gives engine makers clear grounds to plan for higher fluid consumption per vehicle.
Europe is moving in the same direction. Regulation (EU) 2024/1257, known as Euro 7, applies to new types of trucks, buses, and trailers from 29 May 2028 and to all new heavy vehicles from 29 May 2029, and it keeps selective catalytic reduction at the center of heavy-duty compliance. Fleets that renew vehicles over the next several years will therefore add more urea-based systems, and fluid demand will follow. Non-road machines add a second layer through Stage V and similar rules, so growth in consumption is expected to exceed growth in vehicle sales.
Market Dynamics
Driver: Tighter Emission Rules and Larger Selective Catalytic Reduction Fleets Raise Fluid Consumption
China VI-b rules require all new heavy-duty vehicles from July 2023 to meet strict nitrogen oxide limits with on-board remote monitoring, and the system must induce a power limit when the reductant is missing or of poor quality. This design links vehicle operation directly to the use of authentic fluid, so each truck on the road becomes a steady buyer, and the large Chinese heavy truck fleet is the biggest single pool of demand in the world. Diesel remains dominant in heavy transport in most regions, with electric trucks still a small part of the fleet outside China. Remote monitoring also makes tampering with dosing systems far harder for operators, which protects steady consumption.
Non-road machines and developing markets add further demand. India introduced CEV Stage V for construction equipment in January 2025 and has set TREM V for tractors in a staged schedule that starts in 2026, so farm and construction machines in the country are moving toward selective catalytic reduction for the first time. Brazil, Mexico, and other markets apply their own heavy-duty standards. As these programs take effect, engines that once ran without aftertreatment will need a regular supply of fluid, which expands the customer base and increases demand for bottles, drums, and bulk deliveries. Dealers and distributors in these countries are already stocking packaged fluid, and bulk storage is appearing at farm cooperatives and mining sites.
Restraint: Electrification of Heavy Trucks, Urea Price Swings, and Regulatory Relief in the United States
Electric heavy trucks are the main long-term threat. In September 2026, electric vehicles reached 50.30% of heavy-truck sales in China, up from about 13.60% in 2024, and the share of the country on-road heavy fleet that is electric is still small but rising each month. Every electric truck replaces a diesel vehicle that would have consumed fluid, so demand in the largest national market could flatten earlier than elsewhere. In Europe and North America the shift is much slower, with electric trucks making up only a small portion of new registrations. Operators of electric fleets also gain lower fuel and service costs, which encourages further switching in logistics, ports, and urban distribution over time.
Input costs are volatile. Urea rose sharply in spring 2026 after disruption of Gulf shipping, reaching about USD 684.00 per metric ton in early April, and then fell to about USD 386.00 per metric ton by August. Because fluid is about two-thirds water and one-third urea, producers must adjust prices within days, and buyers on fixed contracts feel the swings. Trade policy, including export quotas on fertilizer in China, adds further uncertainty. Relief on enforcement of empty-tank rules could also reduce discipline among fleet operators, though fines and warranty issues limit the risk. Many distributors hold only a few weeks of stock, so sudden swings reduce margins and delay restocking at smaller retail sites.
Opportunity: Marine and Rail Rules, Bulk Networks, and Low-Carbon Fluid Create New Demand
Marine and rail uses are expanding. In May 2026, the International Maritime Organization adopted a North-East Atlantic Emission Control Area for nitrogen oxides, sulfur oxides, and particulates, with entry into force on 1 September 2027, which will extend strict Tier III limits to ships that operate in these waters. Selective catalytic reduction is the main route to meeting Tier III, and ships consume large volumes of marine-grade fluid. Rail operators and generator set owners also adopt aftertreatment as rules tighten, which opens new bulk supply contracts and port-side storage projects for fluid suppliers. Ports and shipping companies are expected to sign storage and bunkering agreements as the rule approaches, which adds a new customer group.
Distribution and product innovation offer a second opening. Truck stops, fleet depots, farm cooperatives, and construction sites are installing bulk tanks and dispensers, which lowers cost per liter and improves quality control compared with small containers. Producers are also launching low-carbon products, such as fluid made with renewable electricity and low-carbon ammonia, and several are building local mixing plants to shorten supply chains. Telematics that report tank levels and trigger refills give suppliers a way to build recurring service revenue and to protect customers from shortages and quality problems. Suppliers that combine certified quality, reliable delivery, and digital monitoring can win long contracts with large fleets, mining companies, and agricultural operators in several regions.
Market Characteristics & Concentration
The Diesel Exhaust Fluid Market is Moderately Consolidated. Large fertilizer and chemical producers supply most urea and finished fluid, while a wide group of regional packagers, lubricant companies, fuel marketers, and distributors package and sell it under many brands. Producers with their own urea and ammonia compete on cost and supply security, whereas brand owners and distributors compete on packaging, delivery networks, quality assurance, and retail presence. Pricing follows urea costs closely.
Quality rules are central. ISO 22241-1:2019 sets the specification for the 32.50% urea solution used in selective catalytic reduction systems, and the American Petroleum Institute runs a certification mark that requires licensed producers to submit batch test results and report volumes each year. Engine makers recommend fluids that meet these standards, because poor quality can damage catalysts and sensors and lead to warranty claims. Buyers in large fleets often require proof of certification before they sign supply contracts.
Barriers to entry are moderate for packaging and distribution but higher in production, where access to technical-grade urea, clean water, and quality systems matters. Supply shocks in recent years have also rewarded firms with secure raw material access. Scale in logistics also matters, because the product is heavy, mostly water, and costly to move over long distances. Suppliers therefore build filling and storage points near large customers, and bulk contracts with fleets and distributors reward those with dense delivery routes and dependable service. Brand recognition is strongest in retail and passenger vehicle channels.
Analyst Perspective
The diesel exhaust fluid market is anchored by regulation, because every modern heavy-duty diesel engine that meets current nitrogen oxide limits needs the fluid to run. Demand will keep rising as more fleets renew vehicles and as non-road machines in India, China, and other markets adopt selective catalytic reduction, even as electric trucks erode demand in China. North America will remain the largest market, and Asia Pacific is expected to grow fastest. Producers with secure urea supply, strong quality assurance, and bulk delivery networks will gain the most share. An SNS Insider Analyst, Santosh Bhul, commented, "Diesel exhaust fluid is a compliance product, and the suppliers that guarantee quality and secure raw materials will win the next wave of fleet and non-road demand."
Segment Analysis
Supply Mode Insights
Bulk occupied the maximum share of 52.43% in 2025. Fleets, truck stops, depots, farms, and mines procure fluids in tanker loads and store them in site tanks that give the lowest price per liter and an assured supply to the big consumers. Bulk distribution is also less vulnerable to contamination than open containers, and telematics-enabled tank monitoring allows for scheduling delivery. The heavy-duty fleets use a lot of fluids each week, hence bulk deals occupy the biggest share, and the trend of long service intervals in fleets helps in repeat purchases of big distributors.
Pumps and Dispensers will have the highest growth CAGR of 9.86% during 2026-2035. The retail fuel stations, truck stops, and fleet depots install dispensers to cater to the needs of drivers who like to fill their tanks fast, and equipment manufacturers provide meters, heaters, and telematics-enabled dispensers. Growing use of selective catalytic reduction in light commercial vehicles and off-road equipment increases the number of locations requiring dispensing. The share of IBCs and Drums is unchanged in small fleets and workshops, whereas Cans and Bottles are unchanged in consumer market.
Vehicle Type Insights
Heavy Commercial Vehicles accounted for the largest share of 47.62% in 2025. Long-haul trucks, buses, and vocational vehicles carry large tanks and travel long distances each year, so they consume far more fluid per vehicle than other classes. Regulation in North America, Europe, China, and India requires aftertreatment on these engines, and fleet operators buy fluid in bulk to control costs. The size of the global heavy truck fleet and the long working life of trucks keep this segment well ahead of light vehicles in value terms. Fleet managers also favor products approved by engine makers.
Off-Highway Equipment is projected to grow at the fastest CAGR of 10.37% from 2026 to 2035. Construction machines, agricultural tractors, mining trucks, and generator sets are being brought under stricter standards such as Stage V in Europe, Stage IV in China, and the new rules in India, which forces adoption of selective catalytic reduction in engines that once ran without it. Light Commercial Vehicles and Passenger Cars add steady demand, as vans and diesel cars with selective catalytic reduction require periodic refills and are often serviced through dealers. Servicing networks continue to grow.
Distribution Channel Insights
The OEM segment had the highest market share of 61.38% in 2025. Vehicle and engine producers provide fluid and dosing systems along with the new machinery and approve certain products, and the dealerships of the manufacturers fill up the tanks as part of service. Fleet deals, first-fill programs, and branded products help manufacturers gain customers, and approvals of engines manufacturers hold some value in purchases. The OEM segment is always the largest since there is a dosing system provided along with every new vehicle that falls under regulation.
The aftermarket is forecast to have the fastest CAGR of 9.41% from 2026 to 2035. Truck stops, fuel retailers, independent shops, farm supplies dealers, and online vendors get more and more business as the installed base of SCR vehicles becomes older and goes beyond the reach of the dealership network. Customers that own older trucks and off-road equipment opt for cheap fluid at local fuel stations because that is where it can be conveniently purchased. Certifications are key to this customer group; therefore, it gives advantages to established players in marketing and producing these products.
Regional Insights
North America held a share of 37.18% of the market in 2025, ahead of Asia Pacific and Europe. The region has a large heavy truck fleet, a mature network of truck stops with bulk dispensers, and strict nitrogen oxide limits that apply to model year 2027 engines. Domestic urea production supports stable supply, and the region is home to major producers and brand owners. Canada and Mexico add demand through freight and agriculture, and off-highway equipment such as tractors and construction machines adds steady volumes.
Get Customized Report as per Your Business Requirement - Enquiry Now
U.S. Diesel Exhaust Fluid Market
The U.S. Diesel Exhaust Fluid Market was valued at USD 9.98 Billion in 2025 and is projected to expand at a CAGR of 7.92% from 2026 to 2035. Long-haul trucking, construction, mining, and farming consume large volumes, and truck stops and fleet depots maintain extensive bulk and dispenser networks. Federal rules for the 2027 model year add a further layer of aftertreatment content, while producers with nitrogen plants in the Gulf Coast and Midwest keep supply stable even when global urea prices swing sharply. Gulf Coast ports also support exports of packaged product.
Retail demand is supported by several million diesel pickups and vans that use selective catalytic reduction, and fluid is available at fuel stations, auto parts stores, and online. Large fleets sign multi-year bulk contracts and use telematics to track consumption, while spring fertilizer demand can tighten urea supply. Federal policy debates on enforcement of empty-tank rules and on California truck regulations create uncertainty about timing, but the requirement to use aftertreatment remains in place, so fluid consumption is expected to grow steadily through the forecast period. Rising adoption among farm and construction machines adds further volume.
Europe Diesel Exhaust Fluid Market
Europe accounted for 24.61% of the market in 2025, led by Germany, France, the United Kingdom, Italy, and Spain. The region introduced Stage V rules for non-road machines with type approval from 1 January 2018, and trucks, buses, and vans already use selective catalytic reduction widely under Euro VI. Large producers of ammonia and urea in Germany, the Netherlands, Norway, and Poland supply the market, and the brand AdBlue is the standard name for the fluid. Fleet operators buy through bulk networks and fuel cards, and quality certification is strongly emphasized.
Gas price shocks in 2022 showed how exposed European fluid supply can be to energy costs, as several producers cut output and prices jumped. Producers have since improved resilience by diversifying feedstock and building stocks. Electric trucks are growing slowly, and diesel still accounts for the large majority of new heavy truck registrations, which supports steady consumption. Cross-border freight flows, strong agricultural machinery use, and rising marine demand add further volumes, while sustainability programs encourage low-carbon fluid products.
Asia Pacific Diesel Exhaust Fluid Market
Asia Pacific held a share of 27.84% in 2025 and is projected to register the fastest regional CAGR of 10.21% from 2026 to 2035, led by China, India, Japan, South Korea, and Southeast Asia. China has the world largest heavy truck fleet and enforces China VI for on-road vehicles and Stage IV for non-road machines, while India is scaling up aftertreatment under BS-VI heavy-duty rules and new standards for construction and farm equipment. In February 2025, Chinese officials said work on the next national emission standard would speed up.
Local urea producers supply much of the region, but import dependence for technical-grade urea in India makes supply sensitive to global events. Japan and South Korea have mature markets with high quality requirements, and Southeast Asian countries are adding standards and local mixing plants. Rising freight volumes, infrastructure projects, and mechanization of agriculture drive consumption, while electric truck growth in China tempers on-road demand. Overall, the region offers the largest absolute increase in volume through 2035.
Latin America Diesel Exhaust Fluid Market
Latin America accounted for 5.95% of the market in 2025, led by Brazil and Mexico. Brazil applies PROCONVE P8 limits on heavy trucks, which require selective catalytic reduction, and Mexico applies NOM-044 on heavy-duty engines. Agriculture, mining, and long-distance freight consume large volumes of diesel, and fluid demand follows fleets that adopt newer engines. Local mixing and packaging plants serve many customers, while some producers import technical-grade urea. Currency swings affect prices, and distribution networks at truck stops and farm suppliers are still expanding in many countries.
Middle East & Africa Diesel Exhaust Fluid Market
The Middle East and Africa held 4.42% of the market in 2025, led by Saudi Arabia, the United Arab Emirates, Turkey, Egypt, and South Africa. Gulf countries host large urea and ammonia producers and import many vehicles that carry selective catalytic reduction, while logistics hubs and construction projects drive diesel use. Emission standards are tightening in several countries, though enforcement varies. Africa has smaller volumes concentrated in South Africa and North Africa, and growth depends on adoption of newer engines and on development of mixing and retail networks across the region.
Key Diesel Exhaust Fluid Market Company Insights
Companies in the diesel exhaust fluid market are focusing on secure urea supply, bulk and dispenser networks, third-party quality certification, and low-carbon product lines. Fertilizer producers integrate forward into finished fluid, while lubricant and fuel marketers extend brands through retail channels. Capacity additions near large demand centers, digital tank monitoring, and local mixing plants shape competition across all regions.
Key Diesel Exhaust Fluid Companies:
-
Yara International
-
CF Industries
-
BASF
-
Old World Industries
-
Brenntag
-
SKW Piesteritz
-
GNFC
Recent Developments
-
In August 2026, CF Industries signed a front-end engineering and design agreement for a urea liquor upgrade plant at its Courtright complex in Ontario that could add more than 400,000 tons a year of diesel exhaust fluid capacity, with a final investment decision expected in 2027.
-
In April 2026, SKW Piesteritz said it was operating near full capacity for the first time in three years, improving supply of ammonia and urea used in European fluid production.
-
In March 2026, Brenntag received VDA certification for its AdBlue site at Samut Prakan, Thailand, described as the first VDA-certified AdBlue facility in Asia Pacific.
-
In March 2026, GNFC, the only domestic producer of technical-grade urea in India, was reported to be facing a gas supply constraint that put production at risk, as the product meets 40.00% to 50.00% of national demand.
-
In February 2026, BASF launched AdBlue GE, made with 100.00% green electricity, starting in Switzerland through a distributor, with other European countries to follow.
-
In May 2025, Old World Industries acquired J&J Lubricantes in Monterrey, Mexico, to produce PEAK products and BlueDEF locally.
Scope and Research Methodology
The study defines the Diesel Exhaust Fluid Market as the 32.50% aqueous urea solution used as the reductant in selective catalytic reduction systems, sold as DEF, AdBlue, or generic AUS 32, together with the storage, dispensing, and dosing systems that deliver it to vehicles and machines. Coverage includes heavy and light commercial vehicles, passenger cars, and off-highway equipment, supplied through bulk, IBC, drum, and container formats. Fuel, engine, and exhaust catalyst products unrelated to the reductant are excluded. The forecast period runs from 2026 to 2035, and all values are expressed in USD. The base year is 2025, and the estimate year is 2026.
The research program combines secondary and primary research. Secondary research draws on emission regulation texts, standards body and certification documents, commodity price series, trade and customs databases, company filings and investor presentations, and trade publications. Primary research consists of structured interviews and surveys with fluid producers, packagers, distributors, fleet operators, engine makers, and dispenser suppliers. These inputs inform vehicle parc, fluid consumption rates, selling prices, urea cost pass-through, and the mix of bulk and packaged sales. Regional views from country-level fleet data further refine the totals across the forecast period.
Market engineering follows a bottom-up build from regulated vehicle and equipment populations, consumption per unit, and selling prices, cross-checked top-down against reported revenue of leading suppliers and urea production data. Segment shares are estimated from the mix of supply modes, vehicle types, and channels across tracked suppliers, and regional values are aligned so that all regions add up to the global total. Forecasts reflect drivers such as emission rules, fleet renewal, electrification, and urea prices, and every estimate passes through an analyst quality review before publication. Cross-checks against urea production, trade flows, and reported supplier volumes help confirm consistency across segments and regions. Estimates are reviewed against shipment trends and supplier commentary before they are finalized.
Diesel Exhaust Fluid Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 30.38 Billion |
| Market Size by 2035 | USD 67.68 Billion |
| CAGR | CAGR of 8.34% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Supply Mode (Bulk, IBCs and Drums, Cans and Bottles, and Pumps and Dispensers) • By Vehicle Type (Heavy Commercial Vehicles, Light Commercial Vehicles, Passenger Cars, and Off-Highway Equipment) • By Distribution Channel (OEM and Aftermarket) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Yara International, CF Industries, BASF, Old World Industries, Brenntag, SKW Piesteritz, GNFC |

Frequently Asked Questions
The market was valued at USD 30.38 Billion in 2025 and is projected to reach USD 67.68 Billion by 2035.
The market is expected to register a CAGR of 8.34% from 2026 to 2035.
North America led the market with a 37.18% share in 2025, ahead of Asia Pacific at 27.84% and Europe at 24.61%.
Asia Pacific is expected to grow the fastest, at a CAGR of 10.21% from 2026 to 2035.
Bulk led the supply mode segment with a 52.43% share in 2025, and Heavy Commercial Vehicles led the vehicle type segment.
