
Drug Addiction Treatment Market Report Scope & Overview:
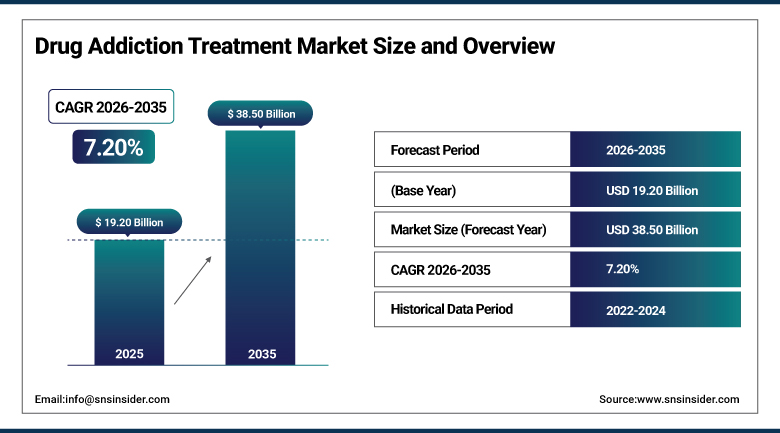
The Drug Addiction Treatment Market was valued at USD 19.20 Billion in 2025 and is expected to reach USD 38.50 Billion by 2035, growing at a CAGR of 7.20% from 2026–2035.
The Drug Addiction Treatment Market will be experiencing growth driven by the increasing rates of substance abuse disorders and greater awareness that addiction can be considered as a disease that can be treated. Growing governmental programs aimed at providing better access to treatment through various programs as well as funding for the treatment of addiction. Usage of drugs like buprenorphine, methadone, and naltrexone is also expected to boost the demand for the treatment, particularly when dealing with opioid dependency issues. Outpatient therapy, behavioral treatments, and other innovative care options are also driving the market growth in the segment. Increased investments in the treatment of addiction through innovative solutions including new therapies and personalized care solutions are also expected to drive the market growth.
Indivior received FDA approval in February 2025 for label changes to SUBLOCADE, its once-monthly injectable buprenorphine treatment for opioid use disorder, including a rapid initiation protocol that cuts the time to begin treatment from one week down to a single hour. That kind of speed matters enormously in addiction medicine specifically, since the gap between a patient deciding they're ready for treatment and actually receiving it is exactly the window where relapse or overdose risk is highest, and a week-long waiting period has historically been long enough for many patients to lose their resolve or their access to care entirely.
To Get more information Drug Addiction Treatment Market - Request Free Sample Report
Drug Addiction Treatment Market Trends:
-
Long-acting injectable treatments reduce daily adherence burdens, improving continuity and persistence among patients receiving addiction care.
-
Integrating behavioral health with primary care expands access, enabling earlier identification and comprehensive substance use disorder treatment.
-
Telehealth counseling and remote monitoring platforms improve addiction treatment access across regions lacking specialized treatment centers.
-
Growing awareness and destigmatization increasingly position substance use disorder as a chronic medical condition requiring treatment.
-
Government initiatives and funding support policy reforms, treatment infrastructure, and expanded responses to rising substance abuse.
U.S. Drug Addiction Treatment Market Outlook:
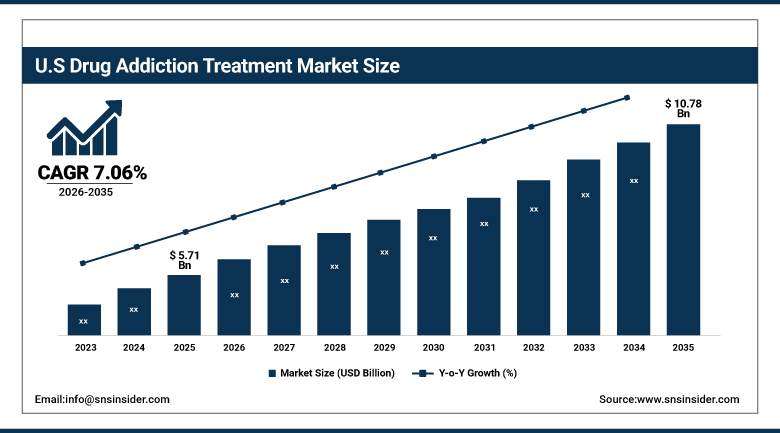
The U.S. Drug Addiction Treatment Market was valued at approximately USD 5.71 Billion in 2025 and is expected to reach approximately USD 10.78 Billion by 2035, growing at a CAGR of approximately 7.06%.
Demand in the United States remains anchored by advanced healthcare infrastructure, higher treatment awareness, and strong adoption of medication-assisted therapies across a population still grappling with a sustained opioid crisis. The economic impact of the opioid epidemic on the domestic healthcare system remains substantial, with an average of four people dying from opioid overdose every hour of every day continuing to drive sustained government and private investment in treatment infrastructure. Investments being made in addiction treatment, improvements in insurance coverage, and integration of behavioral health into general medical practice continue bolstering domestic market growth.
Braeburn, based in Plymouth Meeting, Pennsylvania, launched BRIXADI in September 2023 as the first and only weekly and monthly subcutaneous buprenorphine injection for opioid use disorder, built on a 24-week Phase III trial of 428 adults that deliberately included patients who injected opioids, used heroin, and showed evidence of fentanyl use rather than a narrower, less representative study population.
Drug Addiction Treatment Market Segment Analysis:
-
By Type, the Opioid Addiction segment dominated the Drug Addiction Treatment Market with approximately 44.60% share in 2025, while the Stimulant Addiction segment is the fastest growing with a CAGR of approximately 8.60%.
-
By Treatment, the Therapy segment dominated the Drug Addiction Treatment Market with approximately 52.00% share in 2025, while the Rehabilitation Programs segment is the fastest growing with a CAGR of approximately 7.80%.
-
By Route of Administration, the Oral segment dominated the Drug Addiction Treatment Market with approximately 42.67% share in 2025, while the Injectable segment is the fastest growing with a CAGR of approximately 8.40%.
-
By Care Delivery Setting, the Rehabilitation Centers segment dominated the Drug Addiction Treatment Market with approximately 38.60% share in 2025, while the Outpatient Clinics segment is the fastest growing with a CAGR of approximately 8.20%.
-
By Distribution Channel, the Hospital Pharmacies segment dominated the Drug Addiction Treatment Market with approximately 44.20% share in 2025, while the Online Pharmacies segment is the fastest growing with a CAGR of approximately 8.80%.
By Type, opioid addiction dominates, stimulant addiction grows fastest
Opioid addiction held the largest share of the type segment in 2025, driven by the overprescription of painkillers and aggressive marketing that historically minimized addiction risks, combined with easy access to unused medications and heroin as a cheaper substitute once prescriptions run out. Co-occurring mental health issues like depression continue exacerbating misuse, while the combination of overprescription, availability, and untreated mental health has created a sustained crisis that keeps opioid addiction the dominant treatment category by a wide margin.
Stimulant addiction is growing fastest as methamphetamine and cocaine use continue rising in multiple regions, creating demand for specialized treatment approaches distinct from the medication-assisted therapies well-established for opioid use disorder. The absence of an FDA-approved medication specifically for stimulant use disorder comparable to buprenorphine for opioids is driving significant research and treatment program investment, reinforcing this above-average growth trajectory.
By Treatment, therapy dominates, rehabilitation programs grows fastest
Therapy held the majority share of the treatment segment in 2025, encompassing behavioral counseling, cognitive behavioral therapy, and group support programs that remain foundational to nearly every addiction treatment plan regardless of which substance a patient is being treated for. That universal applicability across substance types keeps therapy the dominant treatment category, since even patients on medication-assisted treatment protocols are generally required to combine medication with counseling and psychosocial support.
Rehabilitation programs are growing fastest, driven by rising demand for long-term recovery services, relapse prevention programs, and integrated behavioral health support that extends care well beyond initial detoxification and stabilization. Growing recognition that addiction requires sustained, long-term management rather than a single treatment episode continues reinforcing this above-average growth trajectory relative to the broader, therapy-dominated treatment mix.
By Route of Administration, oral dominates, injectable grows fastest
Oral administration held the largest share of the route-of-administration segment in 2025, remaining the practical default for most medication-assisted treatment protocols given its lower cost, easier distribution, and compatibility with standard retail and hospital pharmacy dispensing infrastructure. That combination of cost efficiency and distribution simplicity keeps oral administration the dominant route across the broader drug addiction treatment market.
Injectable administration is growing fastest as long-acting injectable formulations continue displacing daily oral medications specifically because they remove the daily adherence burden that has historically undermined treatment continuity for many patients. Growing clinical evidence supporting improved outcomes with monthly and weekly injectable buprenorphine formulations continues reinforcing this above-average growth trajectory relative to the broader, oral-dominated administration mix.
By Care Delivery Setting, rehabilitation centers dominates, outpatient clinics grows fastest
Rehabilitation centers held the largest share of the care-delivery-setting segment in 2025, offering the structured, intensive treatment environment that many patients with moderate to severe substance use disorders require during initial stabilization and early recovery. That combination of clinical intensity and structured support keeps rehabilitation centers the dominant care setting across the broader drug addiction treatment market.
Outpatient clinics are growing fastest as healthcare systems increasingly emphasize outpatient accessibility, allowing patients to receive treatment while maintaining employment, family responsibilities, and community connections that residential treatment can disrupt. Integration of behavioral health and addiction treatment into general medical practice continues reinforcing this above-average growth trajectory relative to the broader, rehabilitation-center-dominated care-setting mix.
By Distribution Channel, hospital pharmacies dominates, online pharmacies grows fastest
Hospital pharmacies held the largest share of the distribution-channel segment in 2025, due to their advantageous position facilitating access to care for patients already engaged with the broader healthcare system through emergency department visits, inpatient stays, or outpatient hospital-affiliated clinics. That built-in access advantage keeps hospital pharmacies the dominant distribution channel across the broader drug addiction treatment market.
Online pharmacies are growing fastest as digital treatment innovations and telehealth counseling continue expanding access to addiction care, particularly in regions with limited specialized treatment center availability or where stigma discourages in-person pharmacy visits. Growing consumer comfort with telehealth-prescribed medication delivery continues reinforcing this above-average growth trajectory relative to the broader, hospital-pharmacy-dominated distribution mix.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
82.40% |
|
Europe |
Germany |
25.60% |
|
Asia Pacific |
China |
38.20% |
|
Latin America |
Brazil |
35.40% |
|
Middle East & Africa |
UAE |
29.70% |
North America Drug Addiction Treatment Market Insights
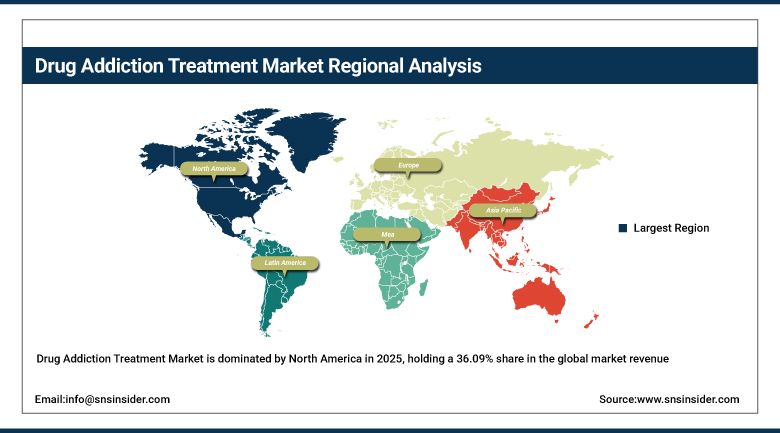
The Drug Addiction Treatment Market is dominated by North America in 2025, holding a 36.09% share in the global market revenue. This is attributable to the fact that North America has a well-developed healthcare infrastructure, high treatment awareness, and adoption of medications in treatment programs. Continued investment in addiction treatment, insurance, and incorporation of behavioral health within the general healthcare facilities are some of the reasons that keep North America in this dominant position.
Canada plays an important part due to its healthcare and addiction treatment facilities, while the Mexico market has been expanding due to increased investment in the healthcare sector. Pharmaceutical supply arrangements across borders have created a link between these regions' demand for medications. Major players usually serve the three regions through common distribution channels.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Drug Addiction Treatment Market Insights
Asia Pacific is expected to register the fastest regional growth through 2035, led by China, Japan, and India through healthcare modernization, supportive government policies, and increasing awareness of substance use disorder treatment across the region's largest and fastest-growing economies. Improved access to drug addiction treatment options, combined with increasing awareness about the devastating impact of drug abuse, continues reinforcing this accelerating growth trajectory.
China's expanding healthcare infrastructure and growing addiction treatment awareness give the region substantial baseline demand, while India's rapidly modernizing healthcare system is drawing significant new investment in substance use disorder treatment capacity. Japan and South Korea represent more mature, technology-forward markets with established treatment infrastructure, while Southeast Asian markets continue following a similar healthcare-modernization-driven growth trajectory.
Europe Drug Addiction Treatment Market Insights
Europe represents a mature, well-established drug addiction treatment market, supported by comprehensive healthcare systems and strong government funding for addiction treatment infrastructure across the region's largest economies. Germany anchors regional demand, home to a large healthcare system and substantial investment in medication-assisted treatment and behavioral health integration.
The United Kingdom, France, and Italy contribute meaningful volume as well, each with substantial public healthcare systems providing addiction treatment services alongside growing private treatment center capacity. Growing regional emphasis on integrated behavioral health and addiction treatment continues shaping healthcare policy and service delivery across the region more directly than in most other global markets.
MEA & Latin America Drug Addiction Treatment Market Insights
The Middle East and Africa represent a smaller but strategically developing drug addiction treatment market, with the UAE driving demand through growing healthcare infrastructure investment tied to broader economic diversification and public health modernization goals. Growth elsewhere in the region remains tied closely to the pace of broader healthcare infrastructure and addiction treatment awareness development.
Latin America is a growing market led by Brazil, where expanding healthcare infrastructure and rising substance abuse awareness continue driving demand for addiction treatment services. Mexico and Argentina contribute meaningful secondary demand, tied to their own growing healthcare systems and public health initiatives addressing substance use disorders.
Market Dynamics:
Growth Drivers: Rising substance abuse prevalence and destigmatization fueling adoption
An increase in the number of substance abuse disorders around the world is one of the most prominent reasons for an increased demand for drug addiction treatment, considering the estimates from the World Health Organization regarding 39.5 million people suffering from substance abuse disorders in the world today. This important aspect provides the demand side of the market with a public health issue of global importance that will continue to grow irrespective of the prevailing economic environment.
Awareness and demystification of substance abuse issues provide the second important aspect driving the demand on this side of the market. Changes in policy and culture that now view substance abuse disorder as a medical condition to be treated rather than a moral failing to be punished provide an additional push to this already strong demand base through government and other initiatives and advancements in therapy.
Restraints: Treatment access barriers and social stigma limiting broader adoption
Limited access to treatment is certainly a significant constraint, as less than half of the 2.5 million American patients diagnosed with opioid use disorder have access to medication-assisted treatment. The lack of access to prescribers, insurers, and treatment centers prevents the actualization of the demand within the market for those who are prepared to be treated.
The social stigma associated with substance use disorder is another significant constraint, which affects patients' willingness to pursue treatment because of fears of being judged by family members, employers, and other members of their communities, despite increasing efforts towards reducing the stigma of substance use disorders. The social stigma, together with problems related to compliance with prescribed treatment, hinders the full realization of demand within the market.
Opportunities: Long-acting injectable formulations and digital treatment expansion opening new growth avenues
The development of long-acting injection formulations provides manufacturers with a real opportunity for securing top-tier business from healthcare professionals and consumers looking for drug regimens which eliminate the burden of adherence associated with many orally administered medications. Those companies which are successful in developing and selling novel injectable formulations supported by fast-initiation protocols have a real chance to secure themselves a disproportionate amount of business in this field of endeavor.
The development of digital treatment is another important opportunity for growth, as telehealth counseling and monitoring services allow for greater access to addiction therapy services in areas where there are few specialized facilities for treatment. Those companies which are capable of providing digital treatment services have the potential to lock up an outsize amount of business in this growing market.
Recent Developments:
-
February 24, 2025: Indivior announced FDA approval of label changes for SUBLOCADE, including alternative subcutaneous injection sites in the abdomen, thigh, buttock, and back of the upper arm.
-
2025: Indivior was added to the S&P SmallCap 600 index, reflecting its growing market capitalization and prominence in the addiction treatment sector.
-
2025: Multiple pharmaceutical manufacturers, including Teva Pharmaceutical Industries, continued expanding production of generic opioid agonist treatments such as methadone and buprenorphine for managing addiction and withdrawal symptoms.
-
2025: Addiction treatment centers and outpatient clinics, including Hazelden Betty Ford Foundation, continued expanding distribution partnerships with pharmaceutical manufacturers to improve patient access to approved medication-assisted therapies.
Drug Addiction Treatment Market Key Players
-
Indivior PLC
-
Alkermes plc
-
Pfizer Inc.
-
Teva Pharmaceutical Industries Ltd.
-
Mallinckrodt Pharmaceuticals
-
Hikma Pharmaceuticals PLC
-
Otsuka Pharmaceutical Co., Ltd.
-
Novartis AG
-
Dr. Reddy’s Laboratories Ltd.
-
Cipla Limited
-
Viatris Inc.
-
Camurus AB
-
Orexo AB
-
Braeburn Inc.
-
Emergent BioSolutions Inc.
-
Acadia Healthcare Company, Inc.
-
Universal Health Services, Inc.
-
Hazelden Betty Ford Foundation
-
American Addiction Centers
-
Eleanor Health
Drug Addiction Treatment Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 19.20 Billion |
| Market Size by 2035 | USD 38.50 Billion |
| CAGR | CAGR of 7.20% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Opioid Addiction, Stimulant Addiction, Nicotine/Tobacco, Others) • By Treatment (Therapy, Medications, Rehabilitation Programs, Others) • By Route of Administration (Oral, Injectable, Others) • By Care Delivery Setting (Rehabilitation Centers, Hospitals, Outpatient Clinics, Others) • By Distribution Channel (Hospital Pharmacies, Retail Pharmacies, Online Pharmacies) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Indivior PLC, Alkermes plc, Pfizer Inc., Teva Pharmaceutical Industries Ltd., Mallinckrodt Pharmaceuticals, Hikma Pharmaceuticals PLC, Otsuka Pharmaceutical Co., Ltd., Novartis AG, Dr. Reddy’s Laboratories Ltd., Cipla Limited, Viatris Inc., Camurus AB, Orexo AB, Braeburn Inc., Emergent BioSolutions Inc., Acadia Healthcare Company, Inc., Universal Health Services, Inc., Hazelden Betty Ford Foundation, American Addiction Centers, Eleanor Health |
Frequently Asked Questions
Key players in the Drug Addiction Treatment Market include Pfizer Inc., Indivior PLC, Novartis AG, Alkermes plc, and Teva Pharmaceutical Industries Ltd., among others.
Key opportunities in the Drug Addiction Treatment Market include long-acting injectable formulations removing daily adherence burden and digital treatment expansion through telehealth counseling and remote monitoring platforms.
The market is driven by rising prevalence of substance abuse disorders worldwide, combined with growing awareness and destigmatization of addiction as a chronic medical condition.
The Opioid Addiction segment dominated the Drug Addiction Treatment Market, accounting for approximately 44.60% market share.
The North America region dominated the Drug Addiction Treatment Market in 2025 with approximately 36.09% share, benefiting from advanced healthcare infrastructure and strong adoption of medication-assisted therapies.
