
E-Pharmacy Market Report Scope & Overview:
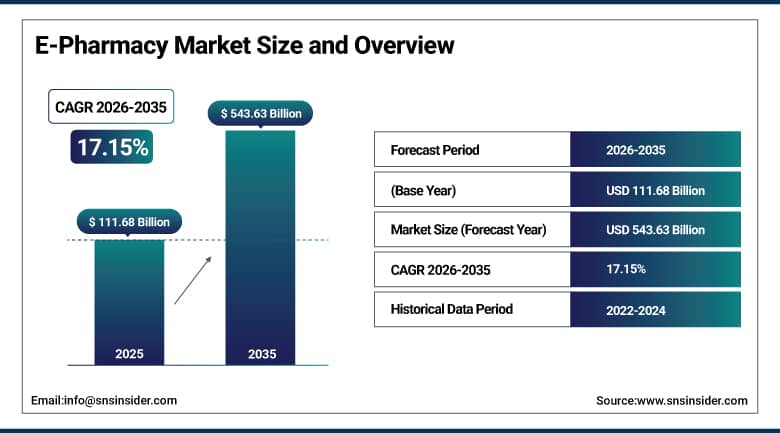
The E-Pharmacy Market was valued at USD 111.68 Billion in 2025 and is expected to reach USD 543.63 Billion by 2035, growing at a CAGR of 17.15% from 2026-2035.
E-Pharmacy Market growth is being fueled largely by increasing internet and smartphone adoption, increasing consumer demand for medicine delivery at their doorsteps, and continuous digitalization of prescription validation and payment mechanisms. E-pharmacies have kept increasing accessibility to medicines, minimizing the time spent waiting at physical pharmacies, and enabling the management of chronic ailments through customized refill schedules, thereby making e-pharmacy delivery a key part of modern healthcare infrastructure rather than just an optional retail channel. Increasing integration with telemedicine makes e-pharmacies more popular because the increasing number of prescriptions made virtually is now fulfilled online without having to make separate visits to the physical pharmacy. Increasing consumer demand for self-medicating and preventive healthcare along with increasing prevalence of chronic ailments and the aging population that needs repeated prescription fulfillment keeps the addressable market base for the channel growing.
In May 2026, the Corporation of European Pharmaceutical Distributors acquired Atida Group from OLP Intermediate S.A., expanding its presence across European pharmacy retail and digital healthcare markets and reinforcing its broader healthcare e-commerce and pharmacy network growth strategy. The acquisition reflects continued consolidation occurring across the e-pharmacy industry as established pharmaceutical distribution groups seek to expand digital healthcare commerce capability through acquisition, reinforcing the competitive position of well-capitalized platforms pursuing integrated pharmacy network and e-commerce strategies across multiple European markets.
To Get More Information On E-Pharmacy Market - Request Free Sample Report
E-Pharmacy Market Trends
-
Rising integration of telemedicine consultations directly with e-pharmacy fulfillment for seamless digital prescription delivery.
-
Growing adoption of mobile app-based ordering, medication reminders, and personalized refill scheduling capability.
-
Expanding subscription-based models for chronic disease medication management and recurring delivery.
-
Increasing regulatory clarity around telepharmacy policies supporting broader e-prescription and controlled substance delivery.
-
Rising consolidation among e-pharmacy platforms through acquisitions expanding regional network and digital healthcare capability.
-
Growing consumer preference for competitive pricing, discounts, and optimized last-mile logistics across online pharmacy platforms.
U.S. E-Pharmacy Market Outlook
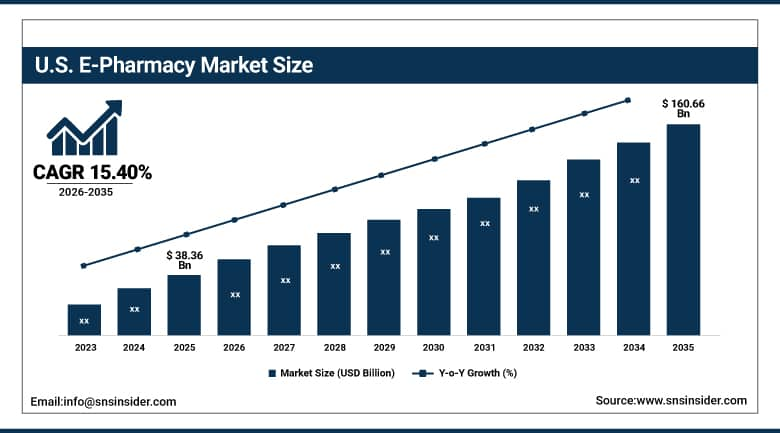
The U.S. E-Pharmacy Market was valued at USD 38.36 Billion in 2025 and is expected to reach USD 160.66 Billion by 2035, growing at a CAGR of 15.40% from 2026-2035.
The U.S. E-Pharmacy Market growth continues to be reinforced by high internet and smartphone penetration, an entrenched consumer preference for online convenience, and continued expansion of same-day and next-day prescription delivery infrastructure among major domestic pharmacy retailers and technology-driven entrants. Rising competition among established retail pharmacy chains and newer technology-driven pharmacy platforms continues to expand delivery coverage, pricing transparency, and digital prescription management capability available to domestic consumers. The country's large and aging population, combined with rising chronic disease prevalence requiring recurring medication management, continues to sustain strong baseline demand for online prescription fulfillment. Growth is further supported by clearer regulatory frameworks around telehealth-integrated prescribing, which continue to widen the range of medications that can be prescribed and fulfilled without an in-person visit.
In October 2024, Amazon Pharmacy announced plans to expand same-day prescription delivery to twenty additional U.S. markets, aiming to make same-day delivery available to nearly 45% of U.S. customers by the end of 2025. The expansion illustrates how major technology-driven pharmacy entrants continue to invest aggressively in delivery infrastructure to compete with established retail pharmacy chains, reinforcing delivery speed and convenience as an increasingly central competitive battleground within the domestic e-pharmacy market.
E-Pharmacy Market Segment Analysis
-
By Drug Type, the Prescription (Rx) Medicines segment dominated the E-Pharmacy Market with approximately 68.60% share in 2025, while the Over-The-Counter (OTC) Products segment is the fastest growing with a CAGR of approximately 22.80%.
-
By Business Model, the Inventory-Based segment dominated the E-Pharmacy Market with approximately 47.80% share in 2025, while the Marketplace-Based segment is the fastest growing with a CAGR of approximately 19.40%.
-
By Platform, the Mobile/App-Based segment dominated the E-Pharmacy Market with approximately 57.20% share in 2025, and is also the fastest growing with a CAGR of approximately 21.60%.
-
By Therapeutic Area, the Pain Management segment dominated the E-Pharmacy Market with approximately 19.80% share in 2025, while the Gastrointestinal Disorders segment is the fastest growing with a CAGR of approximately 16.80%.
By Drug Type, Prescription (Rx) Medicines Dominates the E-Pharmacy Market and OTC Products Grows Fastest
The prescription medicines segment dominates in terms of size as the recurring nature of prescription fill-ups forms the basis of the usage of the platform, especially by those who are suffering from chronic diseases that require regular refills. The increasing use of electronic prescriptions, the growth in telemedicine services, as well as an increasingly sophisticated system of regulation and control of the digital prescription process, are contributing towards the dominance of the prescription medicines segment.
OTC products have been identified as the fastest-growing drugs segment due to the growing inclination of consumers towards self-treatment along with the ease of access of non-prescription drugs and the increase in demand for preventative health care solutions. With increasing consumer interest in preventative health care solutions, vitamins, dietary supplements, immunity boosters, and personal care products are witnessing increasing demands.
By Business Model, Inventory-Based Dominates the E-Pharmacy Market and Marketplace-Based Grows Fastest
The inventory-based model dominates the market because platforms that directly stock and control pharmaceutical inventory can better ensure product authenticity, availability, and quality control, factors that remain critical for consumer and regulatory confidence in an industry where product integrity carries direct health and safety consequences. This direct control over inventory sourcing and storage conditions continues to reinforce the inventory-based model's position as the preferred operating structure among established, well-capitalized e-pharmacy platforms.
The marketplace-based model is the fastest-growing business model as platforms increasingly aggregate multiple independent pharmacy partners to expand product breadth and regional coverage without the capital intensity of building proprietary inventory and warehousing infrastructure. This growth is reinforced by marketplace platforms' ability to scale into new geographic markets more rapidly than inventory-based competitors, particularly across emerging markets where local pharmacy partnership networks can be assembled faster than dedicated warehouse infrastructure.
By Platform, Mobile/App-Based Dominates the E-Pharmacy Market and Also Grows Fastest
Mobile and app-based platforms dominate the market because smartphone-native ordering, medication reminders, and personalized purchase recommendations based on prior orders continue to enhance the overall shopping and medication-management experience relative to desktop or website-only alternatives. Rising smartphone penetration across both developed and emerging markets continues to place a broadening range of pharmaceutical products at users' fingertips, reinforcing mobile applications as the default access point for e-pharmacy platform engagement.
Mobile and app-based platforms are also the fastest-growing platform segment as e-pharmacy operators continue to invest in expanding app functionality, including order tracking, prescription upload, and integrated telehealth consultation booking, to differentiate their mobile experience from competitors. Continued growth in smartphone adoption across price-sensitive emerging markets is further reinforcing mobile applications' above-market growth trajectory relative to website-based ordering channels.
By Therapeutic Area, Pain Management Dominates the E-Pharmacy Market and Gastrointestinal Disorders Grows Fastest
Pain management dominates the market because pain-related conditions represent one of the most common and recurring reasons patients seek both prescription and over-the-counter medication, spanning acute, chronic, and post-surgical pain management needs across a broad patient population. The therapeutic area's breadth, spanning everything from common headache and muscle pain relief to chronic pain management medication, sustains pain management's position as the largest therapeutic area category for e-pharmacy platforms.
Gastrointestinal disorders represent the fastest-growing therapeutic area as rising digestive health awareness, growing prevalence of chronic gastrointestinal conditions, and expanding availability of both prescription and over-the-counter digestive health products continue to drive category growth through e-pharmacy channels. This growth is reinforced by increasing consumer comfort purchasing digestive health and related sensitive-category products online rather than in person, a channel preference that continues to favor e-pharmacy platforms over traditional retail pharmacy purchasing for this therapeutic category.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
84.60% |
|
Asia Pacific |
China |
38.60% |
|
Europe |
Germany |
27.80% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
|
Latin America |
Brazil |
29.80% |
North America E-Pharmacy Market Insights
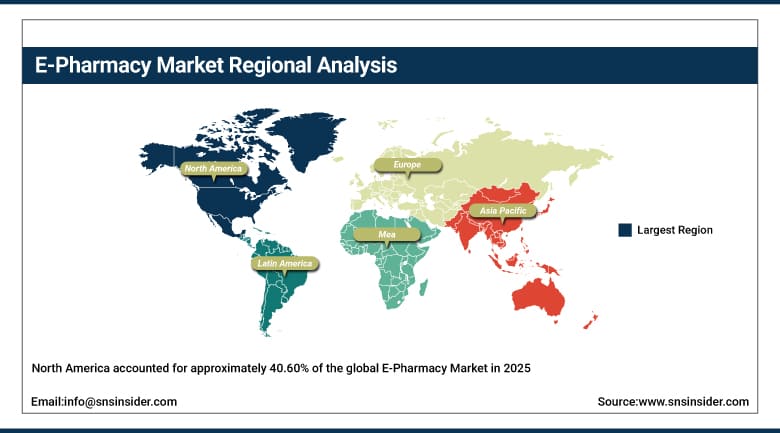
North America accounted for approximately 40.60% of the global E-Pharmacy Market in 2025, making it the largest regional market, supported by high internet and smartphone penetration, strong consumer preference for online convenience, and an established base of both technology-driven pharmacy entrants and traditional retail pharmacy chains expanding digital fulfillment capability. The United States accounts for the substantial majority of regional demand, anchored by major platform operators headquartered domestically and a large, aging population base with recurring prescription medication needs.
Canada is contributing incremental demand as regional e-pharmacy adoption continues to expand alongside similar digital healthcare access trends. Continued regulatory clarity around telepharmacy and e-prescription policy is reinforcing the region's leading position, as clearer frameworks continue to widen the range of medications that can be prescribed and fulfilled through fully digital channels.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific E-Pharmacy Market Insights
Asia Pacific is the region witnessing the fastest growth with a CAGR of approximately 19.80% from 2026 to 2035 due to the quick growth of internet and smartphone adoption, increased investments of middle class in health care, and initiatives undertaken by the government for the development of digital healthcare infrastructure in countries like China, India, and Southeast Asia. In China, the large domestic market for pharmaceutical e-commerce provides an impetus for fast scaling of the platforms, while the e-pharmacy market in India continues to grow rapidly with major domestic platforms creating presence through both online and physical stores.
India contributes significantly to incremental growth with major domestic players developing physical retail stores in addition to the online activities to create omnichannel approach towards health care. Japan and South Korea add to the scale of Asia Pacific through technology infrastructure and comfort level of consumers for digital healthcare solutions.
Europe E-Pharmacy Market Insights
Europe represents a significant share of the global E-Pharmacy Market, anchored by Germany's large pharmaceutical retail base and the region's mature e-commerce infrastructure, well-established regulatory frameworks, and growing aging population requiring recurring medication access. Germany's digital prescription redemption infrastructure continues to expand, with major regional platforms extending electronic prescription redemption capability directly within consumer-facing mobile applications.
The United Kingdom's advanced healthcare sector continues to adopt new digital tools that promote e-pharmacy usage, while France and other Western European markets are contributing steady demand growth as regional platforms extend digital prescription and delivery infrastructure. Growing digitalization and rising internet penetration across the region continue to support broader e-pharmacy platform adoption among Europe's aging population.
MEA & Latin America E-Pharmacy Market Insights
Although the Middle East & Africa market is still relatively small, it is growing due to increased investments in the digital health infrastructure and increased internet penetration in the United Arab Emirates and Saudi Arabia. Digital transformation policies in the region will contribute to the increased adoption of e-pharmacy platforms in Gulf states markets.
The Latin American market is dominated by the Brazilian market, which continues to drive the adoption of e-pharmacy platforms due to increased digital health infrastructure investments and increased internet penetration. Mexico has made substantial secondary market contributions owing to the continued expansion of the digital health infrastructure investments in the region.
Market Dynamics
Growth Drivers: Rising Digital Penetration and Telemedicine Integration Fuel Market Expansion
Rising internet and smartphone penetration represents the primary driver of E-Pharmacy Market growth, as growing digital access continues to expand the population capable of ordering medications online and managing prescriptions through mobile applications. This structural shift in consumer access is directly translating into rising e-pharmacy platform adoption across both developed and emerging markets, extending the addressable market well beyond its traditional urban, technology-forward consumer base.
Growing integration of telemedicine consultations directly with e-pharmacy fulfillment represents a second major growth driver, as digital prescriptions increasingly flow directly from virtual consultations into online pharmacy fulfillment without requiring a separate in-person pharmacy visit. Clearer regulatory frameworks around telepharmacy policy, including extended exceptions supporting remote prescribing of certain controlled substances, continue to reinforce this integration and expand the range of conditions that can be managed entirely through digital channels.
Restraints: Regulatory Complexity and Counterfeit Product Concerns Hamper Market Growth
The diversity and evolution of regulation for online pharmaceutical sales in various nations and states present significant barriers to market development, with online pharmacies being required to cope with multiple and even conflicting requirements for prescription validation, distribution of controlled substances, and international pharmaceutical trade. The diversity of regulations can lead to slower penetration of online pharmacies into new markets compared to traditional retail pharmacy business.
The consumers concerns about counterfeit or poor quality pharmaceuticals bought via less regulated Internet stores present another barrier, especially in nations where regulation of e-pharmacies is underdeveloped. Requirements for the e-commerce business tend to involve obligatory presentation of quality certification and test badges, which raises the bar of compliance and works to the advantage of larger and better-established businesses.
Opportunities: Subscription-Based Chronic Disease Management and Omnichannel Expansion Create Lucrative Growth Opportunities
Rising adoption of subscription-based models for chronic disease medication management represents a substantial opportunity, as platforms that can offer personalized, automated refill scheduling are positioned to build recurring revenue relationships with patients managing long-term conditions rather than competing solely on one-time transaction pricing. Suppliers that successfully integrate medication reminders, refill automation, and health tracking within a single platform stand to capture disproportionate share of this expanding chronic disease management opportunity.
Expansion through omnichannel approaches that integrate digital capabilities with physical stores will be another way in which growth can be achieved because major platforms have started to use their existing offline stores in addition to digital approaches to provide integrated access to healthcare through both digital orders and physical consultation. Platforms that will be able to do this will be in an excellent position to cater to consumers who want both of these.
Recent Developments:
-
In July 2025, Redcare Pharmacy's CardLink solution for electronic prescription redemption was extended by Gematik, enabling a smooth transition to next-generation digital prescription redemption technology across Germany.
-
In January 2026, Tata 1mg announced a major expansion with nearly 500 offline stores nationwide, extending its omnichannel presence across India's e-pharmacy and healthcare retail market.
-
In February 2026, PharmEasy partnered with Samsung Health to launch a 'Find Care' feature, integrating healthcare provider discovery capability directly within Samsung's health platform ecosystem.
-
In April 2024, NetMeds launched a new mobile application allowing users to order medicines and track order status, extending its digital platform capability for Indian consumers.
E-Pharmacy Market Key Players
-
CVS Health Corporation
-
Walgreens Boots Alliance, Inc.
-
Amazon Pharmacy (Amazon.com, Inc.)
-
Cigna Corporation (Express Scripts)
-
Redcare Pharmacy N.V. (DocMorris)
-
Netmeds (Reliance Retail)
-
Walmart Inc.
-
Optum Rx, Inc.
-
The Kroger Co.
-
Rite Aid Corporation
-
HealthWarehouse.com, Inc.
-
Truepill
-
GoodRx Holdings, Inc.
-
Capsule Corporation
-
Tata 1mg
-
PharmEasy (API Holdings)
-
Giant Eagle, Inc.
-
Corporation of European Pharmaceutical Distributors (CEPD)
-
Rowlands Pharmacy
-
MedPlus Health Services Limited
E-Pharmacy Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 111.68 Billion |
| Market Size by 2035 | USD 543.63 Billion |
| CAGR | CAGR of 17.15% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Drug Type (Prescription (Rx) Medicines, Over-The-Counter (OTC) Products) • By Business Model (Inventory-Based, Marketplace-Based) • By Platform (Mobile/App-Based, Website) • By Therapeutic Area (Pain Management, Cardiovascular Diseases, Diabetes & Metabolic Disorders, Respiratory Disorders, Gastrointestinal Disorders, Dermatology, Women's Health, Mental Health, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | CVS Health Corporation, Walgreens Boots Alliance, Inc., Amazon Pharmacy (Amazon.com, Inc.), Cigna Corporation (Express Scripts), Redcare Pharmacy N.V. (DocMorris), Netmeds (Reliance Retail), Walmart Inc., Optum Rx, Inc., The Kroger Co., Rite Aid Corporation, HealthWarehouse.com, Inc., Truepill, GoodRx Holdings, Inc., Capsule Corporation, Tata 1mg, PharmEasy (API Holdings), Giant Eagle, Inc., Corporation of European Pharmaceutical Distributors (CEPD), Rowlands Pharmacy, MedPlus Health Services Limited |
Frequently Asked Questions
Key players include CVS Health Corporation, Walgreens Boots Alliance, Inc., Amazon Pharmacy, Cigna Corporation (Express Scripts), Redcare Pharmacy N.V., and Netmeds, among other online and omnichannel pharmacy operators.
Rising adoption of subscription-based chronic disease medication management models and continued expansion into omnichannel platforms combining digital and physical pharmacy access represent the primary opportunities.
Growth is primarily driven by rising internet and smartphone penetration combined with growing integration of telemedicine consultations directly with e-pharmacy fulfillment.
By Drug Type, Prescription (Rx) Medicines dominated the market with approximately 68.60% share in 2025, reflecting its role as the foundational, recurring use case driving e-pharmacy platform adoption.
North America dominated the market with approximately 40.60% share in 2025, supported by high internet and smartphone penetration and an established base of technology-driven pharmacy entrants.
