
Eye Tracking Market Report Scope & Overview:
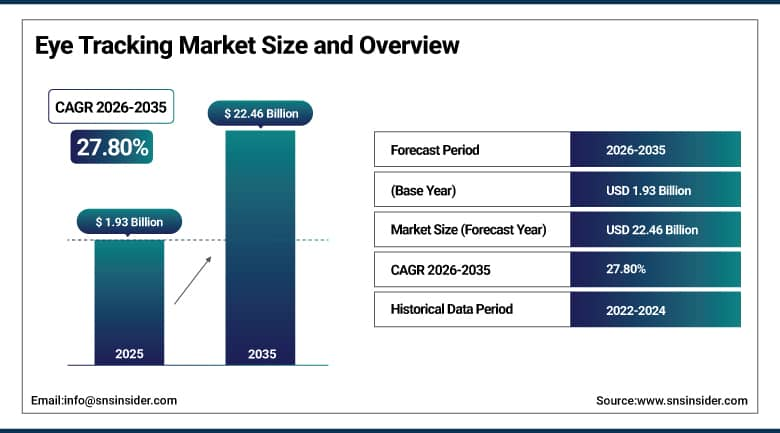
The Eye Tracking Market was valued at USD 1.93 Billion in 2025 and is expected to reach USD 22.46 Billion by 2035, growing at a CAGR of 27.80% from 2026-2035.
The Eye Tracking Market is fuelled by the rising usage of these tracking devices in the automotive safety industry, in the field of augmented and virtual reality systems, and for behavioral analysis based on AI. Modern eye tracking equipment utilizes sophisticated sensor technology and high quality cameras to determine points of gaze, locations of eyes and their movements in an increasing number of practical applications in business and clinical practice. The device utilizes infrared illumination of the pupil and corneal reflection, which is captured using a camera and analyzed by the software, allowing determination of exact gaze location and analysis of cognitive and visual activity and behaviors in marketing, human computer interaction and assistive technologies.
In November 2025, Tobii announced it is providing eye-tracking and interior sensing technology enabling a European automaker's Driver Control Assistance System to perform eye-activated automated lane changes and meet regulatory approval requirements. The announcement illustrates how established eye tracking suppliers continue to extend their technology from research and consumer applications into safety-critical automotive systems, reinforcing the competitive importance of regulatory-grade eye tracking and interior sensing capability as automakers increasingly integrate driver attention monitoring into advanced driver assistance and automated driving features.
To Get More Information On Eye Tracking Market - Request Free Sample Report
Eye Tracking Market Trends
- Rising integration of AI-powered gaze analytics across consumer and enterprise eye tracking platforms.
- Growing adoption of eye-activated automotive safety systems, including driver monitoring and lane-change assistance.
- Expanding use of wearable and head-mounted eye tracking solutions across AR/VR and field research applications.
- Increasing application of eye tracking technology in healthcare diagnostics, including autism spectrum and vision loss research.
- Rising demand for foveated rendering capability enabled by eye tracking in consumer electronics and gaming devices.
- Growing miniaturization of eye tracking components enhancing accessibility across compact consumer devices.
U.S. Eye Tracking Market Outlook
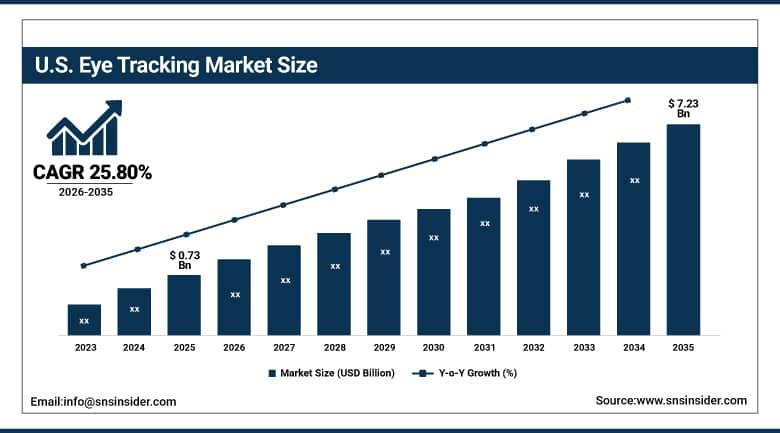
The U.S. Eye Tracking Market was valued at USD 0.73 Billion in 2025 and is expected to reach USD 7.23 Billion by 2035, growing at a CAGR of 25.80% from 2026-2035.
The US Eye Tracking Market expansion has been increasingly fueled by growing use of smart sensors and contactless biometric devices, along with significant application of eye tracking devices in the field of healthcare and scientific research such as psychology, neuroscience and developmental science. The robust presence of eye tracking technology vendors in the US, along with the significant demand for the technology in research institutions and healthcare organizations, has helped maintain the market’s leadership status in the region. Increasing adoption of the technology in consumer electronics, gaming devices and extended reality products has helped in widening the application base of the technology beyond its clinical and scientific roots to the consumer sector.
In December 2024, Himax Technologies, in collaboration with Ganzin Technology, unveiled their eye-tracking solution, Aurora IIS, which debuted at CES 2025 in Las Vegas. The demonstration highlights the ongoing efforts of technology companies to demonstrate the latest eye-tracking technologies at major consumer electronics trade shows in the U.S., underscoring the nation’s importance as an important launch market for cutting-edge eye-tracking technology.
Eye Tracking Market Segment Analysis
- By Type, the optical tracking segment dominated the eye tracking market with approximately 54.30% share in 2025, while the eye attached tracking segment is the fastest growing with a CAGR of approximately 28.00%.
- By Location, the remote segment dominated the eye tracking market with approximately 53.60% share in 2025, while the mobile segment is the fastest growing with a CAGR of approximately 29.80%.
- By Component, the hardware segment dominated the eye tracking market with approximately 54.60% share in 2025, while the software segment is the fastest growing with a CAGR of approximately 29.20%.
- By Application, the healthcare segment dominated the eye tracking market with approximately 26.60% share in 2025, while the gaming segment is the fastest growing with a CAGR of approximately 30.40%.
By Type, Optical Tracking Dominates the Eye Tracking Market and Eye Attached Tracking Grows Fastest
The Optical Tracking segment dominated the eye tracking market in 2025, supported by its high accuracy, non-contact measurement capabilities, and broad compatibility with advanced imaging systems. Optical tracking systems make use of cameras along with infrared lights to track the movement of eyes, gaze direction, and pupil motion without making any direct contact. The continued use of optical tracking in consumer electronics, health care, automotive, research, and human computer interaction systems will lead towards growing market share in the optical tracking segments.
The Eye Attached Tracking segment is expected to register the fastest growth during the forecast period, driven by increasing demand for highly precise and responsive eye-movement measurement. Ocular tracking systems record eye movements through the use of sensors or special devices that are placed near the eyes. These have found application not only in medical research and neuroscience but also in the field of virtual and augmented reality and have created new applications in assistive technology and human-computer interface designs.
By Location, Remote Dominates the Eye Tracking Market and Mobile Grows Fastest
Remote eye trackers dominate the market due to their extensive use in research labs, healthcare, and consumer applications, offering precision and ease of use without requiring wearable devices. Dominance of this sector is further strengthened through its compatibility with current laboratory setup and data processing pipeline, which does not disrupt the workflow and continues to maintain remote eye tracking as the first step for organizations that are looking to use eye tracking technology.
Mobile eye trackers are the fastest-growing type as accelerating adoption of head-mounted and wearable gaze tracking solutions continues to expand across virtual reality, augmented reality, and field research applications. This growth is reinforced by rising automotive driver monitoring system adoption and expanding wearable device applications for business use cases, including employee training and real-time visual insight generation.
By Component, Hardware Dominates the Eye Tracking Market and Software Grows Fastest
Hardware dominates the market because cameras, infrared sensors, and optical components represent the foundational physical technology required for every eye tracking application, from research-grade remote systems to consumer wearable devices. The technical precision and specialized manufacturing required for eye tracking hardware continues to sustain its position as the largest component category across the industry.
Software is the fastest-growing component as AI and machine learning integration increasingly differentiates eye tracking platforms through more sophisticated gaze analytics, behavioral pattern recognition, and predictive capability. This is further fueled by increasing requirements for cloud analytics solutions which convert unstructured eye tracking data into behavioral and cognitive insights for use in healthcare, marketing and research domains.
By Application, Healthcare Dominates the Eye Tracking Market and Gaming Grows Fastest
Healthcare dominates the market as eye tracking technology increasingly supports patient monitoring, cognitive assessment, and clinical research applications, including autism spectrum diagnosis, prosthetic control learning, and vision loss adaptation research. The technology's non-invasive nature and objective, quantifiable data output continue to align with healthcare's broader shift toward evidence-based, personalized medicine, reinforcing healthcare's position as the largest application category.
Gaming is the fastest-growing application as eye tracking increasingly enables foveated rendering, gaze-based controls, and more immersive player interaction across both dedicated gaming hardware and extended reality platforms. This trend is further fueled by increasing integration of eye tracking technology in consumer gaming headsets and screens, as firms try to distinguish their products through more intuitive user interfaces.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.60% |
|
Asia Pacific |
China |
38.60% |
|
Europe |
Germany |
29.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
|
Latin America |
Brazil |
28.60% |
North America Eye Tracking Market Insights
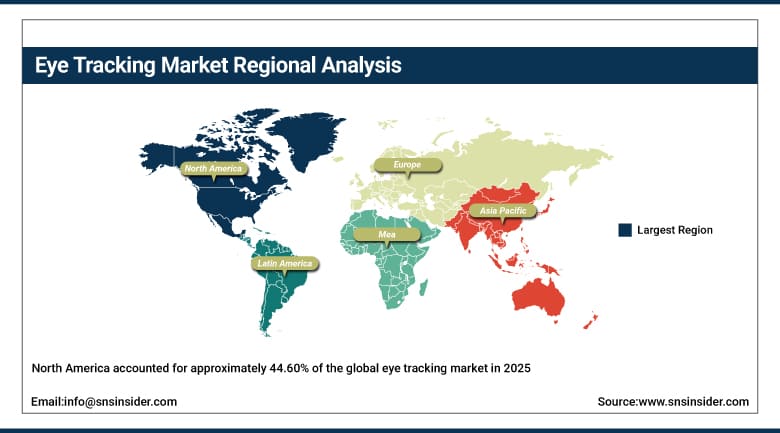
North America accounted for approximately 44.60% of the global eye tracking market in 2025, making it the largest regional market, supported by advanced technological infrastructure and widespread adoption across research, healthcare, marketing, automotive, and human-computer interaction applications. The United States dominates regional demand due to strong investment in AI-driven eye tracking, smart sensors, and contactless biometric technologies, alongside a concentrated presence of established eye tracking solution providers.
The Canadian market is adding to the incremental demand due to more applications of eye tracking technology by research institutes, health care organizations, and technology companies in their research, accessibility, behavior studies, and man-machine interaction. Increasing investments in AI-based gaze analytics, automotive driver monitoring, and immersive technologies are presenting new possibilities in Canada.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Eye Tracking Market Insights
Asia Pacific is the fastest-growing regional market, expanding at a CAGR of approximately 29.60% from 2026 to 2035, driven by rapidly rising consumer electronics demand, expanding retail analytics applications, and growing government and enterprise investment in AI-driven technology across China, Japan, and South Korea. China has maintained its large domestic consumer electronics manufacturing capacity to provide the needed scalability for eye tracking components manufacture.
The other two countries, Japan and South Korea, have provided further scale by virtue of their presence in the consumer electronics industry and the automobile industry, among others, including some eye tracking solutions that they have launched. This combination of consumer electronics demand and automotive safety technology investment is expected to sustain Asia Pacific's position as the fastest-growing market through the forecast period.
Europe Eye Tracking Market Insights
Europe represents a significant share of the global eye tracking market, anchored by Germany's advanced research and development in human-computer interaction and automotive safety, and the region's established base of academic and clinical eye tracking research institutions. European automakers continue to lead in integrating eye tracking and interior sensing technology into advanced driver assistance and automated driving systems.
The United Kingdom, France, and Sweden have provided constant growth in demand because the regional automotive and technology firms have been deploying eye tracking in their commercial automotive products and consumer electronics, expanding from using the technology in research purposes. The regional suppliers are continuously developing technology for driver monitoring and interior sensing to comply with regulations.
MEA & Latin America Eye Tracking Market Insights
The Middle East & Africa eye tracking market remains comparatively small but is expanding gradually as healthcare, academic, and research institutions increase technology investments across the United Arab Emirates and Saudi Arabia. Growing interest in clinical research, behavioral analysis, accessibility, and human-computer interaction is supporting adoption. Nevertheless, the use of regional deployment is still restricted to universities, research institutions, and healthcare facilities owing to limited regional production capacity of eye tracking technology.
Latin America’s eye tracking market is led by Brazil, supported by increasing consumer electronics adoption, academic research investment, and expanding applications in healthcare and human-computer interaction. Mexico is contributing incremental growth as its established automotive manufacturing industry increasingly evaluates driver monitoring and in-cabin sensing technologies. Across the region, adoption remains concentrated among larger research institutions, automotive companies, technology developers, and enterprises with greater capacity to invest in advanced sensing and gaze-analysis solutions.
Market Dynamics
Growth Drivers: Automotive Safety Integration and AR/VR Ecosystem Expansion
The increasing use of eye tracking technology in the automobile sector is the main factor contributing to the growth of the eye tracking market, owing to the need for vehicle safety regulations and increased functionality of advanced driver assistance systems. The increase in the uptake of driver monitoring systems by mass market is driving the eye tracking market beyond its conventional usage in research and consumer electronics markets.
A further growth driver comes in the form of the development and ongoing expansion of the VR/AR ecosystem, where manufacturers of consumer electronics devices are now beginning to incorporate eye tracking to facilitate foveated rendering and gaze interaction. The need for better user experience in gaming and extended reality is driving the increasing application of eye tracking in consumer electronics platforms.
Restraints: High Component Costs and Technical Accuracy Limitations
The cost factor related to the use of expensive eye tracking component parts is a significant limitation of the market growth because the use of sensors and optics for gaze tracking remains a limitation of widespread application due to its cost in consumer electronics. The cost factor contributes to greater use of eye tracking technology in premium consumer electronics and other industries.
Technical accuracy limitations associated with wearable and mobile eye tracking systems represent a further restraint, as these configurations must achieve comparable precision to established remote systems before broader commercial and scientific adoption becomes economically viable at lower price points. Until wearable systems achieve comparable accuracy at lower cost points, remote configurations will continue to serve as the entry point for most organizations exploring eye tracking applications.
Opportunities: Healthcare Diagnostic Expansion and AI-Driven Behavioral Analytics
Continued expansion of eye tracking applications in healthcare diagnostics represents a substantial opportunity, as the technology's non-invasive nature and objective, quantifiable data output increasingly align with evidence-based, personalized medicine approaches across prosthetic control learning, vision loss adaptation, and neurological condition assessment. Suppliers that can develop clinically validated eye tracking diagnostic platforms are positioned to capture demand from healthcare's broader shift toward objective, longitudinal patient monitoring.
The continued integration of AI-enabled gaze analytics across consumer and enterprise platforms offers a further avenue for growth, as businesses increasingly seek to understand human attention and behavior patterns for applications spanning marketing, training, and user experience design. Suppliers that can pair precise gaze detection hardware with sophisticated behavioral analytics software are well positioned to capture demand from this expanding, cross-industry application category.
Recent Developments:
- 2026: Smart Eye entered an agreement to acquire Sightic Analytics, adding behavioral impairment detection capabilities to its eye-tracking and driver-monitoring portfolio.
- 2026: Pupil Labs partnered with NIL Technology to integrate NILT’s ultra-compact metaEye technology into a forthcoming eye-tracking product, supporting smaller form factors and next-generation wearable applications.
- 2026: iMotions expanded its platform with broader VR headset support, improved integration capabilities, and monocular eye-tracking functionality for Smart Eye Trackers, enhancing research flexibility across immersive environments.
Eye Tracking Market Key Players are:
- Tobii AB
- EyeTech Digital Systems, Inc.
- Seeing Machines Limited
- Smart Eye AB
- Pupil Labs GmbH
- iMotions A/S
- Gazepoint Research, Inc.
- SR Research Ltd. (EyeLink)
- Ganzin Technology
- Himax Technologies, Inc.
- LC Technologies, Inc.
- ISCAN Inc.
- Adhawk Microsystems Inc.
- Varjo Technologies Oy
- Meta Platforms, Inc.
- Apple Inc.
- Microsoft Corporation
- Qualcomm Incorporated
- Alphabet Inc.
- Neurable, Inc.
Eye Tracking Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.93 Billion |
| Market Size by 2035 | USD 22.46 Billion |
| CAGR | CAGR of 27.8% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Eye Attached Tracking, Optical Tracking, Electrooculography) • By Location (Remote, Mobile) • By Component (Hardware, Software, Services) • By Application (Healthcare, Automotive, Gaming, AR/VR, Research & Usability Testing, Marketing & Consumer Behavior, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Tobii AB, EyeTech Digital Systems, Inc., Seeing Machines Limited, Smart Eye AB, Pupil Labs GmbH, iMotions A/S, Gazepoint Research, Inc., SR Research Ltd. (EyeLink), Ganzin Technology, Himax Technologies, Inc., LC Technologies, Inc., ISCAN Inc., Adhawk Microsystems Inc., Varjo Technologies Oy, Meta Platforms, Inc., Apple Inc., Microsoft Corporation, Qualcomm Incorporated, Alphabet Inc., Neurable, Inc. |
Frequently Asked Questions
Key players include Tobii AB, EyeTech Digital Systems, Inc., Seeing Machines Limited, Smart Eye AB, Pupil Labs GmbH, and iMotions A/S, among other eye tracking technology suppliers.
Continued expansion of eye tracking applications in healthcare diagnostics and continued integration of AI-enabled gaze analytics across consumer and enterprise platforms represent the primary opportunities.
Growth is primarily driven by expanded automotive safety applications combined with the continued emergence and expansion of virtual reality and augmented reality ecosystems.
By Location, Remote dominated the market with approximately 53.60% share in 2025, reflecting extensive use in research labs, healthcare, and consumer applications.
North America dominated the market with approximately 44.60% share in 2025, fueled by advanced technological infrastructure and significant investment in AI-driven eye tracking solutions.
