
Laboratory Freezers Market Report Scope & Overview:
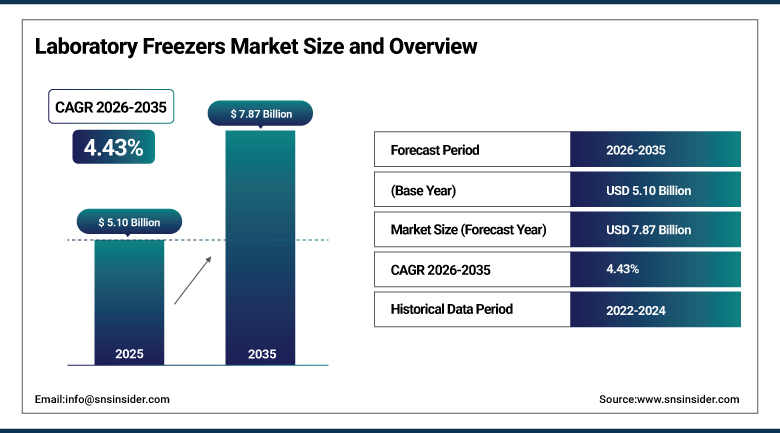
The Laboratory Freezers Market was valued at USD 5.10 Billion in 2025 and is expected to reach USD 7.87 Billion by 2035, growing at a CAGR of 4.43% from 2026-2035.
Laboratory freezers preserve samples, reagents, vaccines, and other temperature-sensitive materials at controlled sub-zero temperatures ranging from a relatively mild -20 degrees Celsius through the extreme -150 degree Celsius range that cryogenic systems provide as an alternative to liquid nitrogen storage. The category spans compact undercounter units used in individual research labs through large upright and chest freezers capable of storing thousands of sample boxes across biobanks, hospital blood banks, and biopharmaceutical manufacturing facilities. Growth is supported by rising demand for biopharmaceuticals, expanding cell and gene therapy pipelines that require carefully controlled cold chain storage at multiple temperature points, and continued investment in healthcare infrastructure across both developed and emerging markets. Energy efficiency has become a defining competitive battleground, as manufacturers race to reduce daily power consumption while meeting increasingly stringent refrigerant regulations, with newer platforms delivering meaningful energy savings over legacy systems that many laboratories are now actively working to replace.
Thermo Fisher Scientific launched its next-generation TSX Universal Series of ultra-low temperature freezers, featuring Universal V-Drive technology, tighter temperature control, quicker recovery times, and a broader range of setpoints, enabling high-use academic labs, GMP facilities, and long-term storage sites to use the same unit across diverse workflows while supporting sustainability goals through potential energy savings of up to 33%.
To Get more information Laboratory Freezers Market - Request Free Sample Report
Laboratory Freezers Market Trends
-
Rising adoption of hydrocarbon and other low global-warming-potential refrigerants replacing legacy refrigerant chemistries.
-
Growing demand for cryogenic chest freezers as a practical alternative to liquid nitrogen storage systems.
-
Expanding use of IoT-enabled remote monitoring and centralized alarm systems across distributed freezer fleets.
-
Increasing preference for modular, right-sized freezer arrays over single large monolithic storage cabinets.
-
Rising energy efficiency competition as manufacturers pursue ENERGY STAR and equivalent certification standards.
-
Growing investment in portable, field-deployable ultra-low temperature units supporting remote vaccination campaigns.
U.S. Laboratory Freezers Market Overview
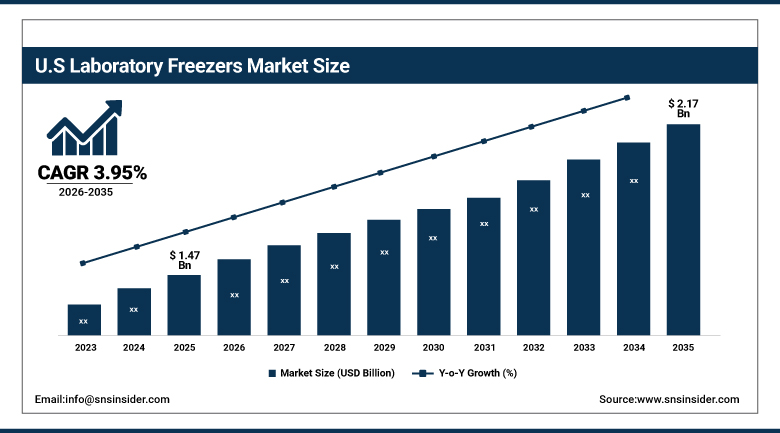
The U.S. Laboratory Freezers Market was valued at USD 1.47 Billion in 2025 and is expected to reach USD 2.17 Billion by 2035, growing at a CAGR of 3.95% from 2026-2035.
The U.S. Laboratory Freezers Market benefits from substantial biopharmaceutical manufacturing capacity, an extensive network of academic and government research institutions, and the presence of leading freezer manufacturers headquartered in the country that continue to compete on energy efficiency, reliability, and total cost of ownership. Continued Food and Drug Administration approval activity for biologics and advanced therapies continues to expand the addressable base of facilities requiring ultra-low temperature and cryogenic storage capacity, while rising cell and gene therapy commercialisation is driving genuinely new demand for specialised storage equipment beyond conventional sample archiving. Leading manufacturers continue to introduce next-generation platforms offering tighter temperature control and meaningful energy savings, positioning their products to serve both greenfield biobanking facilities and the substantial replacement market represented by ageing freezer fleets across academic and clinical research institutions.
Thermo Fisher Scientific reported that its TSX Universal Series ultra-low temperature freezers, part of its broader controlled temperature technologies portfolio, are being adopted across academic laboratories, GMP manufacturing facilities, and long-term storage operations seeking a single adaptable platform capable of switching between high-performance and energy-saving operating modes depending on workflow demands.
Laboratory Freezers Market Segment Analysis
-
By Product Type, the Ultra-Low Temperature Freezers segment dominated the market with a 44.80% share in 2025, while the Ultra-Low Temperature Freezers segment is the fastest growing with a CAGR of 6.55% during 2026-2035.
-
By Cabinet Design, the Upright segment dominated the market with a 58.90% share in 2025, while the Chest segment is the fastest growing with a CAGR of 5.35% during 2026-2035.
-
By Temperature Range, the Below -80 Degrees Celsius segment dominated the market with a 39.75% share in 2025, while the -40 to -80 Degrees Celsius segment is the fastest growing with a CAGR of 5.85% during 2026-2035.
-
By Application, the Biological Sample Storage segment dominated the market with a 36.20% share in 2025, while the Genetic and Genomic Research segment is the fastest growing with a CAGR of 6.25% during 2026-2035.
-
By End User, the Pharmaceutical and Biotechnology Companies segment dominated the market with a 34.95% share in 2025, while the Cell and Tissue Banks segment is the fastest growing with a CAGR of 6.75% during 2026-2035.
By Product Type, Ultra-Low Temperature Freezers Dominates the Market and Ultra-Low Temperature Freezers Grows Fastest
Ultra-low temperature freezers dominated the market in 2025 with a 44.80% share, and these systems, typically operating at or below -80 degrees Celsius, remain the essential storage backbone for biological samples, cell lines, and increasingly cell and gene therapy products that lose viability at less extreme temperatures. Biobanks, national reference laboratories, and biopharmaceutical manufacturers all depend on this equipment category as the foundation of their broader sample and material preservation strategy, and the sheer breadth of applications that require this level of cold, spanning everything from long-term tissue archiving through active vaccine cold chain distribution, continues to keep ultra-low temperature systems at the centre of laboratory capital equipment budgets. The category also benefits from the longest and most established replacement cycle of any freezer type, since facilities that have already standardised on ultra-low temperature infrastructure rarely migrate away from it once workflows and validation protocols are built around a specific platform.
Ultra-low temperature freezers are also expected to grow fastest over the forecast period, registering a CAGR of 6.55%, as expanding biologics and cell therapy storage infrastructure continues to drive sustained investment in this category ahead of every other product type. Continued rollout of next-generation platforms offering tighter temperature control, faster recovery times, and meaningful energy savings continues to reinforce this segment's already dominant position even further relative to deep freezers, cryogenic systems, and refrigeration alternatives, and the fact that this category is simultaneously the largest and the fastest-growing underscores just how central ultra-low temperature storage has become to the broader life sciences cold chain, particularly as more biologics and cell-based therapies enter commercial production and require dependable, validated storage capacity at scale rather than the smaller volumes typical of pure research settings.
By Cabinet Design, Upright Dominates the Market and Chest Grows Fastest
Upright freezers dominated the market in 2025 with a 58.90% share. Their vertical, shelf-based organisation continues to make sample retrieval and inventory management considerably easier than chest-style alternatives, a practical advantage that matters enormously in busy laboratories where staff need to locate specific samples quickly without disturbing the broader stored inventory around them. Upright designs also integrate more naturally into standard laboratory floor plans and rack-based storage systems, allowing facilities to organise inventory by project, patient, or sample type in a way that mirrors how staff actually think about their work, and this ergonomic and organisational advantage continues to outweigh the somewhat higher energy consumption upright cabinets typically carry relative to chest designs of comparable capacity.
Chest freezers are projected to be the fastest-growing cabinet design over the forecast period, registering a CAGR of 5.35%, as their generally lower cost per unit of storage capacity and improved thermal efficiency relative to upright designs continue to appeal to facilities prioritising bulk, long-term archival storage over frequent, rapid sample access. Because cold air naturally settles rather than escaping every time the lid opens, chest freezers lose less cooling capacity per access event than upright units, and this physical efficiency advantage becomes increasingly valuable as facilities scale toward larger storage volumes where energy cost accumulates meaningfully across dozens or hundreds of individual units operating around the clock.
By Temperature Range, Below -80 Degrees Celsius Dominates the Market and -40 to -80 Degrees Celsius Grows Fastest
The below -80 degrees Celsius temperature range dominated the market in 2025 with a 39.75% share. This extreme cold range remains essential for preserving the biological integrity of RNA, certain cell lines, and increasingly sensitive gene and cell therapy products that would otherwise degrade at less extreme storage temperatures, and clinical and research protocols across an enormous range of applications specify this temperature threshold as a non-negotiable requirement rather than a preference. Regulatory and accreditation bodies governing biobanking and clinical laboratory operations frequently mandate specific validated temperature ranges for sample storage, and this compliance requirement continues to sustain demand for below -80 degree systems even as somewhat less extreme alternatives become available for applications with less stringent preservation needs.
The -40 to -80 degrees Celsius range is projected to be the fastest-growing temperature category over the forecast period, registering a CAGR of 5.85%, as expanding vaccine storage requirements and mid-range biologics preservation needs continue to widen demand for this temperature band, which offers a genuinely practical balance between preservation performance and lower energy consumption relative to more extreme ultra-low temperature systems. As more vaccine formulations and biologic products are developed and validated for storage at these somewhat less extreme temperatures, facilities increasingly find they can meet clinical requirements while reducing both capital and operating cost relative to deploying the most extreme cold systems for every application regardless of actual preservation need.
By Application, Biological Sample Storage Dominates the Market and Genetic and Genomic Research Grows Fastest
Biological sample storage dominated the market in 2025 with a 36.20% share. This broad application category, spanning tissue samples, cell lines, and biological specimens across hospitals, biobanks, and research institutions, continues to represent the foundational use case around which the laboratory freezer industry was originally built, and the sheer diversity of specimen types and research programs that fall under this umbrella continues to generate steady, broad-based demand that touches nearly every type of laboratory and healthcare facility regardless of specialty or research focus. Long-term biobanking initiatives, which can store samples for decades in support of longitudinal research studies, continue to add a particularly durable layer of demand that persists independent of shorter-term research funding cycles.
Genetic and genomic research is projected to be the fastest-growing application over the forecast period, registering a CAGR of 6.25%, as the shift toward personalised medicine and cell-based research continues to require reliable, precisely controlled storage for nucleic acid samples and genetic material used in increasingly sophisticated diagnostic and therapeutic research programs. The rapid expansion of genomic sequencing capacity worldwide, combined with growing pharmaceutical and academic investment in gene therapy and precision oncology research, continues to generate a steadily expanding population of genetic material requiring dependable long-term storage, and this application's above-market growth reflects the genuinely accelerating pace of genomic science relative to more established, slower-growing biobanking applications.
By End User, Pharmaceutical and Biotechnology Companies Dominates the Market and Cell and Tissue Banks Grows Fastest
Pharmaceutical and biotechnology companies dominated the market in 2025 with a 34.95% share. Biologics, vaccine, and increasingly cell and gene therapy manufacturing all require extensive, reliable cold storage infrastructure across multiple temperature points, and this substantial and growing manufacturing base continues to anchor pharmaceutical and biotechnology companies as the largest end-user category across the broader market. These organisations typically operate the largest individual freezer fleets of any end-user category, often spanning multiple manufacturing sites and distribution centres, and their purchasing decisions carry substantial weight for manufacturers given the scale and recurring nature of the equipment and validation services these facilities require throughout a product's commercial lifecycle.
Cell and tissue banks are projected to be the fastest-growing end-user category over the forecast period, registering a CAGR of 6.75%, as rising cell therapy and regenerative medicine commercialisation continues to expand demand for specialised, high-reliability storage capacity capable of preserving increasingly valuable biological material over extended periods without compromise. Because a single cell therapy batch can represent an enormous financial and clinical investment, and because a storage failure can mean an irreplaceable loss for an individual patient's treatment, these facilities are increasingly willing to invest in redundant, closely monitored storage infrastructure that goes well beyond what conventional biobanking applications have historically required, reinforcing this end-user category's above-market growth trajectory.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
North America |
United States |
82.90% |
|
Europe |
Germany |
27.60% |
|
Asia Pacific |
China |
35.85% |
|
Latin America |
Brazil |
23.70% |
|
Middle East & Africa |
United Arab Emirates |
20.15% |
North America Laboratory Freezers Market Insights
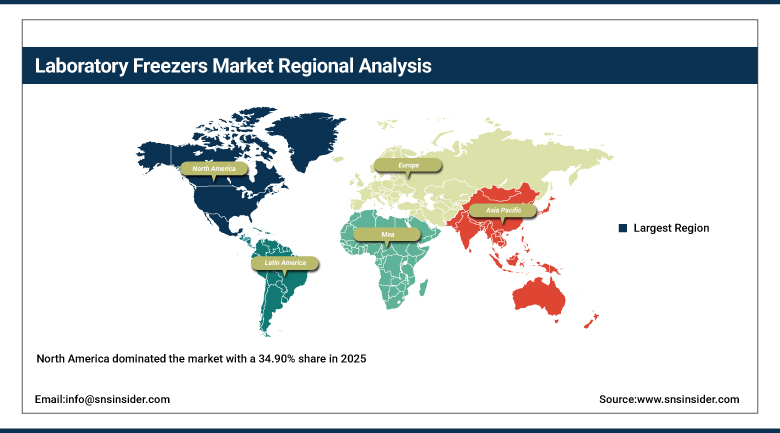
North America dominated the market with a 34.90% share in 2025. Substantial biopharmaceutical manufacturing capacity, an extensive network of academic and government research institutions, and the concentration of leading freezer manufacturers headquartered within the region continue to anchor this leadership position across every major product category. The region's deep base of venture-backed biotechnology companies and well-established contract manufacturing organisations continues to generate sustained capital equipment demand, and the presence of the world's largest life sciences funding ecosystem, spanning both public research grants and private biotechnology investment, continues to support ongoing laboratory infrastructure expansion that keeps freezer capacity growing even as individual facility budgets fluctuate year to year.
Canada contributes meaningful incremental regional demand through its own growing biotechnology and research sector, supported by government-backed innovation funding programs that continue to expand domestic laboratory infrastructure. Continued investment in cell and gene therapy manufacturing capacity, combined with sustained biobanking infrastructure expansion across major academic medical centres, is expected to keep North America in the lead through the forecast period, even as its growth rate trails the faster-scaling markets of Asia Pacific, where healthcare infrastructure is expanding from a comparatively smaller installed base.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Laboratory Freezers Market Insights
Asia Pacific is estimated to grow at the highest rate over the forecast period, registering a projected CAGR of approximately 6.15%, as rapidly expanding biopharmaceutical manufacturing capacity, growing healthcare infrastructure investment, and rising vaccine and biologics storage requirements continue to accelerate regional adoption of advanced laboratory freezer technology. Regional governments across several major economies have made biotechnology and life sciences manufacturing an explicit strategic priority, backing this ambition with substantial public investment in research parks, manufacturing incentives, and academic research funding that continues to translate directly into new laboratory and cold storage capacity across the region.
China anchors regional demand through its expanding domestic biopharmaceutical manufacturing base and growing biobanking infrastructure, supported by sustained government investment aimed at building genuine self-sufficiency across the domestic life sciences supply chain. Japan and South Korea contribute additional regional depth through established research and diagnostics sectors with decades of laboratory infrastructure investment behind them, while India's rapidly expanding vaccine manufacturing and distribution infrastructure continues to add meaningful incremental regional growth as the country builds out its position as a major global vaccine production hub.
Europe Laboratory Freezers Market Insights
Europe holds a significant share of the global market, anchored by Germany's substantial biopharmaceutical manufacturing base and its position as home to leading laboratory equipment manufacturers with deep cold chain engineering expertise built over decades of serving demanding clinical and industrial customers. The region's mature research and healthcare infrastructure continues to sustain steady demand across every major freezer category, reinforced by a dense network of academic medical centres and publicly funded research institutes that maintain consistent equipment replacement and expansion budgets even during periods of broader economic uncertainty.
The United Kingdom, France, and the Nordic countries add consistent regional demand as national biobanking and research infrastructure continues to expand, supported by strong national biobank initiatives that in several cases represent some of the largest coordinated sample collection efforts anywhere in the world. Continued regional investment in sustainable, energy-efficient refrigeration technology, reinforced by tightening European environmental regulation around refrigerant chemistries, is expected to sustain steady growth across the broader European market through the forecast period, with sustainability credentials increasingly influencing procurement decisions at major research institutions.
MEA and Latin America Laboratory Freezers Market Insights
The Middle East and Africa region is supported by growing vaccine cold chain infrastructure investment across the United Arab Emirates and Saudi Arabia, where regional governments continue expanding healthcare and biobanking capacity as part of broader economic diversification and public health modernisation strategies. Regional public health authorities have placed particular emphasis on strengthening vaccine distribution infrastructure following recent global health emergencies, and this policy priority continues to translate into sustained government procurement of properly validated cold storage equipment across the region's expanding network of hospitals and public health facilities.
Latin America is anchored by Brazil, where a growing domestic biopharmaceutical and research sector sustains steady demand for laboratory freezer technology, supported by the country's substantial public health infrastructure and its role as a regional pharmaceutical manufacturing hub. Mexico contributes further incremental growth as regional healthcare infrastructure and vaccine distribution capacity continue to expand gradually, and the broader region's growing integration into global pharmaceutical supply chains continues to raise the baseline standard of cold storage infrastructure facilities across the region are expected to maintain.
Market Dynamics
Growth Drivers: Biopharmaceutical Expansion and Cell Therapy Storage Needs
Increasing demand for biopharmaceuticals stands as the primary growth driver, as expanding biologics, vaccine, and advanced therapy manufacturing pipelines continue to require reliable, precisely controlled cold storage capacity at multiple distinct temperature points spanning conventional refrigeration through extreme ultra-low and cryogenic ranges. Every new biologic that receives regulatory approval effectively creates its own dedicated cold chain requirement, spanning manufacturing, quality control, distribution, and often clinical administration, and the sheer volume of biologics currently in development across the global pharmaceutical pipeline continues to represent a substantial, multi-year tailwind for laboratory freezer demand well beyond what any single product approval could generate on its own.
Rising investments in healthcare infrastructure represent a second major driver, as governments and private healthcare systems worldwide continue expanding hospital, laboratory, and biobanking capacity to meet growing patient populations and rising standards of care. Expansion of biologics and cell therapy storage infrastructure continues to reinforce this trend, as these increasingly valuable therapies demand storage reliability and redundancy that legacy freezer fleets, many of which were designed decades ago for far simpler research sample storage needs, were never originally engineered to provide at the scale and consistency modern advanced therapy manufacturing now requires.
Restraints: High Operating Costs and Energy Consumption Concerns
High operating costs and substantial energy consumption remain a genuine restraint, as ultra-low temperature and cryogenic freezers continue to require considerable electricity to maintain extreme sub-zero temperatures continuously, twenty-four hours a day, every day of the year, a cost burden that can strain operating budgets for smaller laboratories and research institutions operating with limited facility funding, particularly in regions where electricity costs have risen meaningfully in recent years alongside broader energy market volatility.
Refrigerant regulation compliance presents a further restraint, as tightening environmental rules governing high global-warming-potential refrigerants continue to require manufacturers and laboratory operators alike to navigate an evolving regulatory landscape, adding cost and complexity to both new equipment purchases and the ongoing servicing of existing freezer fleets that may rely on refrigerant chemistries increasingly falling out of regulatory favour, forcing some facilities into earlier-than-planned equipment replacement cycles simply to remain compliant with jurisdictions where they operate.
Opportunities: Energy-Efficient Technology and Distributed Storage Architecture
Continued development of energy-efficient, low global-warming-potential refrigeration technology represents a substantial opportunity, as manufacturers that can deliver genuinely lower daily energy consumption while maintaining reliable, precise temperature control stand to capture demand from laboratories increasingly prioritising sustainability alongside cost and performance in their capital equipment decisions, particularly as institutional sustainability commitments increasingly extend down to individual departmental purchasing choices rather than remaining a purely corporate-level policy statement.
Continued adoption of modular, distributed freezer architecture offers a further avenue for growth, as manufacturers that can deliver centralised remote monitoring across arrays of smaller, right-sized units rather than single large monolithic cabinets are positioned to capture demand from laboratories seeking genuine redundancy and risk mitigation for increasingly valuable stored biological material, a design philosophy that also happens to align well with the field-deployable, portable storage solutions increasingly demanded by decentralised vaccination and clinical trial programs operating outside traditional fixed laboratory settings.
Recent Developments:
-
In June 2025, Haier Biomedical launched its UltraEco ultra-low temperature freezer, featuring ENERGY STAR certification and daily energy consumption of 4.16 kilowatt-hours, alongside a hydrocarbon-refrigerant-based platform designed to meet tightening environmental regulations.
-
In 2025, Haier Biomedical secured a significant funding round to accelerate development of energy-efficient, AI-enabled ultra-low temperature freezers, reinforcing its strategy of strengthening distribution across Africa and Latin America alongside expanded remote monitoring platform capability.
Laboratory Freezers Market Key Players
-
Thermo Fisher Scientific Inc.
-
Haier Biomedical
-
PHC Holdings Corporation
-
Eppendorf SE
-
Helmer Scientific
-
Stirling Ultracold (Azbil Corporation)
-
So-Low Environmental Equipment Co.
-
Follett Products, LLC
-
B Medical Systems
-
Labcold Ltd.
-
Liebherr-International AG
-
Vestfrost Solutions
-
Arctiko A/S
-
Cole-Parmer Instrument Company, LLC
-
Binder GmbH
-
Angelantoni Life Science S.r.l.
-
Zhongke Meiling Cryogenics Co., Ltd.
-
BioLife Solutions, Inc.
-
Avantor, Inc.
-
New Brunswick Scientific (Eppendorf)
Laboratory Freezers Market Report Scope:
| Report Attributes | Details |
| Market Size in 2025 | USD 5.10 Billion |
| Market Size by 2035 | USD 7.87 Billion |
| CAGR | CAGR of 4.43% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Product Type (Ultra-Low Temperature Freezers, Deep Freezers, Cryogenic Freezers, and Blood Bank and Chromatography Refrigerators) • by Cabinet Design (Upright and Chest) • by Temperature Range (Below -80 Degrees Celsius, -40 to -80 Degrees Celsius, and -20 to -40 Degrees Celsius) • by Application (Biological Sample Storage, Vaccine Storage, Genetic and Genomic Research, and Blood Banking) • by End User (Pharmaceutical and Biotechnology Companies, Hospitals and Blood Banks, Academic and Research Institutes, and Cell and Tissue Banks) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Thermo Fisher Scientific Inc., Haier Biomedical, PHC Holdings Corporation, Eppendorf SE, Helmer Scientific, Stirling Ultracold (Azbil Corporation), So-Low Environmental Equipment Co., Follett Products, LLC, B Medical Systems, Labcold Ltd., Liebherr-International AG, Vestfrost Solutions, Arctiko A/S, Cole-Parmer Instrument Company, LLC, Binder GmbH, Angelantoni Life Science S.r.l., Zhongke Meiling Cryogenics Co., Ltd., BioLife Solutions, Inc., Avantor, Inc., New Brunswick Scientific (Eppendorf) |

Frequently Asked Questions
Key players include Thermo Fisher Scientific Inc., Haier Biomedical, PHC Holdings Corporation, Eppendorf SE, and Helmer Scientific, among other cold storage equipment manufacturers.
Continued development of energy-efficient, low global-warming-potential refrigeration technology and continued adoption of modular, distributed storage architecture represent the primary opportunities.
Growth is primarily driven by increasing demand for biopharmaceuticals, combined with rising investments in healthcare infrastructure worldwide.
By Product Type, Ultra-Low Temperature Freezers dominated the market with a 44.80% share in 2025, reflecting their essential role in biological sample and therapy storage.
North America dominated the market with a 34.90% share in 2025, supported by substantial biopharmaceutical manufacturing capacity and extensive research infrastructure.
