
Laboratory Equipment Market Report Scope & Overview:
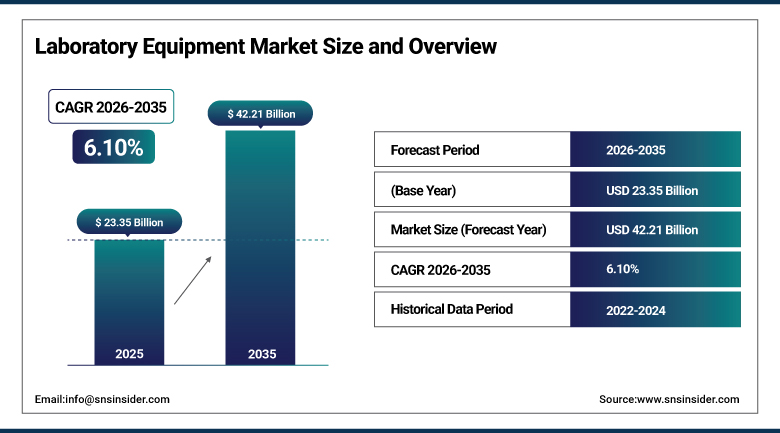
The Laboratory Equipment Market was valued at USD 23.35 Billion in 2025 and is expected to reach USD 42.21 Billion by 2035, growing at a CAGR of 6.10% from 2026-2035.
The Laboratory Equipment Market is expanding steadily as pharmaceutical research, clinical testing and quality control programs require more analytical, sample preparation and automation systems. The market covers the instruments and devices used for analysis, testing, sample preparation, imaging and research in laboratories, including chromatography and spectroscopy systems, microscopes, centrifuges, incubators, balances and automation platforms. Buyers include pharmaceutical and biotechnology companies, hospitals and diagnostic laboratories, universities, and industrial and environmental testing facilities. Demand is supported by drug discovery spending, clinical testing volumes, quality control requirements and a shift toward automated, connected workflows. Replacement of aging instruments and rising biologics development add to purchases across pharmaceutical, clinical, academic and industrial laboratories.
⮞In August 2025, Agilent Technologies launched the Dako Omnis 110, 165 and 165 Duo staining platforms for pathology laboratories, aimed at higher throughput and more consistent results in tissue analysis. The launch reflects how instrument makers are moving beyond stand-alone devices toward automated systems that reduce manual steps and staffing pressure in diagnostic laboratories.
To Get more information Laboratory Equipment Market - Request Free Sample Report
Laboratory Equipment Market Trends
- Laboratory automation and robotics integration
- Growth of online purchasing of instruments and supplies
- Demand for high-throughput analytical instruments in pharma and biotech
- Miniaturized, benchtop and in-process analytical systems
- Connected instruments and data management software
- Sustainability focus on energy-efficient equipment
- Rise of leasing, refurbished and subscription-based equipment models
U.S. Laboratory Equipment Market Outlook
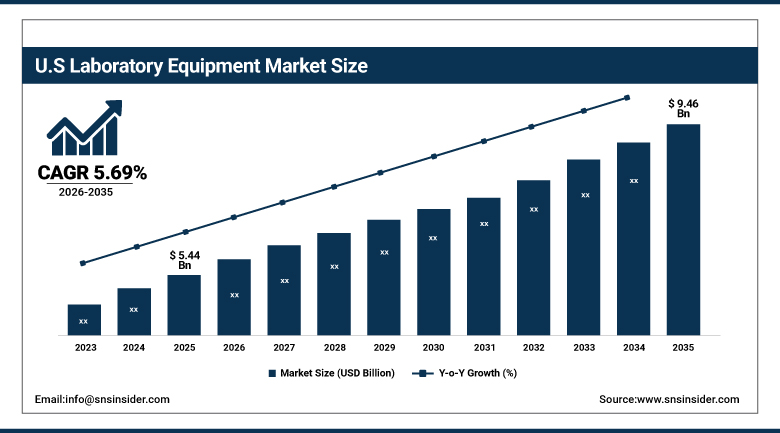
The U.S. Laboratory Equipment Market was valued at USD 5.44 Billion in 2025 and is expected to reach USD 9.46 Billion by 2035, growing at a CAGR of 5.69% from 2026-2035.
The U.S. Laboratory Equipment Market is the largest national market, supported by the world's biggest pharmaceutical and biotechnology sector, extensive federal research funding, a large hospital laboratory network and a strong base of instrument manufacturers. Demand centers on analytical instruments, automation and genomics platforms, and purchasing cycles are influenced by research budgets, drug development pipelines and laboratory modernization programs.
⮞In January 2025, Becton Dickinson and Biosero announced a collaboration to integrate robotic arms with BD flow cytometers, enabling hands-free sample handling in high-throughput laboratories. The move shows U.S. vendors combining instruments with robotics to meet drug-discovery and clinical demand.
Laboratory Equipment Market Segment Analysis
- By Equipment Type, analytical instruments segment dominated the Laboratory Equipment Market in 2025 with 45.70% share; laboratory instruments segment is the fastest-growing segment, with an estimated CAGR of 6.40% during 2026–2035.
- By Automation Level, semi-automatic segment dominated the Laboratory Equipment Market in 2025 with an estimated 42.00% share; automatic segment is the fastest-growing segment, with an estimated CAGR of 7.40% during 2026–2035.
- By End Use, pharmaceutical and biotechnology segment dominated the Laboratory Equipment Market in 2025 with an estimated 34.00% share; clinical and diagnostic segment is the fastest-growing segment, with an estimated CAGR of 7.00% during 2026–2035.
- By Distribution Channel, offline segment dominated the Laboratory Equipment Market in 2025 with 68.50% share; online segment is the fastest-growing segment, with an estimated CAGR of 7.20% during 2026–2035.
By Equipment Type, Analytical Instruments Dominate Laboratory Equipment Market; Laboratory Instruments to Register Fastest Growth.
Analytical instruments dominate the Laboratory Equipment Market because chromatographs, mass spectrometers, spectrometers and thermal analysis systems underpin drug development, quality control, environmental testing and food safety work. These systems carry high unit prices, and regulated laboratories must keep them qualified, calibrated and serviced, which makes replacement and upgrade cycles comparatively predictable. Vendors continue to launch faster, more sensitive platforms with simpler software, and each generation prompts buyers to refresh installed fleets to keep validated methods current. Service revenue from calibration, validation and spare parts adds to the appeal of this category for suppliers.
General laboratory instruments such as centrifuges, incubators, shakers, balances, freezers and sample preparation devices are projected to register the fastest growth. Expanding laboratory capacity, biologics production and clinical testing add units, while connected features such as temperature logging, barcode tracking and remote monitoring raise average selling prices. Other equipment, including safety cabinets and ancillary devices, tends to follow laboratory construction and refurbishment cycles, so its growth is steadier but slower than that of core benchtop instruments. Suppliers also extend benchtop ranges with compact formats suited to smaller laboratories and teaching settings.
By Automation Level, Semi-Automatic Equipment Dominates Laboratory Equipment Market; Automatic Equipment to Register Fastest Growth.
Semi-automatic equipment dominates the Laboratory Equipment Market because it balances throughput and flexibility at a price most laboratories can justify. Pipetting stations, plate washers, benchtop analyzers and sample preparation devices let technicians automate repetitive steps while retaining control over method changes. Buyers often begin with semi-automatic units and add modules over time, which spreads capital expenditure and suits research settings where protocols change frequently and sample volumes vary from week to week. Modular designs allow later upgrades without replacing the full system, which protects earlier investments.
Fully automatic platforms are projected to register the fastest growth as laboratories face labor shortages and need higher throughput and reproducibility. Robotic sample handling, liquid handlers, integrated workcells and scheduling software reduce manual error and allow around-the-clock operation. Partnerships between instrument makers and robotics firms, together with open architectures that allow instruments from different vendors to be orchestrated by a single scheduling layer, are making automation accessible to mid-sized laboratories that previously relied on manual or semi-automatic workflows. Staffing shortages in clinical and quality control laboratories are a further reason for adoption.
By End Use, Pharmaceutical and Biotechnology Dominates Laboratory Equipment Market; Clinical and Diagnostic to Register Fastest Growth.
Pharmaceutical and biotechnology users dominate the Laboratory Equipment Market because drug discovery, development and quality control require large and varied equipment fleets. Growth in biologics, cell and gene therapy and contract research increases purchases of analytical instruments, bioprocess equipment and automation, and companies often standardize on a few vendors to simplify validation. Regulators expect documented data integrity and reproducibility, which favors well-qualified instrument fleets and supports regular investment in upgrades. Procurement is often centralized, with framework agreements covering instruments, consumables and service.
Clinical and diagnostic laboratories are projected to register the fastest growth as testing volumes rise with aging populations, chronic disease and precision medicine. Hospitals and reference laboratories are consolidating into large central facilities that invest in automated analyzers, molecular platforms and pathology systems to improve throughput and consistency. Academic and research, food and beverage, and chemical and materials laboratories grow steadily, supported by research funding, safety testing rules and materials development, though funding cycles make their purchasing less even. Government programs that expand hospital capacity add further momentum for the segment.
By Distribution Channel, Offline Dominates Laboratory Equipment Market; Online to Register Fastest Growth.
Offline channels dominate the Laboratory Equipment Market because high-value instruments require demonstrations, installation, training and service contracts delivered by direct sales teams and distributors. Procurement rules at hospitals, universities and regulated manufacturers favor established vendor relationships, tendering processes and long-term maintenance agreements. Distributors and manufacturers also provide financing, leasing and preventive maintenance schedules that support repeat orders for analytical systems, automation platforms and other capital equipment. Hospital and university buyers also value local service engineers, rapid spare-part availability and training included in contracts.
Online sales are projected to register the fastest growth as buyers purchase benchtop equipment, accessories and consumables through vendor portals and marketplaces. Price transparency, quick delivery and digital catalogs appeal to smaller laboratories and academic buyers, while manufacturers connect e-commerce portals to laboratory inventory and procurement systems so that routine reorders and quotations can be handled without a sales visit. Vendors increasingly pair online catalogs with remote support and subscription-based consumable plans. Digital catalogs make it easier for new buyers to compare specifications and prices across vendors.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
69.30 |
|
Asia Pacific |
China |
44.00 |
|
Europe |
Germany |
28.00 |
|
Latin America |
Brazil |
47.00 |
|
Middle East & Africa |
Saudi Arabia |
24.00 |
North America Laboratory Equipment Market Insights
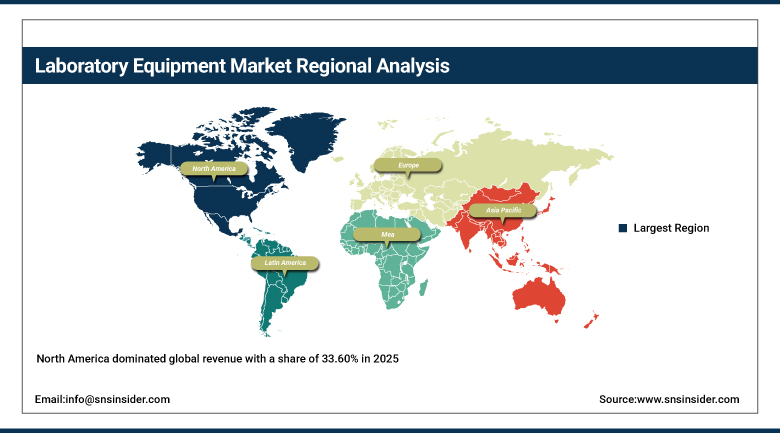
North America dominated global revenue with a share of 33.60% in 2025, supported by large research budgets, a deep biotechnology industry and a concentration of leading instrument makers such as Thermo Fisher Scientific, Danaher and Becton, Dickinson. The United States accounts for most regional demand, and Canada adds steady purchases through life sciences clusters in Toronto, Montreal and Vancouver. Several of the largest laboratory networks and contract research organizations are headquartered in the region, which concentrates purchasing power.
Replacement of aging equipment in public health and university laboratories, supported by periodic federal and state funding, provides a stable order base. Tariff discussions, supply-chain localization and variability in federal research grants can delay purchasing decisions, while hospital consolidation concentrates buying power and puts pressure on prices. Vendors respond with service contracts, leasing and automation bundles that help laboratories manage budgets and staffing shortages. Growth in the region is also tied to biologics manufacturing investments and expanded genomic testing capacity.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Laboratory Equipment Market Insights
Asia Pacific is the second-largest region and is projected to be the fastest-growing, at a CAGR of 6.70% from 2026-2035. China leads regional demand through pharmaceutical manufacturing, government research funding and hospital build-out, followed by Japan, India and South Korea. India's growing generic drug industry and clinical research sector, together with Japan's long-standing instrument makers such as Shimadzu and Hitachi High-Tech, add depth to regional demand. Contract research and manufacturing organizations are also establishing sites in the region to serve global drug developers.
South Korea's biopharmaceutical expansion, Singapore's research institutes and Australia's biomedical manufacturing add specialized purchases, while Taiwan supports semiconductor and materials testing. Local manufacturers offer lower-cost instruments that broaden adoption, and rising local content requirements are encouraging global vendors to assemble and service systems closer to customers. Government initiatives to localize pharmaceutical production and build national research facilities are expected to keep orders rising through the forecast period. Regional distributors and training programs are expanding to support users and shorten service response times.
Europe Laboratory Equipment Market Insights
Europe is a mature, quality-driven market where Germany leads, followed by the United Kingdom, France, Switzerland and Italy. Germany stands out for analytical instrumentation and precision engineering, Switzerland for pharmaceutical production, balances and liquid handling, and the United Kingdom for academic and clinical research. Suppliers such as Sartorius, Eppendorf, Mettler-Toledo and Metrohm are headquartered in the region and supply customers worldwide. Strong university research networks and a large base of pharmaceutical quality control laboratories keep orders consistent. Pharmaceutical hubs in Basel, Dublin and Copenhagen add specialized demand.
The European Union's regulatory framework for in vitro diagnostics and the push to modernize pharmaceutical manufacturing encourage investment in validated analytical systems, while public research programs sustain academic purchases. Contract research and manufacturing hubs in Ireland, Belgium and the Netherlands draw further investment. Sustainability goals are prompting laboratories to prefer energy-efficient freezers, fume hoods and solvent-saving chromatography systems, which supports upgrade cycles even where budgets are tight. Budget pressure in public research and the maturity of installed bases moderate growth relative to Asia Pacific.
MEA & Latin America Laboratory Equipment Market Insights
In Latin America, Brazil leads on the strength of hospital laboratories, pharmaceutical manufacturing and agricultural testing, followed by Mexico, whose medical device and pharmaceutical manufacturing base adds demand, and by Argentina and Colombia, where clinical laboratories are expanding. Chile and Peru add purchases through mining and environmental testing laboratories that require spectroscopy and sample preparation equipment. Public health programs for infectious disease and growing private diagnostic chains also add to equipment demand across the region. Argentina's research institutes also contribute modest demand.
In the Middle East and Africa, the United Arab Emirates, Saudi Arabia and Qatar are investing in hospital and research infrastructure aligned with national health and economic diversification strategies. Egypt, Turkey and South Africa host expanding generic drug manufacturers and diagnostic networks, and international donor programs fund laboratory strengthening for infectious disease surveillance across Africa, although import dependence and budget limits constrain some markets. Regional distributors play a major role in importing, installing and servicing instruments for hospitals and universities.
Market Dynamics
Growth Drivers: Pharmaceutical R&D, Diagnostic Testing Volumes and Automation
Pharmaceutical and biotechnology research is a main driver. Biologics, cell and gene therapy and contract research all require analytical and sample preparation equipment, and companies replace older instruments to meet regulatory expectations. Contract research and manufacturing organizations further increase equipment needs as drug developers outsource analytical work, and stricter regulatory expectations for impurity and stability testing raise the number of analyses each laboratory must run. Contract research and manufacturing organizations further increase equipment needs as drug developers outsource testing. Companies replace older instruments to meet changing regulatory expectations.
Rising diagnostic testing volumes and automation add demand. Aging populations and chronic disease increase testing, while labor shortages push laboratories to adopt automated and connected systems that raise throughput. Public investment in pandemic preparedness and national diagnostic networks has also left laboratories with greater testing capacity that must be maintained and upgraded, supporting steady replacement demand for analyzers, centrifuges and sample preparation devices over the forecast period. Public investment in pandemic preparedness and national diagnostic networks has also left laboratories with larger instrument fleets to maintain and upgrade.
Restraints: High Equipment Cost, Research Funding Cycles and Skills Gaps
High equipment cost restrains adoption, especially among small laboratories and in developing regions. Advanced instruments require service contracts and consumables that add to ownership costs. Beyond the purchase price, customers must budget for installation, validation, training, consumables and annual service agreements, and these recurring charges can exceed expectations for smaller facilities, prompting them to delay upgrades or buy refurbished units. Beyond the purchase price, customers must budget for installation, validation, training, consumables and annual service contracts, which can add materially to ownership cost over the instrument life.
Research funding cycles and skills gaps also limit growth. Grant uncertainty delays purchases at academic institutions, and a shortage of trained technicians slows installation and use of complex systems. Uncertainty over research funding, particularly in academic markets, creates uneven demand across fiscal years, and the integration of instruments with legacy data systems often requires specialist support, which lengthens deployment times and can discourage the adoption of newer platforms. Uncertainty over research funding, particularly in academic markets, creates uneven demand across fiscal periods.
Opportunities: Laboratory Automation, Emerging Markets and Online Sales
Laboratory automation offers a major opportunity as vendors sell integrated workflows, robotics and software rather than stand-alone instruments, creating recurring service and software revenue. Software, data analytics and remote monitoring services can be sold on subscription terms, and artificial intelligence tools that interpret chromatograms, images and spectra can improve laboratory productivity and give vendors differentiated offerings that are harder to replicate. Software, data analytics and remote monitoring services can be sold on subscription terms, and artificial intelligence tools that help interpret results add further value to instrument platforms.
Emerging markets and online channels add potential. Healthcare and research investment in Asia, Latin America and the Middle East expands the customer base, and online platforms reach smaller buyers at lower cost. Refurbished and leased equipment programs, together with application-specific benchtop systems priced for smaller laboratories, allow manufacturers to reach customers who previously could not afford advanced technology, and these channels also strengthen long-term relationships through consumables sales. Refurbished and leased equipment programs, together with application-specific benchtop systems priced for smaller users, can open new buyer groups in emerging economies.
Recent Developments:
- In June 2025, Thermo Fisher Scientific unveiled the Orbitrap Astral Zoom and Orbitrap Excedion Pro mass spectrometers at ASMS 2025, with the Astral Zoom offering about 35% faster scan speeds and 40% higher throughput. The launches target life sciences discovery and biopharma characterization workflows.
- In March 2025, Shimadzu debuted multiple new analytical products at Pittcon 2025. The introductions broaden its chromatography and spectroscopy portfolio for laboratory customers.
- In January 2025, Waters launched TGA Smart-Seal Pans for benchtop analysis of atmosphere-sensitive materials. The consumable extends its thermal analysis offering to samples that react with air.
- In February 2024, Bruker launched the BEAM FT-NIR spectrometer for in-process solid-sample control. The system supports quality control directly in manufacturing environments.
Laboratory Equipment Market Key Players are:
- Thermo Fisher Scientific Inc.
- Agilent Technologies, Inc.
- Bruker Corporation
- Danaher Corporation
- Revvity, Inc.
- Waters Corporation
- Shimadzu Corporation
- Mettler-Toledo International Inc.
- Sartorius AG
- Eppendorf SE
- Becton, Dickinson and Company
- Merck KGaA
- Hitachi High-Tech Corporation
- JEOL Ltd.
- Bio-Rad Laboratories, Inc.
- Avantor, Inc.
- Tecan Group Ltd.
- Hamilton Company
- PHC Holdings Corporation
- Metrohm AG
Laboratory Equipment Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 23.35 Billion |
| Market Size by 2035 | USD 42.21 Billion |
| CAGR | CAGR of 6.10% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Equipment Type (Analytical Instruments, Laboratory Instruments, and Other Equipment) • By Automation Level (Manual, Semi-Automatic, and Automatic) • By End Use (Pharmaceutical and Biotechnology, Clinical and Diagnostic, Academic and Research, Food and Beverage, Chemical and Materials, and Others) • By Distribution Channel (Offline and Online) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Thermo Fisher Scientific Inc.; Agilent Technologies, Inc.; Bruker Corporation; Danaher Corporation; Revvity, Inc.; Waters Corporation; Shimadzu Corporation; Mettler-Toledo International Inc.; Sartorius AG; Eppendorf SE; Becton, Dickinson and Company; Merck KGaA; Hitachi High-Tech Corporation; JEOL Ltd.; Bio-Rad Laboratories, Inc.; Avantor, Inc.; Tecan Group Ltd.; Hamilton Company; PHC Holdings Corporation; Metrohm AG |

Frequently Asked Questions
Key players include Thermo Fisher Scientific, Agilent Technologies, Bruker, Danaher, Revvity, Waters, Shimadzu, Mettler-Toledo, Sartorius and Eppendorf.
Key opportunities include laboratory automation, integrated software and service offerings, expansion in emerging markets and growth of online sales.
The major growth factor is rising pharmaceutical and biotechnology research and diagnostic testing, combined with demand for automated, high-throughput systems.
By Equipment Type, the Analytical Instruments segment dominated the market in 2025, supported by its role in drug development, quality control and regulated testing.
North America dominated the market with a share of 33.60% in 2025, driven by large research budgets and a strong pharmaceutical and instrument manufacturing base.
