
Large Molecule Bioanalytical Testing Services Market Report Scope & Overview:
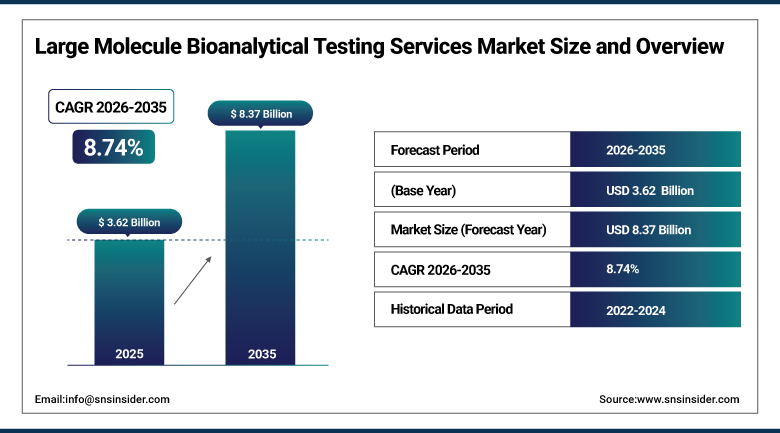
The Large Molecule Bioanalytical Testing Services Market was valued at USD 3.62 Billion in 2025 and is expected to reach USD 8.37 Billion by 2035, growing at a CAGR of 8.74% from 2026-2035.
Large molecule bioanalytical testing services market covers laboratory services that measure biologic drugs such as monoclonal antibodies, proteins, vaccines and cell and gene therapies in blood and tissue, and that test how the body responds to them. Services include pharmacokinetics, immunogenicity, neutralizing antibody and biomarker assays run under good laboratory and clinical practice. Growth is supported by a rising biologics pipeline, outsourcing by drug developers and tighter regulatory guidance, while assay complexity and capacity limits shape the market.
⮞In January, 2026, Frontage Laboratories, a U.S.-based contract research and development organization with 26 sites worldwide, announced that its subsidiary Frontage Europe had moved its bioanalytical laboratory to a 2,500 square meter facility near Milan, Italy. The site offers ligand-binding and mass spectrometry assays, pharmacokinetics support and central laboratory services under ICH M10 guidance.
To Get more information Large Molecule Bioanalytical Testing Services Market - Request Free Sample Report
Large Molecule Bioanalytical Testing Services Market Trends
- Growth of biologics, antibody-drug conjugates and bispecific antibodies needing complex assays
- Outsourcing of bioanalysis by biotechnology firms without in-house laboratories
- Adoption of ICH M10 guidance for bioanalytical method validation
- Hybrid ligand binding and mass spectrometry approaches for proteins and peptides
- Rising demand for immunogenicity and neutralizing antibody testing
- Expansion of cell and gene therapy testing capacity
U.S. Large Molecule Bioanalytical Testing Services Market Outlook
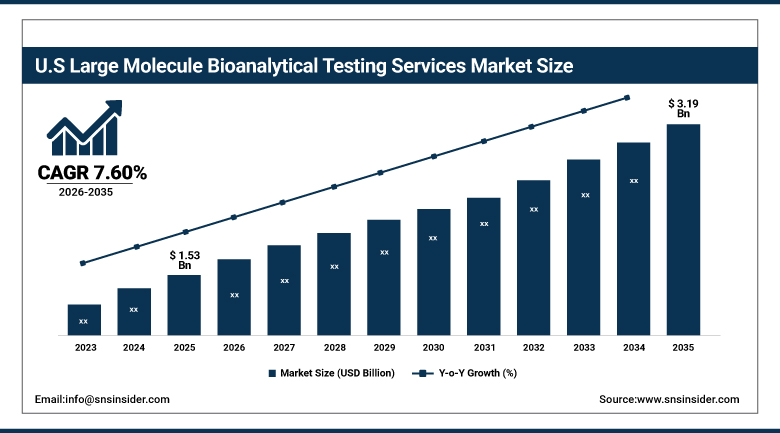
The U.S. Large Molecule Bioanalytical Testing Services Market was valued at USD 1.53 Billion in 2025 and is expected to reach USD 3.19 Billion by 2035, growing at a CAGR of 7.60% from 2026-2035.
The U.S. Large Molecule Bioanalytical Testing Services Market is the largest national market, supported by the world's largest biologics pipeline, a large biotechnology sector that outsources laboratory work and the regulatory expectations of the Food and Drug Administration. Contract laboratories invest in ligand binding, mass spectrometry and cell-based platforms. Growth is moderated by laboratory capacity limits, skilled staff shortages and price competition among providers.
⮞In August 29, 2025, Eurofins Viracor BioPharma announced that it would relocate to a new 96,000 square foot custom-built facility in Lenexa, Kansas, due for completion in September 2025. The site supports sequencing, cell-based assays, flow cytometry, immunogenicity and neutralizing antibody testing, and biomarker analysis under GLP and GCLP.
Large Molecule Bioanalytical Testing Services Market Segment Analysis
- By Molecule Type, monoclonal antibodies segment dominated the Large Molecule Bioanalytical Testing Services Market in 2025 with an estimated 43.00% share; cell and gene therapy products segment is the fastest-growing segment, with an estimated CAGR of 15.50% during 2026–2035.
- By Test Type, pharmacokinetics segment dominated the Large Molecule Bioanalytical Testing Services Market in 2025 with an estimated 45.00% share; cell-based assays segment is the fastest-growing segment, with an estimated CAGR of 11.00% during 2026–2035.
- By Technology, ligand binding assays segment dominated the Large Molecule Bioanalytical Testing Services Market in 2025 with an estimated 52.00% share; liquid chromatography-mass spectrometry segment is the fastest-growing segment, with an estimated CAGR of 11.80% during 2026–2035.
- By End User, pharmaceutical companies segment dominated the Large Molecule Bioanalytical Testing Services Market in 2025 with an estimated 48.00% share; biotechnology companies segment is the fastest-growing segment, with an estimated CAGR of 10.40% during 2026–2035.
By Molecule Type, Monoclonal Antibodies Dominates Large Molecule Bioanalytical Testing Services Market; Cell and Gene Therapy Products to Register Fastest Growth.
Monoclonal antibodies dominate the Large Molecule Bioanalytical Testing Services Market because they are the largest class of biologic medicines and the biggest group of products in development for cancer, immune disease and other conditions. Each program requires pharmacokinetic, immunogenicity and biomarker assays across preclinical and clinical phases. Biosimilar programs add further testing to prove similarity. Antibody-drug conjugates and bispecific antibodies add further complexity, since several analytes such as total antibody, conjugated drug and free payload must be measured. This raises the number of assays per program and the value of each study.
Cell and gene therapy products are projected to register the fastest growth as more candidates enter clinical trials and need specialized assays for vector shedding, expression, persistence and immune response. Their testing is complex, and few laboratories have the skills and capacity, which supports pricing. Developers outsource much of this work to specialist contract laboratories. Regulators expect detailed immunogenicity strategies for these products, and long follow-up in chronic therapies means samples are analyzed over years. Providers with validated, repeatable methods hold an advantage when sponsors select partners.
By Test Type, Pharmacokinetics Dominates Large Molecule Bioanalytical Testing Services Market; Cell-Based Assays to Register Fastest Growth.
Pharmacokinetics dominates the Large Molecule Bioanalytical Testing Services Market because measuring how much drug is present over time is required for almost every biologic study. Sponsors need concentration data to set doses, show exposure and support filings. Studies generate large numbers of samples, and assays must be validated and run under strict regulatory standards. Pharmacokinetic work also supports dose selection in pediatric trials, drug interaction studies and biosimilar comparisons, spreading demand across the development cycle. Contract laboratories often win long-term agreements based on turnaround and data quality.
Cell-based assays are projected to register the fastest growth as neutralizing antibody and potency testing demand functional readouts that reflect how a drug works in cells. Complex modalities such as bispecific antibodies and cell therapies depend on these assays. Laboratories are investing in automation and flow cytometry to scale this work while maintaining quality. Sponsors increasingly request neutralizing antibody assays early in development, since these results influence regulatory discussions. Providers that can offer flow cytometry, reporter gene and binding assays under one roof can win broader contracts.
By Technology, Ligand Binding Assays Dominates Large Molecule Bioanalytical Testing Services Market; Liquid Chromatography-Mass Spectrometry to Register Fastest Growth.
Ligand binding assays dominate the Large Molecule Bioanalytical Testing Services Market because they offer high sensitivity for antibodies and proteins and can be run in plates at large scale. Platforms such as ELISA, electrochemiluminescence and single-molecule arrays are widely validated. Regulators and sponsors are familiar with them, and they suit the high sample counts of clinical trials. Automation and multiplexing, such as running several analytes in one well, lift productivity and lower cost per sample. Laboratories with extensive reagent libraries and experienced scientists can develop assays faster than newer entrants.
Liquid chromatography-mass spectrometry is projected to register the fastest growth as it provides specificity for proteins, peptides and drug conjugates, and is less affected by interfering antibodies. Hybrid methods combine immunocapture with mass spectrometry for better selectivity. Growth in antibody-drug conjugates and oligonucleotide-protein hybrids is increasing use of this technology. Advances in high-resolution instruments and improved digestion and capture methods are expanding the range of proteins that can be measured. Regulators have shown growing acceptance of these methods when properly validated.
By End User, Pharmaceutical Companies Dominates Large Molecule Bioanalytical Testing Services Market; Biotechnology Companies to Register Fastest Growth.
Pharmaceutical companies dominate the Large Molecule Bioanalytical Testing Services Market because they run the largest number of clinical programs and have the budgets to outsource steady volumes of testing. Many use preferred provider agreements with a few contract laboratories. They also fund late-stage studies that generate the largest sample sets. Large sponsors also negotiate bundled agreements covering bioanalysis, biomarker and central laboratory services, which rewards providers with global networks. Quality audits and data integrity records are central to winning and keeping this business.
Biotechnology companies are projected to register the fastest growth as venture-backed firms advance more biologic candidates without building their own laboratories. They rely on contract laboratories for assay development, validation and sample analysis, and they value flexible, fast-moving partners. Funding cycles affect the pace, but the number of early-stage programs remains high. Contract laboratories can help biotech companies conserve cash by sharing instruments and expertise, and many also offer consulting on regulatory strategy. As funding conditions improve, small firms are expected to place new studies.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
92.00 |
|
Europe |
Germany |
24.00 |
|
Asia Pacific |
China |
40.00 |
|
Latin America |
Brazil |
45.00 |
|
Middle East & Africa |
Saudi Arabia |
28.00 |
North America Large Molecule Bioanalytical Testing Services Market Insights
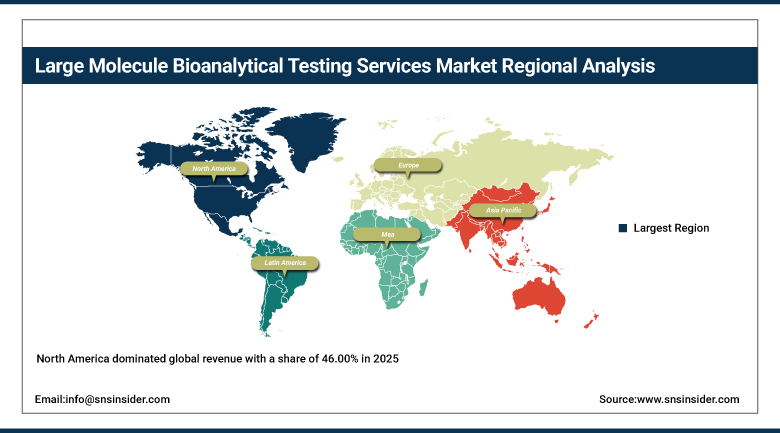
North America dominated global revenue with a share of 46.00% in 2025. The United States accounts for about 92.00% of regional demand, with Canada adding volume. Charles River Laboratories, Labcorp, Eurofins, BioAgilytix, Frontage Laboratories, Thermo Fisher Scientific, Syneos Health and Altasciences serve sponsors in the region. Regulatory guidance from the Food and Drug Administration on immunogenicity and method validation sets expectations that providers worldwide follow. Many laboratories maintain dedicated clinical bioanalytical sites in several states to serve local sponsors quickly.
The concentration of pharmaceutical and biotechnology companies, the largest biologics pipeline and a deep network of contract laboratories support leadership. Providers are adding capacity for immunogenicity, cell-based and cell and gene therapy testing. Capacity limits, skilled staff shortages and price pressure from large sponsors moderate growth, though outsourcing is expected to keep rising. Academic medical centers, biotechnology clusters in Boston, San Francisco and San Diego, and research parks support collaboration. Consolidation among contract providers continues, with acquisitions adding capacity and specialized capabilities.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Large Molecule Bioanalytical Testing Services Market Insights
Germany, the United Kingdom, France, Switzerland and Italy lead regional demand. Eurofins, SGS, Frontage Europe, Charles River, Labcorp, Intertek and Solvias serve biologics developers in the region. Switzerland, Germany and the United Kingdom host large biopharmaceutical companies that outsource bioanalysis. Regional centers of excellence provide expertise in vaccines, cell therapy and advanced analytics. Contract organizations in Belgium, the Netherlands and Spain also support late-phase trials, and shared biobanks make sample logistics easier.
A strong biotechnology base, biosimilar development and active regulators support demand for bioanalysis. Sponsors from other regions also use European laboratories to support trials and filings in the region. Differences in national regulations, high labor costs and competition from lower-cost sites in Asia moderate growth, though quality reputation helps retain work. Adoption of ICH M10 across the region has aligned method validation requirements, easing work across borders. The European Medicines Agency continues to emphasize data integrity, which favors well-established providers. Public funding for biotechnology start-ups across the region also adds new early-stage programs that need assays.
⮞In January, 2026 relocation of Frontage Europe's laboratory to Nerviano, near Milan, is described in the Overview. No further verified, dated company instance was found for Europe.
Asia Pacific Large Molecule Bioanalytical Testing Services Market Insights
Asia Pacific is projected to be the fastest-growing region, at a CAGR of 11.40% during 2026-2035. China leads regional demand, followed by India, Japan, South Korea, Singapore and Australia. WuXi AppTec, WuXi Biologics, Pharmaron, QPS, Labcorp and BioAgilytix's Australian laboratory are among the providers. Japan and South Korea have strong biologics and biosimilar sectors, and Australia is a popular location for early clinical trials thanks to favorable tax incentives. India and Singapore are building contract research capacity. Investment by multinational sponsors in regional laboratories further raises local quality standards over time.
Rapid growth of local biologics developers, clinical trials run in the region and lower operating costs attract outsourcing. Governments support biotechnology clusters, and more companies seek global regulatory acceptance of regional data. Geopolitical concerns about data and biosecurity, differing regulation and quality perception moderate growth for some sponsors. Local contract organizations are investing in ligand binding and mass spectrometry platforms and seeking accreditation to attract global sponsors. Competition on price is strong, and quality credentials help differentiate leading providers. Rising government funding for biosimilars, vaccines and cell therapy in several countries adds to the flow of new programs.
MEA & Latin America Large Molecule Bioanalytical Testing Services Market Insights
In Latin America, Brazil leads, followed by Mexico, Argentina, Colombia and Chile, with regional demand growing at about 8.80% annually. Local biosimilar and vaccine programs, along with growing clinical trial activity, drive demand for bioanalytical services. Limited local capacity means many samples are sent to laboratories in North America. Biosimilar manufacturers in Brazil, Argentina and Mexico need comparability data, and regulators are aligning with international guidance. Sponsors often choose partners with established laboratories in North America for complex assays. Clinical trial sites in these countries are increasingly part of global studies, which will gradually raise the volume of samples analyzed nearby.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, South Africa and Egypt lead demand. National biotechnology and clinical research programs in the Gulf are building laboratory capacity, while funding and talent gaps restrain growth in much of Africa. Gulf countries are investing in genomic and biotechnology centers as part of long-term diversification plans, and hospitals are joining multinational trials. Building skilled laboratory teams remains the main challenge for the region.
Market Dynamics
Growth Drivers: Biologics Pipeline, Outsourcing and Regulatory Guidance
The number of biologic drugs in development is rising, and each requires pharmacokinetic and immunogenicity testing across many studies. Approvals of novel antibodies and cell therapies continue at a steady pace, which expands the number of products entering post-approval studies. Faster approvals and orphan drug incentives also encourage developers to launch more programs in rare conditions with small patient groups, each needing tailored assays for exposure and immune response.
Biotechnology firms outsource laboratory work, and harmonized guidance such as ICH M10 pushes sponsors toward experienced providers. Greater use of biomarkers in trials also creates additional demand for assays that run alongside pharmacokinetic work. Rising investment by large pharmaceutical companies in biologics through partnerships and acquisitions maintains a healthy flow of studies for contract laboratories to support.
Restraints: Assay Complexity, Capacity Limits and Talent Shortages
Large molecule assays take time to develop and validate, and reagents such as critical antibodies can be scarce. Delays in reagent supply or reference standards can hold up assay validation and extend study timelines. Variability between laboratories in assay performance can require repeat testing or bridging studies, adding cost and delays for sponsors and discouraging some from switching providers.
Skilled scientists are in short supply, and laboratories face queues when demand rises quickly. Price pressure from large sponsors also limits margins for providers with high fixed costs. Cybersecurity and data protection rules also add compliance costs for laboratories handling trial data across borders, especially for providers working with sponsors in several regions.
Opportunities: Cell and Gene Therapy, Hybrid Platforms and Emerging Regions
Cell and gene therapy and bispecific antibody programs need specialized assays that command higher prices. Digital laboratory systems and data analytics can shorten turnaround and improve quality. Expanding access to standardized reagents, kits and reference materials can lower assay development time and attract new entrants, widening the pool of capacity for small developers.
Hybrid methods, automation and new laboratories in Asia Pacific and the Middle East provide room for new capacity and partnerships. Long-term partnerships with sponsors provide revenue visibility and justify capacity expansion. Regional centers of excellence and training programs for scientists can also help close the talent gap, supporting growth in markets where capacity is limited today.
Recent Developments:
- In January 2026, Frontage Laboratories moved its Frontage Europe bioanalytical laboratory to a 2,500 square meter facility near Milan, Italy.
- In August 2025, Eurofins Viracor BioPharma announced relocation to a new 96,000 square foot facility in Lenexa, Kansas.
Large Molecule Bioanalytical Testing Services Market Key Players are:
- Charles River Laboratories International, Inc.
- Laboratory Corporation of America Holdings (Labcorp)
- Thermo Fisher Scientific Inc.
- Eurofins Scientific SE
- SGS SA
- WuXi AppTec Co., Ltd.
- ICON plc
- Syneos Health, Inc.
- Pace Analytical Services LLC
- Frontage Laboratories, Inc.
- Medpace Holdings, Inc.
- Intertek Group plc
- BioAgilytix Labs
- Altasciences
- QPS Holdings, LLC
- IQVIA Holdings Inc.
- Catalent, Inc.
- Solvias AG
- Pharmaron Beijing Co., Ltd.
- Coriolis Pharma
Large Molecule Bioanalytical Testing Services Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.62 Billion |
| Market Size by 2035 | USD 8.37 Billion |
| CAGR | CAGR of 8.74% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Molecule Type (Monoclonal Antibodies, Proteins and Peptides, Vaccines, and Cell and Gene Therapy Products) • By Test Type (Pharmacokinetics, Immunogenicity, Cell-Based Assays, and Others) • By Technology (Ligand Binding Assays, Liquid Chromatography-Mass Spectrometry, Cell-Based Assays, and PCR) • By End User (Pharmaceutical Companies, Biotechnology Companies, and Contract Research Organizations) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Charles River Laboratories International, Inc., Laboratory Corporation of America Holdings (Labcorp), Thermo Fisher Scientific Inc., Eurofins Scientific SE, SGS SA, WuXi AppTec Co., Ltd., ICON plc, Syneos Health, Inc., Pace Analytical Services LLC, Frontage Laboratories, Inc., Medpace Holdings, Inc., Intertek Group plc, BioAgilytix Labs, Altasciences, QPS Holdings, LLC, IQVIA Holdings Inc., Catalent, Inc., Solvias AG, Pharmaron Beijing Co., Ltd., Coriolis Pharma |

Frequently Asked Questions
Key players include Charles River Laboratories International, Inc., Laboratory Corporation of America Holdings (Labcorp), Thermo Fisher Scientific Inc., Eurofins Scientific SE, SGS SA, WuXi AppTec Co., Ltd., ICON plc and Frontage Laboratories, Inc.
Key opportunities include specialized testing for cell and gene therapy and bispecific antibodies, hybrid ligand binding and mass spectrometry platforms, and new capacity in Asia Pacific and the Middle East.
The major growth factor is the expanding pipeline of biologic drugs together with outsourcing of laboratory work by drug developers.
By Molecule Type, the Monoclonal Antibodies segment dominated the market in 2025 with an estimated 43.00% share, supported by the large pipeline of antibody drugs and biosimilars.
North America dominated the market with a share of 46.00% in 2025, driven by the concentration of drug developers, the largest biologics pipeline and a deep network of contract laboratories.
