
Mammography Workstations Market Report Scope & Overview:
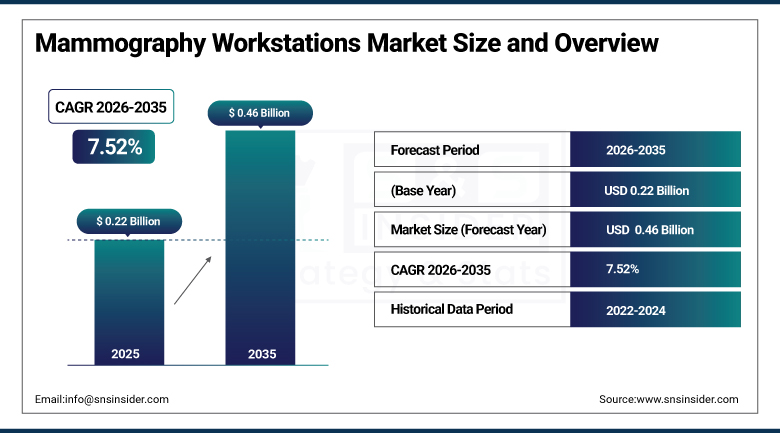
The Mammography Workstations Market was valued at USD 0.22 Billion in 2025 and is expected to reach USD 0.46 Billion by 2035, growing at a CAGR of 7.52% from 2026-2035.
The Mammography Workstations Market growth is mainly fueled by the increasing incidence of breast cancer all over the world, the increasing awareness about early detection, and key technology advancements such as digital tomosynthesis and artificial intelligence-enabled software. A mammography workstation is a specialized medical imaging system created for helping radiologists analyze and interpret images of the breast. In view of the increasing volume of imaging and keeping in mind the importance of patient outcomes, the aim of radiology departments is to adopt a solution that simplifies their workflow. In view of the increasing focus on early detection and digitization, the mammography workstation is becoming an intelligent diagnostic station facilitating personalized treatment, collaboration, and scalable adoption.
In May 2025, Hologic revealed that MedTech Breakthrough had chosen the company's Genius AI Detection PRO software platform as "Best New Imaging Technology Solution," at their annual award ceremony which honors innovation in the wider field of medical technology. This is yet another validation from the industry of the role of artificial intelligence in making a diagnostic tool in the field of mammography workstations, and highlights the increasing importance of advanced AI detection algorithms for radiology departments as they consider diagnostic accuracy and efficiency when selecting mammography workstation technologies.
To Get more information On Mammography Workstations Market - Request Free Sample Report
Mammography Workstations Market Trends
- Rising integration of AI-powered computer-aided detection tools improving diagnostic accuracy and radiologist workflow efficiency.
- Growing adoption of multimodal workstations supporting integrated review of mammography, ultrasound, and MRI data.
- Expanding clinical use of contrast-enhanced mammography and digital breast tomosynthesis requiring advanced workstation capability.
- Increasing demand for standalone, cost-efficient workstation solutions among small and mid-sized imaging centers.
- Rising government support for breast cancer screening programs expanding workstation adoption across emerging regions.
- Growing integration of remote collaboration capability enabling distributed radiology review across healthcare networks.
U.S. Mammography Workstations Market Outlook
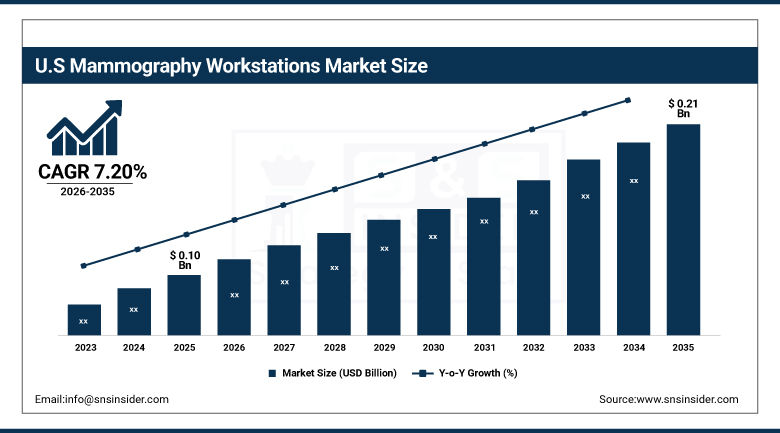
The U.S. Mammography Workstations Market was valued at USD 0.10 Billion in 2025 and is expected to reach USD 0.21 Billion by 2035, growing at a CAGR of 7.20% from 2026-2035.
The U.S. Mammography Workstations Market growth continues to be reinforced by the rising incidence of breast cancer and growing awareness about the importance of early detection, which continue to be major contributors to increased adoption of advanced diagnostic technologies across the domestic healthcare system. The United States leads North American market, anchored by substantial hospital and outpatient imaging infrastructure increasingly investing in workstation systems to support multi-modal breast imaging review. Rising adoption of advanced mammography workstations supporting digital mammography, 3D tomosynthesis, and AI-assisted image analysis continues to reflect domestic healthcare providers' expanded screening program emphasis and prioritization of timely diagnosis. Growth is supported by domestic investment in workstation technology extending high-quality breast imaging access to remote and underserved communities.
In March 2024, iCAD, Inc. revealed new and improved ProFound Detection workstation features, with the enhanced capability for both 2D and 3D mammography helping radiologists interpret mammograms more easily and effectively at their workstation. The feature enhancement illustrates how established domestic mammography workstation and AI detection software vendors continue to invest in incremental diagnostic capability improvements, reinforcing the competitive importance of continuous product refinement as domestic radiology departments increasingly prioritize both diagnostic accuracy and workflow efficiency when evaluating workstation technology investments.
Mammography Workstations Market Segment Analysis
- By Modality Type, the Multimodal segment dominated the Mammography Workstations Market with approximately 53.60% share in 2025, while the Standalone segment is the fastest growing with a CAGR of approximately 8.20%.
- By Application, the Diagnosis & Screening segment dominated the Mammography Workstations Market with approximately 38.60% share in 2025, while the Advanced Imaging segment is the fastest growing with a CAGR of approximately 8.40%.
- By End-User, the Hospitals segment dominated the Mammography Workstations Market with approximately 46.60% share in 2025, while the Clinics segment is the fastest growing with a CAGR of approximately 7.60%.
By Modality Type, Multimodal Dominates the Mammography Workstations Market and Standalone Grows Fastest
Multimodal workstations have become prevalent in the market owing to an increasing need for integrated imaging environment, enabling radiologists to examine images from mammography, ultrasound, and MRI studies in one workstation, hence improving confidence during diagnosis and conducting a full assessment of the breast in difficult cases. The use of such workstations simplifies the workflow and increases the rate at which they are adopted, bringing with it benefits such as better patient care and improved performance of radiology, making multimodal workstations maintain their dominance as the most dominant modality type category.
Standalone workstations are the fastest-growing modality type as rising demand among small and mid-sized imaging centers seeking cost-efficient, easy-to-install workstation solutions continues to expand this segment's adoption. These systems allow for easy deployment without the need for complicated integration processes, thus making them more efficient and flexible solutions that can be implemented quickly, particularly in situations where resources are limited, thus making them a good alternative for imaging service providers who want to increase their breast imaging capacity.
By Application, Diagnosis & Screening Dominates the Mammography Workstations Market and Advanced Imaging Grows Fastest
The diagnosis and screening applications continue to hold the dominant share of the market owing to increased use of breast cancer screening programs on an international scale by healthcare providers to improve access to breast cancer screening and ensure accurate diagnoses within both the mature and emerging healthcare markets. The volume of breast cancer screenings being done along with the increasing governmental support for breast cancer screening programs helps maintain the dominance of these applications.
Advanced imaging applications are the fastest-growing application category as increasing clinical adoption of high-resolution modalities, including contrast-enhanced mammography and digital breast tomosynthesis, continues to require sophisticated workstations capable of handling complex datasets. These techniques drive demand for systems supporting deeper visualization and improved lesion characterization, positioning advanced imaging as an increasingly important application category as radiology departments pursue enhanced diagnostic capability beyond routine screening.
By End-User, Hospitals Dominates the Mammography Workstations Market and Clinics Grows Fastest
Hospitals have been leading the market due to the increasing trend of centralization of breast imaging centers with state-of-the-art diagnostic facilities, owing to the increasing investments of hospitals in workstation systems to conduct multi-modal breast imaging reviews within cancer care programs. The size and sophistication of the breast imaging programs of hospitals, along with the existing relationship between hospitals and workstation suppliers, continue to keep hospitals at the top of the end-user list for mammography workstations.
Clinics are the fastest-growing end-user category as growing demand for accessible and specialized breast imaging services in community and outpatient settings continues to expand workstation adoption beyond traditional hospital-based programs. Clinics are increasingly adopting advanced mammography workstations to offer high-quality, efficient diagnostic services closer to patients, positioning clinics as an increasingly important care setting as healthcare systems prioritize early detection and digital transformation extending breast imaging access to more remote and underserved communities.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.60% |
|
Europe |
Germany |
29.60% |
|
Asia Pacific |
China |
39.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
North America Mammography Workstations Market Insights
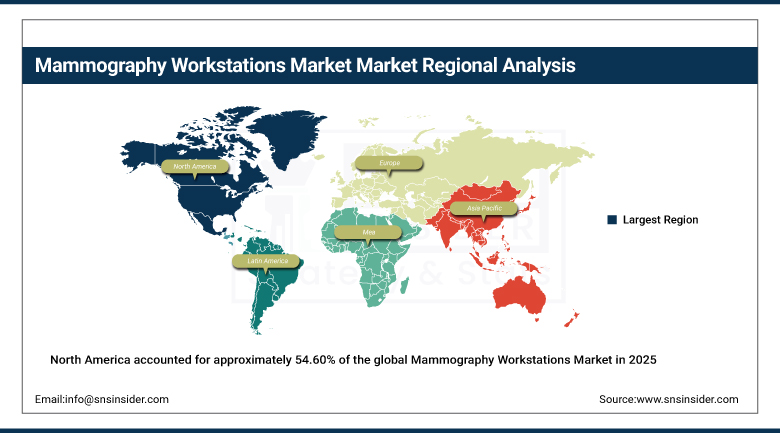
North America accounted for approximately 54.60% of the global Mammography Workstations Market in 2025, making it the largest regional market, driven by high awareness of breast cancer screening and substantial healthcare infrastructure investment across the region. The United States dominates regional demand, anchored by a mature hospital and outpatient imaging infrastructure with established workstation vendor relationships and consistent screening program participation rates.
With Canada adding gradual regional demand for breast imaging due to expansion of its health care infrastructure, the continued domestic investments in AI diagnostic technologies and multimodal workstations will ensure that North America maintains its leadership in the region throughout the forecast period, although at a growth rate that will be lower compared to other emerging markets with developing healthcare infrastructures.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Mammography Workstations Market Insights
Asia Pacific is the fastest-growing regional market, expanding at a CAGR of approximately 8.80% from 2026 to 2035, driven by rising breast cancer incidence, expanding healthcare infrastructure investment, and growing government support for screening programs across China and India. China's large and aging population, combined with expanding healthcare infrastructure investment, continues to drive substantial regional demand for mammography workstation adoption.
India is contributing significant incremental growth as its healthcare infrastructure and breast cancer screening awareness continue to expand, supported by rising government investment in early detection programs. Japan and South Korea contribute additional scale through established healthcare systems increasingly adopting advanced AI-powered workstation technology, reinforcing Asia Pacific's position as the fastest-growing market through the forecast period.
Europe Mammography Workstations Market Insights
Europe represents a significant share of the global Mammography Workstations Market, anchored by Germany's large healthcare infrastructure and established breast cancer screening program participation. European healthcare systems continue to support robust mammography workstation adoption given the region's well-developed public healthcare reimbursement frameworks covering breast cancer screening and diagnostic imaging services.
The United Kingdom, France, and Italy are providing consistent demand for increased use of advanced workstation technologies by regional healthcare systems through their national screening programs. The regional medical device suppliers are focusing on developing intelligent diagnosis solutions and multimodal integration capacity in order to meet the rising demands for improved diagnostic accuracy from the region's breast imaging equipment.
MEA & Latin America Mammography Workstations Market Insights
The Middle East & Africa market remains comparatively small but is expanding as growing healthcare infrastructure investment across the United Arab Emirates and Saudi Arabia sustains demand for advanced breast imaging diagnostic capability. Regional governments continue to invest in expanding specialized breast imaging centers to serve growing domestic demand for early detection services.
Latin America's market is led by Brazil, where a growing awareness of breast cancer screening and expanding healthcare infrastructure continue to drive gradual mammography workstations market growth. Mexico is contributing growth as regional healthcare access continues to expand. Across the region, adoption remains concentrated among larger urban medical centers with established breast imaging programs.
Market Dynamics
Growth Drivers: Rising Breast Cancer Prevalence and AI-Powered Diagnostic Technology
The increase in cases of breast cancer around the globe is the main catalyst for the growth of the Mammography Workstations market, owing to increased awareness about the importance of early detection which is contributing to an increased demand for sophisticated mammography workstations that can support digital mammography, 3D tomosynthesis, and AI-driven image interpretation. As the healthcare industry scales up its screening and diagnostic initiatives, the demand for workstation technology grows accordingly.
Technological advancements constitute a second important growth driver since the adoption of new-age imaging technologies such as 3D tomosynthesis and computer-aided detection software powered by AI is helping to enhance the level of accuracy in diagnosis as well as increase efficiency within the field of radiology. Increased focus on developing healthcare infrastructure and support from the government for screening programs in different countries is contributing to market growth.
Restraints: High Equipment Costs and Integration Complexity
High equipment costs represent a meaningful restraint on market growth, as advanced multimodal workstations incorporating AI-powered diagnostic capability continue to require substantial capital investment that can be particularly burdensome for smaller imaging centers and clinics operating with limited capacity expansion budgets. This cost consideration continues to concentrate the most sophisticated workstation technology adoption among larger, well-capitalized hospital systems and breast care centers.
Integration challenges pose yet another limitation, since the use of multimodal workstations that integrate mammography, ultrasound, and MRI data entails technical integration with current PACS and other IT healthcare systems. The challenge of integration may delay the deployment process as well as increase its costs, especially for those organizations whose imaging infrastructure needs upgrading in order to facilitate the use of advanced workstations.
Opportunities: AI-Powered Detection Innovation and Emerging Market Screening Expansion
Continued innovation in AI-powered computer-aided detection tools represents a substantial opportunity, as vendors that can demonstrate superior diagnostic accuracy and workflow efficiency improvements are positioned to capture premium positioning as radiology departments increasingly prioritize AI-assisted diagnostic capability. Vendors achieving industry recognition for AI detection innovation are increasingly favored by healthcare providers seeking validated, high-performance diagnostic technology.
The continued expansion of breast cancer screening programs across emerging markets offers a further avenue for growth, as government investment in healthcare infrastructure and growing awareness of early detection importance continue to extend mammography workstation demand into previously underserved regions. Vendors that can develop cost-competitive, standalone workstation solutions suited to resource-constrained settings are well positioned to capture demand from emerging market imaging centers seeking to expand breast cancer screening capability.
Recent Developments:
- 2026: Siemens Healthineers received FDA clearance for new contrast-enhanced mammography and biopsy capabilities for MAMMOMAT B.brilliant, including enhanced image reconstruction for dense breast tissue.
- 2026: Barco continued advancing diagnostic display technologies for medical imaging, supporting high-resolution visualization requirements across radiology and breast-imaging environments.
- 2026: Konica Minolta developed healthcare imaging and diagnostic workflow technologies, integrating advanced image processing and informatics capabilities to support efficient breast-imaging operations.
Mammography Workstations Market Key Players are:
- Koninklijke Philips N.V.
- EIZO Corporation
- Sectra AB
- Esaote SpA
- Carestream Health, Inc.
- Siemens Healthineers AG
- Hologic, Inc.
- Barco NV
- Konica Minolta, Inc.
- Agfa-Gevaert Group
- iCAD, Inc.
- GE HealthCare Technologies Inc.
- Fujifilm Holdings Corporation
- Canon Medical Systems Corporation
- Planmed Oy
- IMS Giotto S.p.A.
- Metaltronica S.p.A.
- BK Medical
- Volpara Health Technologies Ltd.
- Carl Zeiss Meditec AG
Mammography Workstations Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 0.22 Billion |
| Market Size by 2035 | USD 0.46 Billion |
| CAGR | CAGR of 7.52% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Modality Type (Multimodal, Standalone) • By Application (Diagnosis & Screening, Clinical Review, Advanced Imaging, Others) • By End-User (Hospitals, Clinics, Diagnostic & Imaging Centers, Specialty Clinics, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Koninklijke Philips N.V., EIZO Corporation, Sectra AB, Esaote SpA, Carestream Health, Inc., Siemens Healthineers AG, Hologic, Inc., Barco NV, Konica Minolta, Inc., Agfa-Gevaert Group, iCAD, Inc., GE HealthCare Technologies Inc., Fujifilm Holdings Corporation, Canon Medical Systems Corporation, Planmed Oy, IMS Giotto S.p.A., Metaltronica S.p.A., BK Medical, Volpara Health Technologies Ltd., Carl Zeiss Meditec AG. |
Frequently Asked Questions
Key players include Koninklijke Philips N.V., Siemens Healthineers AG, Hologic, Inc., GE HealthCare Technologies Inc., iCAD, Inc., Fujifilm Holdings Corporation, and Sectra AB, among other global medical imaging technology providers.
Continued innovation in AI-powered computer-aided detection tools and continued expansion of breast cancer screening programs across emerging markets represent the primary opportunities.
Growth is primarily driven by the rising prevalence of breast cancer worldwide combined with important technological developments including AI-powered diagnostic tools and digital tomosynthesis.
By Modality Type, Multimodal dominated the market with approximately 53.60% share in 2025, reflecting growing demand for integrated review of mammography, ultrasound, and MRI data.
North America dominated the market with approximately 54.60% share in 2025, driven by high awareness of breast cancer screening and substantial healthcare infrastructure investment.
