
Nuclear Robots Market Report Scope & Overview:
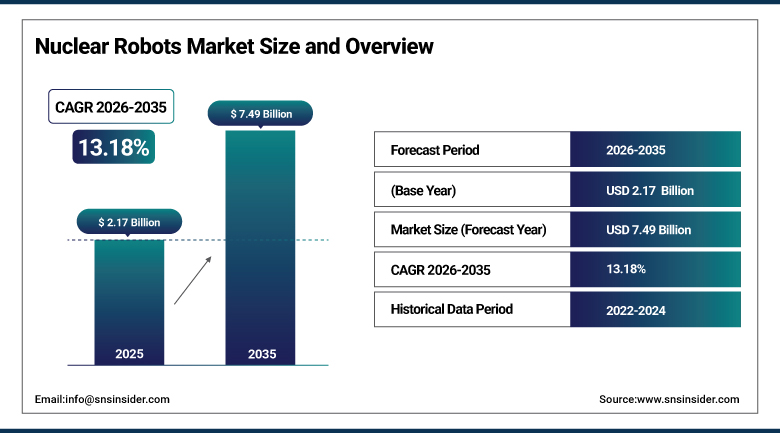
The Nuclear Robots Market size was valued at USD 2.17 Billion in 2025 and is expected to reach USD 7.49 Billion by 2035, growing at a CAGR of 13.18% from 2026-2035.
The Nuclear Robots Market includes remotely operated and autonomous machines that inspect, maintain, repair and dismantle nuclear facilities where radiation makes human work risky. These systems range from heavy manipulators and crawling vehicles to drones, underwater vehicles and humanoid robots. Ageing reactors, life extension programs and a growing backlog of plants to be decommissioned are creating steady demand. Artificial intelligence and better radiation-tolerant electronics are improving autonomy. Qualification costs, long approval cycles and the lack of common interface standards slow adoption. Fusion projects and small modular reactors add new uses for remote handling. Vendors are expanding service networks to support customers across several countries.
⮞In October 2026, the World Nuclear Association reported 443 operable reactors with about 406 GWe of capacity worldwide, and 79 more under construction. A fleet of that size and age creates continuing need for remote inspection and maintenance.
To Get more information Nuclear Robots Market - Request Free Sample Report
Nuclear Robots Market Trends
-
Rising use of autonomous inspection and radiation mapping powered by artificial intelligence
-
Legged, aerial and humanoid robots entering nuclear sites alongside traditional manipulators
-
Large decommissioning programs in Japan, the United Kingdom, the United States and Korea
-
Remote handling systems for fusion research and small modular reactors
-
Radiation-tolerant electronics, sensors and actuators extending robot service life
U.S. Nuclear Robots Market Size Outlook
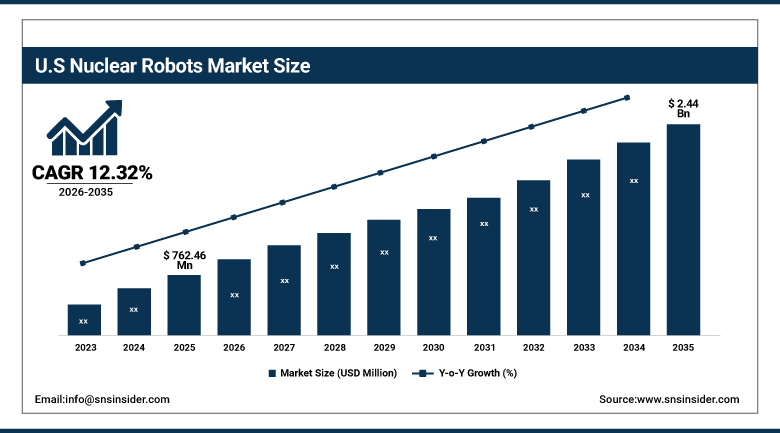
The U.S. Nuclear Robots Market was valued at USD 762.46 Million in 2025 and is expected to reach USD 2.44 Billion by 2035, growing at a CAGR of 12.32% from 2026-2035.
The U.S. Nuclear Robots Market is driven by the largest operating reactor fleet in the world and by the long cleanup of former weapons production sites. The Department of Energy oversees waste retrieval and facility demolition at Hanford, Oak Ridge, Savannah River and other locations. Utilities extend reactor licenses to 80 years, which increases the need for remote inspection of aged components. Interest in advanced and small modular reactors adds further demand for robotic maintenance. National laboratories and universities supply research, while commercial companies build field systems. Procurement rules and safety reviews lengthen sales cycles but support steady budgets. Long project timelines give suppliers visibility into future orders.
⮞In May 2026, the U.S. Department of Energy reported that Hanford had turned more than 100,000 gallons of tank waste into glass since hot commissioning began in October 2025. The tanks hold about 56 million gallons, so remote handling work will continue for years.
Nuclear Robots Market Segment Analysis
-
By Type, the Remote Manipulators segment dominated the Nuclear Robots Market with approximately 31.55% share in 2025, while the Aerial Drones segment is the fastest growing with a CAGR of approximately 15.68%.
-
By Application, the Inspection & Monitoring segment dominated the Nuclear Robots Market with approximately 36.40% share in 2025, while the Decommissioning segment is the fastest growing with a CAGR of approximately 14.93%.
-
By End User, the Nuclear Utilities & Plant Operators segment dominated the Nuclear Robots Market with approximately 42.00% share in 2025, while the Decommissioning & Waste Contractors segment is the fastest growing with a CAGR of approximately 14.68%.
-
By Facility Type, the Nuclear Power Plants segment dominated the Nuclear Robots Market with approximately 54.60% share in 2025, while the Waste Storage & Disposal Sites segment is the fastest growing with a CAGR of approximately 13.58%.
By Type, Remote Manipulators Dominates the Nuclear Robots Market and Aerial Drones Grows Fastest
Remote manipulators lead because most nuclear tasks involve handling, cutting or moving objects behind shielding. Master-slave arms, force-feedback telemanipulators and heavy hydraulic arms are proven in hot cells, gloveboxes and reactor buildings. Operators trust these systems because a skilled person controls every motion. They are also used for sampling, tool changes and size reduction of contaminated parts. Their long record with regulators makes approval easier than for newer designs, and utilities often prefer to extend existing equipment rather than qualify a new platform for each job. Training operators on familiar controls is also simpler than introducing new interfaces.
Aerial drones are the fastest growing type as operators look for quick surveys of large halls, cooling towers and storage areas without sending people in. Drones carry cameras, radiation detectors and laser scanners, and they can reach high structures that scaffolds cannot. Flight in enclosed, radiated spaces needs radiation hardened electronics and careful navigation, so use remains limited to inspection and mapping. As autonomy software and radiation-tolerant payloads improve, adoption is expected to widen across plants and cleanup sites. Vendors are also testing tethered drones that can recharge and relay data safely.
⮞In October 2025, Mitsubishi Heavy Industries said its underwater ultrasonic vessel inspection robot, which scans at 200 mm per second, has been used about 50 times at Japanese pressurized water reactors. The record shows the maturity of purpose-built inspection robots.
By Application, Inspection & Monitoring Dominates the Nuclear Robots Market and Decommissioning Grows Fastest
Inspection and monitoring leads because operating plants must check welds, vessels, pipes, tanks and floors on a fixed schedule, and many locations are dangerous for people. Robots with ultrasonic probes, cameras and radiation sensors collect data without lengthy shutdown work. Condition data from repeated surveys helps operators plan repairs and extend asset life. Regulators accept robotic inspection when results are traceable, which supports wider use. Digital records also let engineers compare results across outages. Each outage season generates a fresh set of inspection tasks for crawlers, swimmers and arms.
Decommissioning is the fastest growing application as a large group of early reactors reaches the end of its life. Dismantling needs remote cutting, debris retrieval, decontamination and waste sorting, all in areas with high radiation. Governments have set long cleanup programs with large budgets, and contractors are adopting robots to cut worker dose and speed up work. Projects at sites such as Fukushima Daiichi, Sellafield and Hanford act as test beds, and lessons from them feed into products for plants that will close later. Cost savings from reduced scaffolding and shielding also help the case.
⮞In October 2026, the World Nuclear Association reported that more than 220 power, experimental and prototype reactors have been retired worldwide, and that about 25 have been fully dismantled. The gap points to a long decommissioning pipeline.
By End User, Nuclear Utilities & Plant Operators Dominates the Nuclear Robots Market and Decommissioning & Waste Contractors Grows Fastest
Utilities and plant operators lead because they own the operating reactors where inspection, maintenance and outage work recur every year. They buy or lease robots for steam generators, reactor vessels, fuel pools and containment areas, and they run long-term service agreements with suppliers. Safety cases and worker dose limits push them toward remote tools. Life extension programs and power uprates add work, while new build projects create future needs. Large operators also invest in internal robotics teams to adapt equipment to plant specifics. Collaboration with suppliers shortens development time.
Decommissioning and waste contractors are the fastest growing end users as governments hand cleanup programs to specialist consortia. These firms need flexible fleets of manipulators, demolition machines, sampling crawlers and automated sorting systems. They also buy from technology startups and universities to speed innovation. Fixed-price and milestone-based contracts reward productivity, so robots that cut labor and exposure win favor. As more plants retire, the contractor base is expected to widen across North America, Europe and Asia. Specialist rental fleets are also emerging to serve short projects.
⮞In February 2026, the Ontario government reported that the four-unit Darlington refurbishment was complete at CAD 12.8 billion, CAD 150 million under budget and four months ahead of schedule. The project adds more than 3,500 MW and extends operation to at least 2055.
By Facility Type, Nuclear Power Plants Dominates the Nuclear Robots Market and Waste Storage & Disposal Sites Grows Fastest
Nuclear power plants lead because they hold the greatest number of high-value assets that need frequent, remote checks and repairs. Reactor vessels, steam generators, piping and spent fuel pools all involve radiation or limited access. Operators use robots during outages to reduce time and dose, and extended licenses mean components stay in service longer. New small modular reactors are being designed with robotic access in mind, which will support future demand. Power plants also have budgets for continuing service, unlike many one-time cleanup projects. Fleet standardization lowers training and spare part cost.
Waste storage and disposal sites are the fastest growing facility type as countries retrieve legacy waste and build repositories. Tanks, silos and storage vaults contain hazardous material in awkward spaces, and robots are the only practical way to survey, sample and move it. Sorting and packaging of waste also benefit from automation. As geological repositories and interim stores open in several countries, they will need remote handling for emplacement and monitoring over decades. Remote handling reduces exposure for staff during long operating periods.
⮞In June 2025, the Nuclear Decommissioning Authority launched a program of up to GBP 9.5 million over four years for its Auto-SAS autonomous waste sorting robot, with the first phase running to August 2027. The funding shows public investment in waste automation.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
87.15 |
|
Europe |
France |
28.51 |
|
Asia Pacific |
China |
37.92 |
|
Latin America |
Brazil |
58.53 |
|
Middle East & Africa |
Saudi Arabia |
30.74 |
North America Nuclear Robots Market Insights
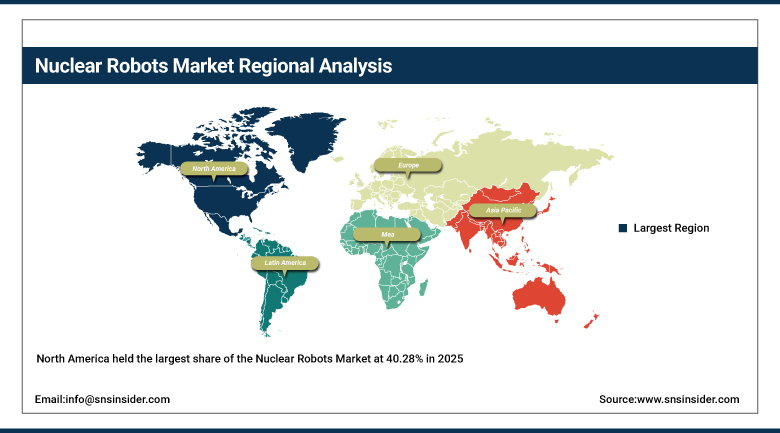
North America held the largest share of the Nuclear Robots Market at 40.28% in 2025, with the United States accounting for most of it. The region has the biggest operating fleet, a long list of weapons-era cleanup sites and strong research capacity at national laboratories. Canada adds demand through the refurbishment of its CANDU reactors, and Mexico operates one power station. Suppliers and integrators in the region work with utilities and federal agencies on tailored systems. Local research bodies also help test prototypes under realistic conditions.
Regulatory and funding choices shape demand. Federal budgets for site cleanup are large and continuing, and license renewals now reach 80 years for many reactors. Canada's utilities run major refurbishment projects that require remote tooling and inspection. Interest in advanced reactors and fusion is creating a new customer group. The long approval cycle for equipment used inside nuclear facilities is a restraint, but it also protects established suppliers with proven records. Insurance and liability rules add to the caution.
⮞In July 2025, the U.S. Nuclear Regulatory Commission issued a subsequent license renewal for a South Carolina reactor to August 2062, bringing the number of units renewed to 80 years to 13. Longer operating lives support steady inspection and maintenance work.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Nuclear Robots Market Insights
Europe holds about 31.75% of the Nuclear Robots Market and is led by France, the United Kingdom, Germany and Russia. France operates a large reactor fleet and fuel cycle plants, while the United Kingdom manages the cleanup of its early reactors and reprocessing facilities. Germany is phasing out power plants and is dismantling them, which creates strong demand for remote cutting and handling. Sweden, Spain and Belgium also use robots for inspection and decommissioning.
National agencies and research programs support the market. The United Kingdom funds robotics trials through its decommissioning authority and its largest cleanup site, and universities work with startups on legged and autonomous platforms. Small modular reactor developers in the region are including robotic inspection in their designs. Public funding supports demonstrations, though procurement is slow. Cross-border projects and common safety guidance help suppliers sell to several countries. Regional supply chains also help keep parts available.
⮞In September 2026, Rolls-Royce SMR reported that finalists from five organizations demonstrated robotic inspection systems during a challenge held on 20 and 21 August 2026. The event shows early interest in robotics for small modular reactor designs.
Asia Pacific Nuclear Robots Market Insights
Asia Pacific is projected to be the fastest growing region, with a CAGR of 15.23% during 2026-2035 and a 22.00% share in 2025. China, Japan, South Korea and India lead. Japan continues the long cleanup of Fukushima Daiichi, South Korea began dismantling its first reactor in 2025, China is building a large number of new plants and India aims to expand its fleet. Each country is also developing its own robotics industry.
Government programs are central to growth. Japan's cleanup requires specialized arms for retrieving fuel debris, and the schedule extends for decades. South Korea's research institutes transfer technology to private companies, and China invests in fusion maintenance systems. New reactors need inspection and maintenance tools from the start. Local suppliers are gaining ground against global firms, though qualification standards remain strict, and exports of robots to nuclear sites face careful review. Language and standards differences also complicate cross-border sales.
⮞In January 2025, the Korea Atomic Energy Research Institute transferred its Armstrong dual-arm disaster response robot, which can lift 200 kg, to the company Victex for commercialization. The deal shows how research results are reaching industry.
MEA & Latin America Nuclear Robots Market Insights
Latin America and the Middle East and Africa together hold about 5.97% of the Nuclear Robots Market. In Latin America, Argentina, Brazil and Mexico operate reactors, and plant life extensions are creating inspection work. Brazil is also completing long-delayed projects and has decommissioning needs for older facilities. Local engineering firms and national nuclear agencies are the main buyers, and many rely on imported robotic tools. Training and local service support are growing needs.
In the Middle East and Africa, the United Arab Emirates operates four large reactors at Barakah, Saudi Arabia is studying a nuclear program, and South Africa runs the Koeberg station with extended licenses. These operators need inspection and maintenance systems, mostly bought from global suppliers. Egypt and Turkey are building new plants, which will create demand for service robots in the next decade. Budget limits and a shortage of trained staff slow adoption.
⮞In January 2026, Nucleoeléctrica Argentina reported 2025 net nuclear generation of 10,760,572 MWh, up from 10,449,015 MWh in 2024, with the Atucha I life extension outage 48% complete. Life extension work of this type creates inspection and maintenance needs.
Market Dynamics
Growth Drivers: Ageing Reactor Fleets and Decommissioning Programs Drive Growth in the Nuclear Robots Market
Ageing reactor fleets and decommissioning programs are the main drivers. Hundreds of reactors are operating beyond their original design life, and regulators approve extensions only with stronger inspection records. Robots can reach areas that people cannot and collect consistent data. At the same time, early reactors are being retired, and dismantling them involves radiation, contamination and heavy structures that favor remote tools. Governments have funded cleanup programs for decades, which provides stable demand for specialist machines. Public agencies also fund research that moves prototypes toward field use.
Technology advances and safety rules strengthen the case. Artificial intelligence improves navigation, defect detection and radiation mapping, and sensors have become smaller and tougher. Worker dose limits and public expectations push operators to replace manual entries with remote work. Governments also see robotics as a way to control cleanup costs over long schedules. New fusion and small modular reactor projects add further demand for remote handling from the design stage. Insurance and licensing bodies increasingly expect documented remote methods.
⮞In July 2025, Asia Business Daily reported that Korea's Kori 1 decommissioning budget is KRW 1.0713 trillion and that the global decommissioning market could reach about KRW 500 trillion by 2045. The figures show the scale of future demand.
Restraints: High Qualification Costs and Slow Retrieval Schedules Restrain Growth in the Nuclear Robots Market
High qualification costs and long approval cycles restrain growth. Equipment used inside nuclear facilities must withstand radiation, pass strict safety reviews and be supported for many years. Testing can take years and cost tens of millions of dollars for new entrants. Utilities are cautious, since a failed tool could stop an outage or block a pathway. These conditions favor established suppliers and make it hard for startups to scale, even when their technology is promising. Procurement teams also prefer vendors that offer long spare part support.
Technical difficulty adds further limits. Radiation damages electronics, seals and actuators, so robots need frequent repair or replacement of parts. Reactor designs differ, and no common interface exists, so tools often need custom work for each site. Complex tasks, such as retrieving melted fuel debris, advance slowly and sometimes slip behind plan. Small markets for each tool keep unit costs high, and customers are sensitive to budget overruns. Maintenance of radiated robots adds recurring cost that buyers must plan for.
⮞In July 2025, Tokyo Electric Power Company said in a draft plan that preparing access points for the Fukushima Daiichi Unit 3 debris retrieval would take about 12 years for side access and about 15 years for top access. The timeline shows how complex nuclear cleanup work remains.
Opportunities: Fusion Maintenance and Humanoid Robots Create Opportunities in the Nuclear Robots Market
Fusion maintenance offers a major opportunity. Experimental fusion devices need remote handling for installing, inspecting and replacing components in vacuum vessels, often with very tight tolerances. Research projects in China, Europe, Japan and the United States are funding large manipulators and precision tools. Success there could lead to commercial plants that need continuing service fleets. Technologies developed for fusion also transfer to fission and decommissioning. Vendors that win early fusion contracts can gain reputation and design knowledge that carry over to fission.
Humanoid and legged robots, along with small modular reactors, offer further openings. Humanoids can use tools built for people and move through stairs and doors, which suits older plants. Trials with legged robots at cleanup sites show their ability to carry sensors across rough ground. Small modular reactors will be built in series, so robots designed for inspection from the start can be repeated across units. Lower cost sensors and better batteries also widen the range of feasible missions. Emerging nuclear nations will also need service robots as new plants begin operating.
⮞In September 2025, the Institute of Plasma Physics at the Chinese Academy of Sciences reported that its fusion maintenance arm built for the CRAFT facility handles a payload of 60 tonnes with placement accuracy of 4 mm. The system shows rising technical ambition in remote handling.
Recent Developments:
-
In January 2025, Brokk deployed a remote-controlled demolition robot fitted with a custom BGS65 grapple saw at Vattenfall's Ågesta plant in Sweden. The company said the tool cut pipes three to six times faster than handheld equipment.
-
In July 2025, AtkinsRéalis reported that its ARGO remote glovebox robot was working in two gloveboxes at Sellafield, some up to 60 years old, and extended its robotics partnership with Kinova by three years. The work aims to reduce human entry into contaminated enclosures.
-
In November 2025, Orano and Capgemini began a four-month trial of the Hoxo humanoid robot at the Melox facility. The test is the first use of an intelligent humanoid in the nuclear sector.
-
In November 2025, Veolia Nuclear Solutions showed its Dexter force-feedback telemanipulator at the World Nuclear Exhibition in Paris. The system is designed for precise remote work inside hot cells and gloveboxes.
Nuclear Robots Companies are:
-
Veolia Nuclear Solutions
-
Brokk AB
-
AtkinsRéalis
-
Createc
-
Kinova Inc.
-
Eddyfi Technologies
-
ANYbotics AG
-
Victex Co., Ltd. (KAERI technology)
-
Atommash (Rosatom)
Nuclear Robots Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.17 Billion |
| Market Size by 2035 | USD 7.49 Billion |
| CAGR | CAGR of 13.18% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Remote Manipulators, Mobile Crawlers, Aerial Drones, Underwater Robots, and Humanoid Robots) • By Application (Inspection & Monitoring, Maintenance & Repair, Decommissioning, Waste Handling, and Others) • By End User (Nuclear Utilities & Plant Operators, Government & Defense Agencies, Decommissioning & Waste Contractors, and Research Institutions) • By Facility Type (Nuclear Power Plants, Fuel Cycle Facilities, Waste Storage & Disposal Sites, and Research Reactors & Laboratories) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Mitsubishi Heavy Industries, Ltd., Veolia Nuclear Solutions, Brokk AB, AtkinsRéalis, Createc, Boston Dynamics, Kinova Inc., Eddyfi Technologies, ANYbotics AG, Victex Co., Ltd. (KAERI technology), Atommash (Rosatom) |

Frequently Asked Questions
Key players include Mitsubishi Heavy Industries, Veolia Nuclear Solutions, Brokk, AtkinsRéalis, Createc, Boston Dynamics, Kinova, Eddyfi Technologies, ANYbotics, Victex and Atommash.
Key opportunities include fusion maintenance systems, humanoid and legged robots, robotics designed for small modular reactors and demand from emerging nuclear countries.
Ageing reactor fleets, life extensions and a growing backlog of decommissioning projects are the main growth factors, supported by worker safety rules.
By Type, the Remote Manipulators segment dominated the market in 2025 with an estimated 31.55% share, supported by their proven use in handling, cutting and sampling tasks.
North America dominated the market with a share of 40.28% in 2025, driven by the largest operating reactor fleet and large federal cleanup programs.
