
Premium Bottled Water Market Report Scope & Overview:
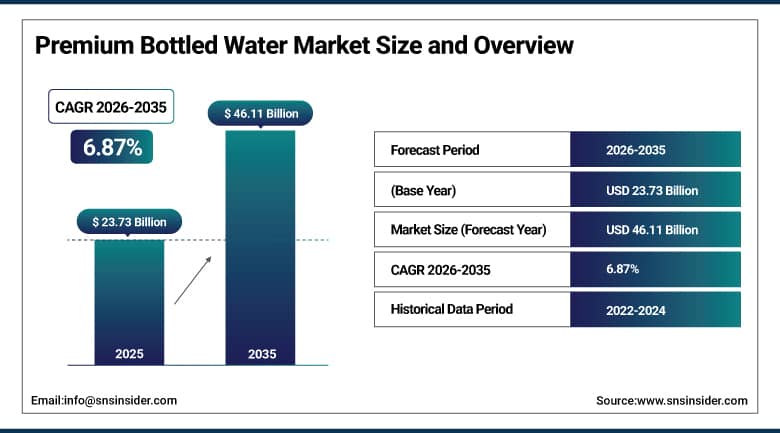
The global Premium Bottled Water Market was valued at USD 23.73 Billion in 2025 and is expected to reach USD 46.11 Billion by 2035, growing at a CAGR of 6.87% from 2026 to 2035.
Premium bottled water is water that has a higher quality and provides additional health value aside from mere hydration, and comes from a particular glacier or spring, thus being cleaner and having an added taste and health benefits. People now consider drinking water not as a need, but as a part of their lifestyle, and companies provide special bottles of water for these people to emphasize the importance.
Glass bottles have been launched by Fiji Water in 2023 in the HoReCa distribution channel to serve premium restaurants and hotels that prefer using less plastic in their offerings but want to keep the same upscale appearance in their packaging solutions – this is one of the trends seen in the premium bottled water industry.
To Get More Information On Premium Bottled Water Market - Request Free Sample Report
Premium Bottled Water Market Trends
- Growing sustainability focus has fueled acceptance of alternative packaging solutions including glass bottles, aluminum cans, and biodegradable materials.
- Rising premium brand emphasis on aesthetics and unique design continues to improve shelf presence and create distinct brand identity from competitors.
- Expanding functional water segment, offering added health benefits including electrolytes and alkalinity, continues to register the fastest product-category growth.
- Increasing rise in premium-priced bottled water is fueled by growing consumer interest in health, wellness, and sustainability positioning.
- Growing direct-to-consumer subscription delivery models and exclusive online product lines continue to accelerate e-commerce channel expansion.
The U.S. Premium Bottled Water Market Outlook
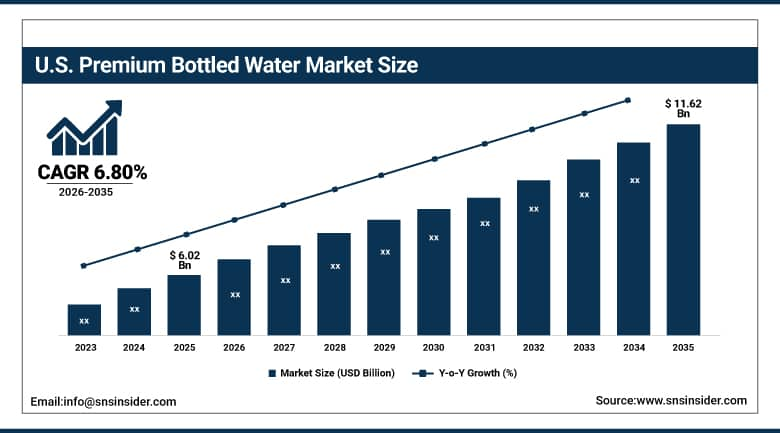
The U.S. Premium Bottled Water Market was valued at USD 6.02 Billion in 2025 and is projected to reach USD 11.62 Billion by 2035, growing at a CAGR of 6.80% during 2026-2035.
Increasing disposable incomes and heightened health consciousness will lead consumers to think more about the quality, purity, and values while choosing products throughout the country. Top brands keep developing their positioning through exclusive water sources and optimized mineral profile in response to the increased demands for superior drinking experiences. Increased eco-consciousness among buyers with regard to sustainable packaging and ethical sourcing practices will lead to continued development of the domestic market.
Rebranding to “Perfection Hydration Alkaline Water” in October 2024, the company focused on the refreshment of its packaging with a focus on sustainability and functionality of its branding with a retained blue color palette along with a new sporty pH-oriented logo, sharper fonts and highlights of the use of environmentally friendly packaging in order to sustain domestic investments into packaging re-design within the functional water category.
Premium Bottled Water Market Segment Analysis
- By Product Type, mineral/spring water led the premium bottled water market with a 43.00% share in 2025, while sparkling water is the fastest-growing product type segment with a CAGR of 7.90% from 2026-2035.
- By Packaging Type, plastic/PET bottles led the premium bottled water market with a 72.20% share in 2025, while cans/aluminum is the fastest-growing packaging type segment with a CAGR of 10.87% from 2026-2035.
- By Distribution Channel, supermarkets/hypermarkets led the premium bottled water market with a 38.00% share in 2025, while online is the fastest-growing distribution channel segment with a CAGR of 9.50% from 2026-2035.
By Product Type, mineral/spring water dominated the market while sparkling water is the fastest-growing segment
Mineral/Spring Water accounted for the largest market share in terms of revenue of 43.00% in the Premium Bottled Water market in 2025 due to increased preference among consumers for naturally-sourced water that is regarded as healthy and premium. The fact that mineral water that is naturally sourced from spring water has good brand positioning and is readily accepted by consumers has helped maintain its leadership position in the global Premium Bottled Water market.
The sparkling water segment is expected to register the fastest CAGR of 7.90% during the forecast period 2026-2035, driven by bottled carbonated water becoming increasingly popular as an alternative to traditional non-alcoholic soft drinks. A combination of health-conscious consumer behavior and changing lifestyle preferences continues to reinforce this segment's above-average growth trajectory, with premium sparkling water brands innovating across flavor profiles and packaging formats.
By Packaging Type, plastic/PET bottles dominated the market while cans/aluminum is the fastest-growing segment
The segment of plastic/PET bottles dominated the premium bottled water market with its revenue share of 72.20% in 2025 owing to PET bottles’ lightweight, cost-effective, durable and widespread application in supermarket, hypermarket and convenience stores. The widespread application of PET bottles is expected to persist as such a packaging type facilitates easy portability and visibility on shelves at a competitive price, thus keeping it dominant in the premium bottled water market.
The cans/aluminum segment is expected to register the fastest CAGR of 10.87% during the forecast period 2026-2035, driven by growing consumer preference for recyclable and environmentally friendly packaging options that address plastic waste concerns. Aluminum's highly recyclable properties and lightweight nature reducing transportation emissions continue to reinforce this segment's above-average growth trajectory relative to conventional plastic and glass packaging formats.
By Distribution Channel, supermarkets/hypermarkets dominated the market while online is the fastest-growing segment
Supermarket/Hypermarket was the major contributor to the premium bottled water market, accounting for a 38.00% revenue share in 2025 due to increased accessibility and consumers’ preference of purchasing bottles at home and while on the move via existing channels. Supermarkets, Hypermarkets, Convenience Stores, and Specialty Retailers offer varied purchase touchpoints that allow customers to buy single bottles and bulk packs, thereby retaining its dominance in the premium bottled water market.
The online segment is projected to register the fastest CAGR of 9.50% during the forecast period 2026-2035, driven by e-commerce and direct-to-consumer platforms accelerating off-trade sales through subscription-based deliveries and exclusive online product lines. Rapid digital transformation and increasing internet connectivity continue to play a key role reinforcing this channel's above-average growth trajectory relative to traditional retail formats.
Regional Analysis
|
Region |
Country |
Share (2025) |
|---|---|---|
|
Europe |
Germany |
24.80% |
|
North America |
United States |
84.60% |
|
Asia Pacific |
China |
34.60% |
|
Middle East & Africa |
UAE |
22.60% |
|
Latin America |
Brazil |
24.60% |
Europe Premium Bottled Water Market Insights
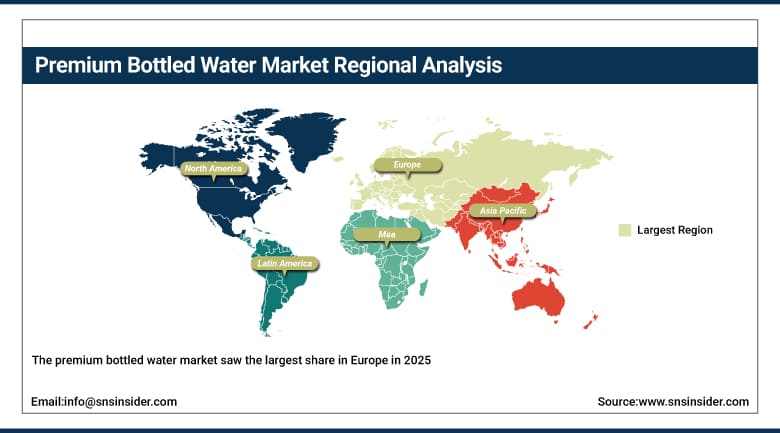
The premium bottled water market saw the largest share in Europe in 2025 owing to the perception of premium bottled water being more than just an essential commodity, and rather a way of life, well-being, and status. Discretionary income levels, along with increased health consciousness, have compelled Europeans to think beyond quality and authenticity, further solidifying Europe's dominance in the premium bottled water space.
The European market was dominated by Germany with a regional share of 24.80% in 2025 owing to its rich history of sourcing minerals and the preference of consumers for natural premium water. Other countries such as France, Italy, and Switzerland are adding value to the regional growth in this market due to their established premium water brands with exclusive springs and glaciers sources.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Premium Bottled Water Market Insights
In the year 2025, North America accounted for a major chunk of the world premium bottled water market owing to the presence of strong premium brand and increasing consumer awareness towards environment-friendly packaging. The region's well-established retail and foodservice distribution channel will continue to strengthen the demand for exclusive bottled water.
The USA occupied around 84.60% share in the North America market during 2025 due to the country's substantial number of premium consumers along with the presence of popular premium bottled water brands. Canada has been responsible for regional growth with regular usage of premium hydration products by consumers and preference for sustainable packaging materials.
Asia Pacific Premium Bottled Water Market Insights
Asia Pacific is projected to grow at the fastest rate during the forecast period 2026-2035, driven by rising health and wellness trends, increasing need for convenience and accessibility, and robust production innovation across China, India, and Southeast Asia. Growing urbanization and expanding modern retail infrastructure continue to reinforce the region's above-average growth trajectory relative to more mature Western markets.
China represented about 34.60% of the Asia Pacific region in 2025 due to the fast-growing population of health-aware consumers in the country. In addition, there is an increase in the number of premium water production manufacturers in China. Other nations in the Asia Pacific region that have contributed to the growth are Japan, South Korea, and India.
Middle East & Africa and Latin America Premium Bottled Water Market Insights
The Middle East & Africa region is exhibiting steady growth as premium retail infrastructure and health-conscious consumer demand continue expanding across the Gulf states. Latin America is similarly benefiting from rising disposable income and growing consumer interest in premium, health-oriented hydration products across major regional urban centers.
In the Middle East & Africa region, the UAE had the largest market share of 22.60% in 2025, owing to the development of premium retail facilities and strong consumer purchasing power. The share of Brazil in the Latin American market was 24.60% in 2025, as a result of increasing demand for premium bottled water, while Mexico too contributed to regional growth.
Market Dynamics
Growth Drivers: Wellness Positioning and Sustainable Packaging Innovation Driving Market Growth
The trend that is fueling the premium bottled water market is mainly due to the fact that more and more consumers are looking out for high quality, mineralized or specialty bottled waters which provide them health benefits such as enhanced hydration, while they prefer the premium bottled water coming from distinct locations. Branding of premium bottled water focuses on purity, exclusiveness and luxury since water in their case is a status symbol as well as a necessity.
Growing sustainability focus continues to fuel acceptance of alternative packaging solutions including glass bottles, aluminum cans, and biodegradable materials. Rising premium brand emphasis on aesthetics and unique design continues to improve shelf presence and create distinct brand identity. Expanding functional water segment, offering added health benefits including electrolytes and alkalinity, continues to register strong product-category growth, reinforcing sustained industry investment across the broader premium water landscape.
Restraints: Environmental Criticism and Price Sensitivity Limiting Market Expansion
The market is bound to have some limitations in the context of environmental criticism especially when brands are dealing with the import/export of water from international regions, raising questions about their carbon footprint. High-end water brands still have to address issues of balancing luxury products with the requirements of sustainable environment among other factors.
Price sensitivity among mainstream consumers continues to limit premium segment penetration beyond affluent and aspirational buyer segments, given premium water often commands 20 to 40 percent higher pricing than mass-market alternatives. Growing competitive intensity among an expanding roster of premium and emerging water brands also continues to fragment the competitive landscape, requiring sustained marketing investment to maintain differentiated brand positioning.
Opportunities: Alternative Packaging Innovation and Functional Water Expansion Creating New Growth Avenues
Substantial opportunity exists in continued development of alternative packaging formats including aluminum cans and biodegradable materials capable of addressing sustainability concerns while maintaining premium brand positioning. Companies that successfully commercialize eco-friendly packaging without compromising luxury presentation stand to capture significant share of category growth as environmentally conscious consumers increasingly influence premium purchasing decisions.
Growing functional water segment expansion, offering electrolytes, alkalinity, and other added health benefits, presents a further significant growth avenue as consumers seek hydration products delivering more than basic purity claims. Expanding online and direct-to-consumer distribution channels across emerging markets in Asia Pacific and Latin America also represent meaningful untapped opportunity for premium bottled water brands.
Recent Developments:
- 2023: Svalbardi expanded its luxury Arctic-sourced bottled water distribution to Asian markets including China and Japan, targeting the growing region with ultra-premium water products.
- 2026: Liquid Death continued its 'Death to Plastic' aluminum can strategy, sourcing mountain spring water from the Austrian Alps in both still and sparkling formats.
- 2026: Voss of Norway continued differentiating through its iconic cylindrical glass bottle and exceptionally low mineral content sourced from a Southern Norway aquifer.
- 2026: Premium mineral water pricing continued trending 20-40% higher than mass-market options, with demand remaining strong as consumers increasingly view premium water as a permissible indulgence.
Premium Bottled Water Market key players are:
- Nestle Waters (Nestle S.A.)
- Danone S.A. (Evian)
- The Coca-Cola Company
- PepsiCo, Inc.
- Fiji Water Company LLC
- Mountain Valley Spring Company
- Svalbardi Polar Iceberg Water
- Voss of Norway ASA
- Icelandic Glacial ehf.
- BlueTriton Brands, Inc.
- Gerolsteiner Brunnen GmbH & Co. KG
- San Pellegrino S.p.A.
- Perrier Vittel S.A.
- Liquid Death Mountain Water
- Essentia Water, LLC
- Uludag Icecek A.S.
- Acqua Panna
- Perfect Hydration, LLC
- Waiakea, Inc.
- Boxed Water Is Better
Premium Bottled Water Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 23.73 Billion |
| Market Size by 2035 | USD 46.11 Billion |
| CAGR | CAGR of 6.87% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Still Water, Sparkling Water, Mineral/Spring Water, Functional Water, Flavored Water) • By Packaging Type (Plastic/PET Bottles, Glass Bottles, Cans/Aluminum, Alternative Packaging) • By Distribution Channel (Supermarkets/Hypermarkets, Specialty Stores, Online) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Nestle Waters (Nestle S.A.), Danone S.A. (Evian), The Coca-Cola Company, PepsiCo, Inc., Fiji Water Company LLC, Mountain Valley Spring Company, Svalbardi Polar Iceberg Water, Voss of Norway ASA, Icelandic Glacial ehf., BlueTriton Brands, Inc., Gerolsteiner Brunnen GmbH & Co. KG, San Pellegrino S.p.A., Perrier Vittel S.A., Liquid Death Mountain Water, Essentia Water, LLC, Uludag Icecek A.S., Acqua Panna, Perfect Hydration, LLC, Waiakea, Inc., Boxed Water Is Better |
Frequently Asked Questions
The Premium Bottled Water Market is expected to grow at a CAGR of 6.87% from 2026 to 2035.
The Premium Bottled Water Market was valued at USD 23.73 Billion in 2025.
The market is driven by consumers increasingly seeking high-quality, mineral-rich, or specialty waters that offer perceived health benefits alongside growing preference for premium, pristine sourcing.
The Mineral/Spring Water segment dominated the Premium Bottled Water Market in 2025, accounting for approximately 43.00% market share.
The Europe region dominated the Premium Bottled Water Market in 2025.
