
Processed & Frozen Vegetables Market Report Scope & Overview:
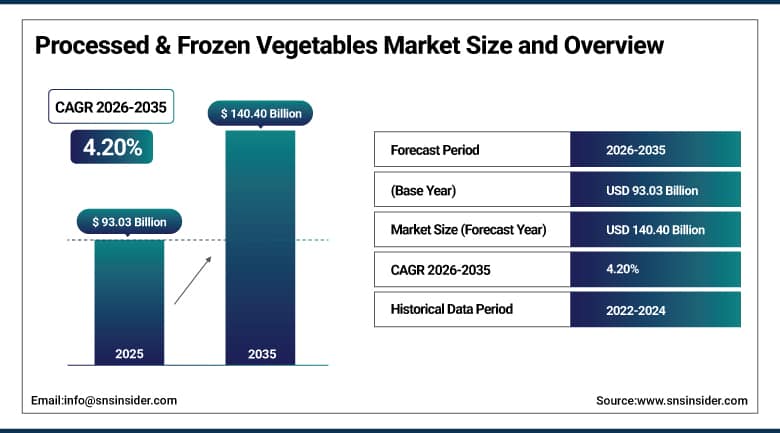
The global Processed & Frozen Vegetables Market was valued at USD 93.03 Billion in 2025 and is expected to reach USD 140.40 Billion by 2035, growing at a CAGR of 4.20% from 2026 to 2035.
Processed and frozen vegetables remain an important part of the food processing industry across the world because of lifestyle changes, urbanization, and the increasing demand for food convenience. There is more awareness about consumer health and the demand for low-calorie foods to avoid any kind of health problems. This ensures the sustained demand for canned and frozen vegetables from the major consuming regions across the world.
McCain Foods USA increased its production capacity at its Burley, Idaho, frozen potato and vegetable factory by investing USD 200 million. It ensures sustained investments made by the major producers of frozen vegetables due to the steady increase in the demand for frozen products across the world because of the increasing fast food chains and retail frozen food sales.
To Get More Information On Processed & Frozen Vegetables Market - Request Free Sample Report
Processed & Frozen Vegetables Market Trends
-
Growing emergence of e-commerce platforms is enabling direct-to-consumer sales of frozen vegetables with customizable portion sizes.
-
Rising adoption of automation and machine learning continues to enhance supply chain agility, helping companies quickly adjust to shifting requirements.
-
Expanding Individual Quick Freezing and improved packaging technologies continue to be critical in preserving quality, flavor, and nutrition.
-
Increasing consumer preference for plant-based diets continues to fuel growth of the frozen vegetable category alongside cold-chain infrastructure expansion.
-
Growing decentralized operations continue to improve organizations' responsiveness to market changes and preserve business continuity amid regional disruptions.
U.S. Processed & Frozen Vegetables Market Outlook
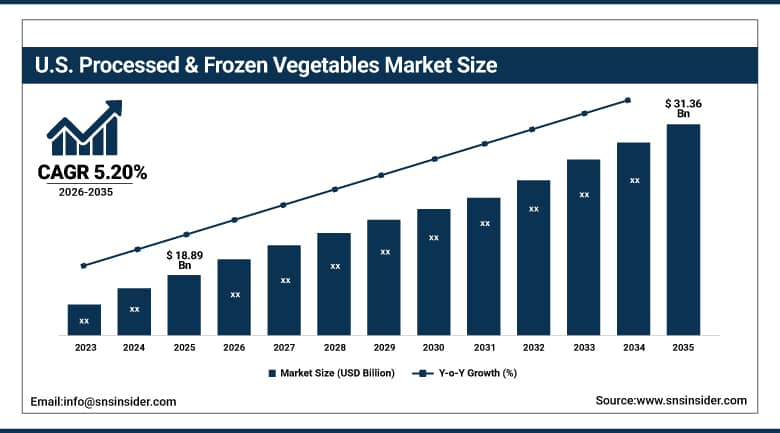
The U.S. Processed & Frozen Vegetables Market was valued at USD 18.89 Billion in 2025 and is projected to reach USD 31.36 Billion by 2035, growing at a CAGR of 5.20% during 2026-2035.
Market expansion remains highly influenced by lifestyle changes among consumers seeking convenience and nutrition at the same time. Major companies continue expanding their frozen potato and vegetables production capabilities in response to sustained demand from fast food restaurants and the frozen food market. Investment in automation and sustainability initiatives further contributes to market expansion on a domestic scale.
Lamb Weston launched new packaging and rebranded its Grown in Idaho retail potato products in 2026, following brand investments made by major frozen vegetable and potato products manufacturing companies, considering that Lamb Weston continues being the leading potato company in North America with yearly sales of approximately USD 2 billion and ranks second in the world behind Canada-based McCain Foods.
Processed & Frozen Vegetables Market Segment Analysis
-
By Product Type, Canned led the Processed & Frozen Vegetables Market with a 41.00% share in 2025, while Frozen is the fastest-growing product type segment with a CAGR of 6.20% from 2026-2035.
-
By Nature, Conventional led the Processed & Frozen Vegetables Market with a 67.63% share in 2025, while Organic is the fastest-growing nature segment with a CAGR of 6.52% from 2026-2035.
-
By Distribution Channel, Supermarkets/Hypermarkets led the Processed & Frozen Vegetables Market with a 31.12% share in 2025, while Online Retail is the fastest-growing distribution channel segment with a CAGR of 8.17% from 2026-2035.
-
By End Use, Retail/Household led the Processed & Frozen Vegetables Market with a 65.00% share in 2025, while Food Service is the fastest-growing end use segment with a CAGR of 6.80% from 2026-2035.
By Product Type, Canned Dominated the Market While Frozen Is the Fastest-Growing Segment
The Canned segment accounted for the largest revenue share of 41.00% in the Processed & Frozen Vegetables Market in 2025 owing to the rising need for foods packed in cans due to their high shelf life stability and existing manufacturing facility. Canned vegetable products have remained beneficial for consumers in terms of health and nutrition, contributing to their dominance in the global processed and frozen vegetables market.
The Frozen segment is expected to witness the highest CAGR of 6.20% during the forecast period 2026-2035 owing to the availability of convenience, nutritious, and healthy frozen vegetables among the consumers through different distribution channels. The growing adoption of Individual Quick Freezing technique has contributed towards the above-mentioned average growth rate of this segment over the canned segment.
By Nature, Conventional Dominated the Market While Organic Is the Fastest-Growing Segment
The Conventional segment led the Processed & Frozen Vegetables Market with a revenue share of 67.63% in 2025, reflecting conventional processing's continued affordability and broad availability relative to certified organic alternatives across mainstream retail channels. Conventional processed and frozen vegetables continue to represent the largest and most established nature category, sustaining this segment's dominant position across the broader market worldwide.
The Organic segment is expected to register the fastest CAGR of 6.52% during the forecast period 2026-2035, driven by growing consumer demand for chemical-free, sustainably produced vegetables amid rising health consciousness and environmental awareness. Increasing organic farming practice adoption across major producing regions continues to reinforce this segment's above-average growth trajectory relative to conventional processing methods.
By Distribution Channel, Supermarkets/Hypermarkets Dominated the Market While Online Retail Is the Fastest-Growing Segment
Supermarkets/Hypermarkets dominated the Processed & Frozen Vegetables Market in 2025, with a revenue share of 31.12%. The widespread reach of the supermarkets/hypermarkets route and consumer purchasing preferences for canned and frozen vegetables have helped maintain this channel’s dominance in the global processed and frozen vegetables market.
Online Retail will witness the fastest CAGR of 8.17%, during the forecast period 2026-2035. This can be attributed to the advent of online platforms providing an avenue for the sale of customized portion sizes of frozen vegetables directly to consumers. Growth in internet usage and e-commerce businesses has helped bolster this channel’s growth rate above average compared to other physical retail routes.
By End Use, Retail/Household Dominated the Market While Food Service Is the Fastest-Growing Segment
The Retail/Household segment accounted for the largest revenue share of 65.00% in the Processed & Frozen Vegetables Market in 2025 owing to consistent household preference for the use of processed and frozen vegetable-based meals in everyday cooking needs. The retail and household end-user segment is the largest and most experienced segment, which is responsible for sustaining its dominance in the processed and frozen vegetables market.
The Food Service segment is anticipated to witness the highest CAGR of 6.80% throughout the forecast period 2026-2035. This is attributed to an increased demand for processed vegetables from quick service restaurants and catering purposes by institutions due to their convenience. The increasing global demand for frozen French fries and vegetable sides in the food service segment continues to bolster its growth rate.
Regional Analysis
|
Region |
Country |
Share (2025) |
|---|---|---|
|
Europe |
Germany |
24.80% |
|
North America |
United States |
84.60% |
|
Asia Pacific |
Japan |
22.60% |
|
Middle East & Africa |
UAE |
20.60% |
|
Latin America |
Brazil |
24.60% |
Europe Processed & Frozen Vegetables Market Insights
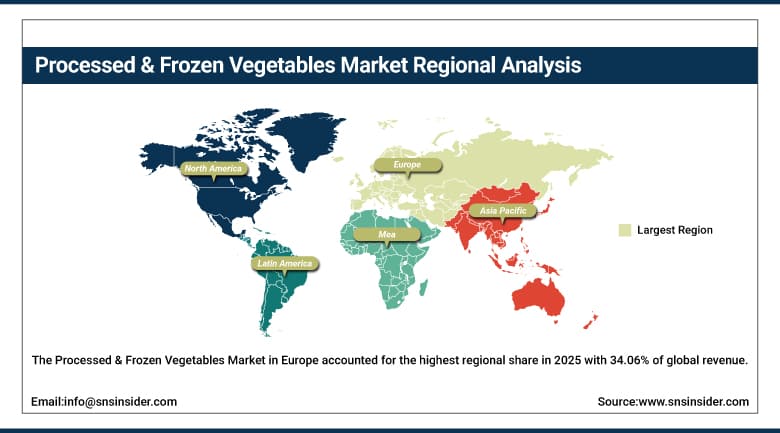
The Processed & Frozen Vegetables Market in Europe accounted for the highest regional share in 2025 with 34.06% of global revenue owing to the presence of many leading manufacturers of processed and frozen vegetables in Europe and a well-developed cold-chain network. Increasing consumer inclination toward plant-based diets will further bolster the dominance of Europe in the entire processed & frozen vegetables market.
Germany had the dominant share in the Europe market with 24.80% in 2025 due to the presence of a well-established food processing industry and leading frozen vegetable brands in Germany. France, the UK, and Belgium are some other countries contributing substantially to regional growth owing to the presence of leading global processed vegetables manufacturers such as Bonduelle and McCain Foods in Europe.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Processed & Frozen Vegetables Market Insights
North America represented a significant share of the global Processed & Frozen Vegetables Market in 2025, supported by changing consumer lifestyles that prioritize convenience while maintaining nutritional value. Extensive frozen potato and vegetable processing infrastructure continues to reinforce the region's strategic importance across the broader processed and frozen vegetables landscape.
The United States accounted for approximately 84.60% of the North American market in 2025, reflecting its large processed and frozen vegetable consumer base and concentration of leading manufacturers including McCain Foods, Lamb Weston, and Conagra Brands. Canada is contributing to regional growth through steady frozen vegetable production and growing export-oriented manufacturing capacity.
Asia Pacific Processed & Frozen Vegetables Market Insights
Asia Pacific is anticipated to have the highest CAGR during the forecast period from 2026-2035, owing to the fastest growth at the country level in Japan, which is facilitated by better access to cold chains in retail sales. Urbanization and increasing disposable income of the middle class continue to fuel above average growth rates in the region compared to more developed Western economies.
In 2025, Japan captured around 22.60% share of the Asia Pacific market, owing to superior cold chain retail networks and rising popularity of ready to cook vegetables amongst consumers. China, India, and South Korea are other nations in the region that are contributing significantly to market growth.
Middle East & Africa and Latin America Processed & Frozen Vegetables Market Insights
There is consistent growth in the Middle East & Africa due to investment in retail infrastructure and cold chain logistics in the Gulf countries. In Latin America, there is consistent growth due to increase in the agricultural processing capacity, as well as due to increased interest in processed vegetable products amongst the consumers in the region.
The UAE dominated the Middle East & Africa market in 2025 with a regional market share of 20.60% on account of the increasing investment in the modern retail infrastructure and cold chain logistics. Brazil accounted for 24.60% share of the Latin America market in 2025 due to an increasing capacity for agricultural processing.
Market Dynamics
Growth Drivers: Convenience-Driven Consumption and Cold-Chain Infrastructure Expansion Driving Market Growth
The Processed & Frozen Vegetables Market is being driven primarily by changing consumer lifestyles, rising urbanization, and increasing demand for convenient food solutions. Processed vegetables include products that undergo preservation, freezing, drying, canning, or juicing to extend shelf life while maintaining nutritional value, with increasing health issues among consumers leading to a surge in demand for low-calorie foods that help prevent further health difficulties.
Growing emergence of e-commerce platforms is enabling direct-to-consumer sales of frozen vegetables with customizable portion sizes. Rising adoption of automation and machine learning continues to enhance supply chain agility. Expanding Individual Quick Freezing and improved packaging technologies continue to be critical in preserving quality, flavor, and nutrition, reinforcing sustained industry investment across canned and frozen product categories.
Restraints: Seasonal Raw Material Dependency and Regulatory Compliance Costs Limiting Market Expansion
While the fundamentals of demand are quite positive, there are some notable limitations associated with the high degree of dependence on seasonality in terms of the availability of raw materials, contributing to the ongoing presence of supply chain uncertainties for producers with year-round processing needs. The need to comply with strict regulations regarding food safety and quality remains an issue of significant costs for manufacturers operating in the market.
The intensifying nature of competition among an increasing number of processed and frozen vegetable companies, in combination with antitrust price fixing litigation involving some leading frozen potato products companies, continues to be a factor influencing competitive trends within the market and exposing firms to legal risks.
Opportunities: Plant-Based Product Expansion and Direct-to-Consumer Distribution Creating New Growth Avenues
There is a considerable chance of business growth through increased expansion within plant-based and functional product segments, considering the growing number of consumers following vegan and vegetarian diets as well as export opportunities to areas where local production does not exist. Manufacturers capable of implementing unique processing technologies can earn considerable market share as consumer interest in ready-made vegetable products grows.
Another area of considerable growth lies within the realm of online sales and direct delivery systems, which have the ability to change the manner in which processed and frozen vegetables are sold to consumers through portion-size customization and subscription programs. Expansion within cold chain infrastructures throughout developing countries in the Asia Pacific and Latin American markets is another area of considerable growth potential.
Recent Developments:
-
2026: McCain Foods celebrated 18 Manufacturing Academy graduates in Scarborough, UK, since launching the program in 2022, enrolling 118 employees for skills development.
-
2026: Strong Roots appointed Emma Curtis as Managing Director, succeeding Charlotte Turton.
-
2024-2025: McCain Foods, Lamb Weston, JR Simplot, and Cavendish Farms faced antitrust price-fixing lawsuits in U.S. courts.
-
2026: Global demand for frozen French fries continued growing steadily, driven by QSR expansion, retail frozen food sales, and convenience trends despite supply volatility and climate-related risks.
Processed & Frozen Vegetables Market key players are:
-
Conagra Brands, Inc.
-
General Mills, Inc.
-
Bonduelle SCA
-
B&G Foods, Inc.
-
McCain Foods Limited
-
The Kraft Heinz Company
-
Nestlé S.A.
-
Unilever PLC
-
J.R. Simplot Company
-
Lamb Weston Holdings, Inc.
-
Dole Food Company, Inc.
-
Del Monte Foods, Inc.
-
Nomad Foods Limited
-
Ardo Group
-
Greenyard NV
-
Iceland Foods Ltd.
-
Seneca Foods Corporation
-
SunOpta Inc.
-
Strong Roots
-
Cavendish Farms Corporation
Processed & Frozen Vegetables Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 93.03 Billion |
| Market Size by 2035 | USD 140.40 Billion |
| CAGR | CAGR of 4.20% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Canned, Frozen, Dried) • By Nature (Conventional, Organic) • By Distribution Channel (Supermarkets/Hypermarkets, Convenience Stores, Online Retail) • By End Use (Retail/Household, Food Service, Industrial) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Conagra Brands, Inc., General Mills, Inc., Bonduelle SCA, B&G Foods, Inc., McCain Foods Limited, The Kraft Heinz Company, Nestlé S.A., Unilever PLC, J.R. Simplot Company, Lamb Weston Holdings, Inc., Dole Food Company, Inc., Del Monte Foods, Inc., Nomad Foods Limited, Ardo Group, Greenyard NV, Iceland Foods Ltd., Seneca Foods Corporation, SunOpta Inc., Strong Roots, Cavendish Farms Corporation |
Frequently Asked Questions
The Processed & Frozen Vegetables Market is expected to grow at a CAGR of 4.20% from 2026 to 2035.
The Processed & Frozen Vegetables Market was valued at USD 93.03 Billion in 2025.
The market is driven by changing consumer lifestyles, rising urbanization, and increasing demand for convenient food solutions.
The Canned segment dominated the Processed & Frozen Vegetables Market in 2025, accounting for approximately 41.00% market share.
The Europe region dominated the Processed & Frozen Vegetables Market in 2025, accounting for approximately 34.06% market share.
