
Rice Market Report Scope & Overview:
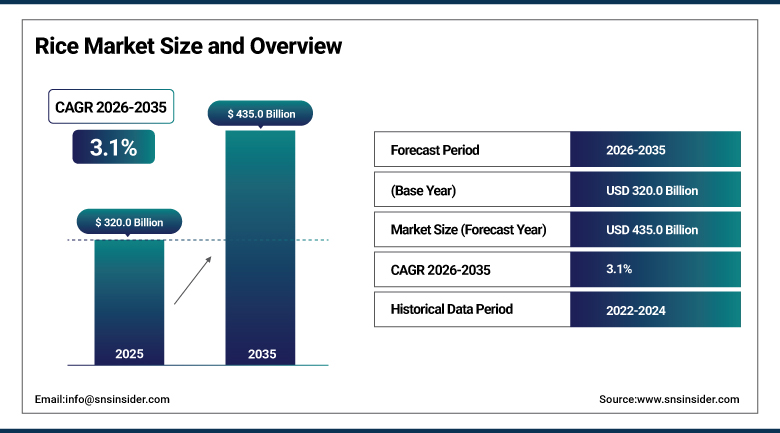
The Rice Market was valued at USD 320.0 Billion in 2025 and is expected to reach USD 435.0 Billion by 2035, growing at a CAGR of 3.1% from 2026–2035.
The Rice Market is growing steadily, owing to the rise in world population, increased consumption, and because rice is an essential part of the diet in Asia, Africa, and other developing nations. The demand for quality and convenience rice products is increasing due to urbanization and rise in incomes. Opportunities in rice export/import business also exists due to the high demands from the countries dependent on imports, especially Africa. Premium products like basmati, jasmine, organic, and specialty rice are preferred by consumers whereas modern channels of rice distribution are also creating opportunities in the market in the form of retail and online stores. Additionally, applications in food processing and value-added rice products are creating opportunities for market expansion till 2035.
India, the world's largest rice exporter, lifted its ban on exports of 100% broken rice in March 2025 after domestic inventories swelled to nearly nine times the government's target storage level, following on from September 2024's removal of the minimum export price on basmati rice. Both moves triggered sharp rallies in listed Indian rice exporters' share prices and underscored just how much a single country's trade policy can move global rice pricing and availability.
To Get more information Rice Market - Request Free Sample Report
Rice Market Trends
-
Branded and premium rice varieties, particularly basmati and jasmine, are gaining share across developed export markets.
-
Health-conscious consumers are increasing demand for brown and whole-grain rice varieties due to higher fiber content.
-
Organic rice production is expanding as clean-label preferences increasingly influence purchasing decisions across staple food categories.
-
Government export policies remain crucial, with stockpile management and restrictions significantly influencing global rice prices.
-
Ready-to-cook and pre-cooked rice formats are expanding as time-constrained consumers seek convenient staple food options.
U.S. Rice Market Outlook
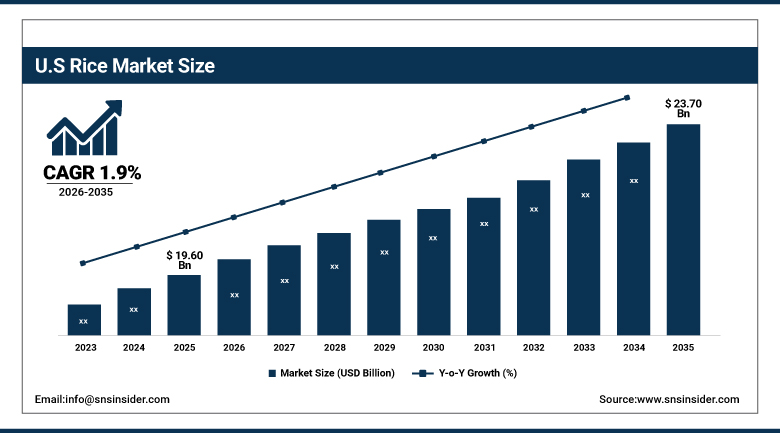
The U.S. Rice Market was valued at approximately USD 19.60 Billion in 2025 and is expected to reach approximately USD 23.70 Billion by 2035, growing at a CAGR of approximately 1.9%.
U.S. rice production is concentrated in Arkansas, Louisiana, California, and a handful of other Gulf Coast and Delta states, with planted acreage expanding in recent seasons on favorable weather and firm grower returns. Domestic consumption spans everyday white rice through premium and specialty categories, with basmati in particular commanding strong brand loyalty among American consumers shaped by South Asian diaspora communities and broader interest in ethnic cuisine. Branded imported rice continues to hold a meaningful share of U.S. retail shelves even as domestic growers supply the bulk of everyday rice consumption.
LT Foods' Royal brand holds more than 50% market share of the U.S. basmati rice segment, a level of category dominance few packaged food brands achieve anywhere in American retail. The company has continued investing in U.S. distribution and brand expansion, including its acquisition of the Golden Star rice brand, as it works to defend that position against both Indian rivals and a growing field of private-label competitors.
Rice Market Segment Analysis
-
By Type, the Regular (White) Rice segment dominated the Rice Market with approximately 52.4% share in 2025, while the Basmati Rice segment is the fastest growing with a CAGR of approximately 5.0%.
-
By Grain Size, the Long Grain segment dominated the Rice Market with approximately 58.6% share in 2025, while the Short Grain segment is the fastest growing with a CAGR of approximately 4.6%.
-
By Color, the White Rice segment dominated the Rice Market with approximately 74.8% share in 2025, while the Brown Rice segment is the fastest growing with a CAGR of approximately 5.8%.
-
By Nature, the Conventional segment dominated the Rice Market with approximately 91.2% share in 2025, while the Organic segment is the fastest growing with a CAGR of approximately 6.9%.
-
By Distribution Channel, the Supermarkets & Hypermarkets segment dominated the Rice Market with approximately 82.0% share in 2025, while the Online Retail segment is the fastest growing with a CAGR of approximately 9.4%.
-
By Application, the Residential & Household segment dominated the Rice Market with approximately 61.4% share in 2025, while the Food Service & HoReCa segment is the fastest growing with a CAGR of approximately 5.2%.
By Type, regular rice dominates, basmati grows fastest
Regular white rice held the largest share of the type segment in 2025, as it continued to be the staple in most cultures and cuisines across the world that consume rice. The relatively inexpensive nature of the product, along with its abundance and versatility to go well with all meals, ensures that standard white rice will continue to be the default type in the vast majority of rice consumed around the globe.
Basmati rice is experiencing rapid growth due to the increasing international preference for high-end long-grain rice with aromatic properties in Western countries like North America and Europe apart from its native South Asia and Middle East. This has been aided by the opening up of Indian exports along with heavy branding efforts in the West by key basmati producers.
By Grain Size, long grain dominates, short grain grows fastest
Long grain rice accounted for the largest share of the grain-size segment in 2025, favored for its light, fluffy texture after cooking and its versatility across a wide range of cuisines from South Asian biryanis to American jambalaya. That broad culinary applicability keeps long grain the default choice across most retail and foodservice channels.
Short grain rice is growing fastest as demand for sushi, risotto, and other short-grain-dependent dishes expands beyond their traditional cultural markets into broader Western dining and home cooking. Rising interest in Japanese and Italian cuisine specifically has pulled short grain rice into mainstream Western grocery assortments in a way it wasn't a decade ago.
By Color, white rice dominates, brown rice grows fastest
White rice, meaning rice that has had its bran layer milled away, held the overwhelming majority of the color segment in 2025, remaining the default choice across nearly every major rice-consuming market due to its faster cooking time, longer shelf life, and milder flavor relative to unmilled varieties.
Brown rice is growing fastest as health-conscious consumers seek out its higher fiber content and lower glycemic index relative to white rice. That health positioning has made brown rice a genuine beneficiary of the broader whole-grain and low-glycemic-index eating trends spreading across developed markets, even though it remains a modest share of total rice volume.
By Nature, conventional dominates, organic grows fastest
Conventional rice continues to account for the overwhelming majority of volume, reflecting both cost sensitivity among large-volume buyers and the simple fact that certified organic rice acreage remains a small fraction of total global rice cultivation. Government food security programs and bulk institutional buyers are almost entirely focused on conventional rice given its lower cost and higher available supply.
Organic rice is growing fastest, albeit from a small base, as clean-label demand spreads from packaged and processed foods into staple grains that consumers previously purchased without much regard for cultivation method. Premium retailers and health-focused consumers are driving most of this growth, willing to pay a meaningful premium for certified organic rice even as it remains a niche category relative to total market volume.
By Distribution Channel, supermarkets & hypermarkets dominate, online retail grows fastest
Supermarkets and hypermarkets represented the highest share of the distribution channel in 2025 because they remain the main place from which most families would purchase rice due to the flexibility in terms of offering variety, good pricing, and convenience in one-stop grocery shopping. The bulk packaging choice offered through this channel also attracts larger families and budget-conscious customers buying rice as an essential foodstuff.
The fastest-growing distribution channel is the online channel as consumers become accustomed to making their purchases through online grocery stores when it comes to staple and non-perishable items such as rice. The automated subscription service for household staples works especially well in the case of this item.
By Application, residential & household dominates, food service & HoReCa grows fastest
Residential and household consumption accounted for the largest application share in 2025, reflecting rice's role as a daily dietary staple prepared at home across a majority of the world's population. That sheer breadth of everyday home cooking use keeps household consumption the largest single application by a wide margin.
Food service and HoReCa is the fastest-growing application as expanding restaurant, hotel, and catering sectors globally incorporate rice, particularly premium varieties like basmati, into a growing range of menu items. Institutional demand from airline caterers, hospital food services, and corporate canteens is adding a further layer of growth to this category as these buyers increasingly specify premium branded rice varieties over generic bulk supply.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
Asia Pacific |
India |
41.0% |
|
North America |
United States |
68.0% |
|
Europe |
Italy |
24.0% |
|
Latin America |
Brazil |
41.0% |
|
Middle East & Africa |
Nigeria |
33.0% |
North America Rice Market Insights
North America represents a mature but steadily growing rice market, with the United States serving as both a significant domestic producer and a major importer of premium and specialty rice varieties from Asia. Domestic production is concentrated in Arkansas, Louisiana, California, and other Gulf Coast and Delta growing regions with long-established rice cultivation infrastructure.
Canada's market remains largely import-dependent given its limited domestic rice cultivation capacity, while Mexico contributes both modest domestic production and growing consumption tied to its expanding food processing and foodservice sectors. Branded imported rice, particularly basmati, continues gaining shelf space across the region as ethnic cuisine adoption and premium positioning both support continued category growth.
Europe Rice Market Insights
Europe represents a smaller but well-established rice market, split between limited domestic production concentrated in Italy and Spain and substantial reliance on imports from Asia and the Americas to meet broader consumption needs. Italy anchors regional demand, home to a centuries-old risotto tradition and significant Arborio rice cultivation.
The United Kingdom, France, and Germany contribute meaningful consumption as well, with South Asian diaspora communities in several countries driving strong and steady demand for basmati and other aromatic rice varieties. Growing interest in ethnic cuisine more broadly across Western Europe continues to expand the range of rice varieties European retailers stock beyond traditional short-grain risotto rice.
Asia Pacific Rice Market Insights
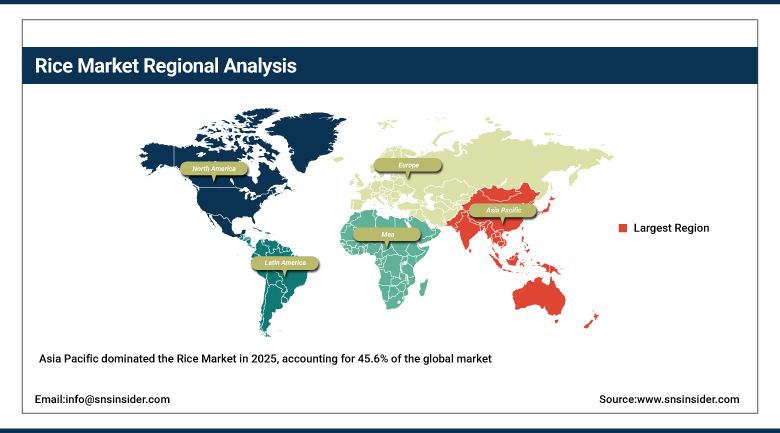
Asia Pacific dominated the Rice Market in 2025, accounting for 45.6% of the global market. The dominance of the region is justified by the high volume of production and consumption of rice, the importance of which is determined by its importance in the diet and agricultural sector. The two countries that form the main share of production and consumption of the region are China and India, but rice continues to play an important role in diets in Southeast Asia. The region is additionally characterized by large population growth, increased food consumption, existing rice processing industry, and favorable agricultural conditions.
The position of the largest exporter of rice on the part of India makes it the most influential country in relation to the global rice trade and price formation. Export restriction decisions and the adoption of minimal prices can have a great impact on global rice markets. Southeast Asian countries also include Thailand and Vietnam, which are important rice producers and exporters to Africa and the Middle East.
Get Customized Report as per Your Business Requirement - Enquiry Now
Middle East & Africa Rice Market Insights
The Middle East and Africa are anticipated to post the fastest regional growth until 2035 on account of growing population growth and expanding food security programs in several African countries where rice consumption is growing as a proportion of total diet consumption. Nigeria leads regional demand with one of the largest rice consuming populations in the continent as well as domestic production and imports.
Basmati and other premium rice types have a special significance for the Middle East, which has led to sustained demand for branded Indian and Pakistani exports despite attempts by several countries to increase domestic rice production capabilities. Improvement in geopolitical stability in parts of the region in recent years has positively impacted the export prospects for major rice producers from Asia.
Market Dynamics
Growth Drivers: Population growth and premiumization fueling market expansion
Continued global population growth, particularly across rice-dependent regions of Asia and Africa, is one of the clearest forces behind rising rice demand, since rice remains the primary caloric source for a majority of the world's population. That demographic tailwind gives the rice market a demand floor that few other food categories can match in scale or consistency.
Premiumization adds a second major driver, as branded basmati, jasmine, and other aromatic varieties continue commanding real price premiums in both domestic and export markets. Rising incomes across emerging markets are giving more consumers the purchasing power to trade up from generic bulk rice to branded, premium varieties, supporting revenue growth that outpaces underlying volume growth.
Restraints: Export policy volatility and climate risk limiting supply predictability
One of the major causes of uncertainty in the rice market still comes from the government’s policies on rice exports because exporting nations from time to time change their policies to export restrictions based on their food stock and food security requirements. These policy changes have the ability to affect prices of rice internationally over a single trading season.
Another cause of uncertainty in the supply of rice comes in the form of climatic conditions because rice requires a specific amount of rain during the monsoon period for its growth. Climate change and weather disasters have the ability to impact the supply of rice and it is expected that this situation will be even worse in the future.
Opportunities: Branded premiumization and fortification programs opening new growth avenues
Continued premiumization of branded rice varieties offers producers and exporters a genuine path to revenue growth that outpaces the relatively modest volume growth typical of a mature staple food category. Companies that build strong export brands, verified provenance, and consistent quality are positioned to capture premium pricing that bulk commodity rice simply can't command.
Expanding rice fortification programs represent a second significant opportunity, as governments across Asia and Africa increasingly fortify rice with essential vitamins and minerals to address widespread micronutrient deficiencies. Producers that build fortification capability early are positioned to capture a growing and relatively stable source of institutional demand as these public health programs continue to scale.
Recent Developments:
-
February 2026: KRBL Limited reported a recovery in basmati export volumes and announced plans to expand its Maharani brand internationally alongside new domestic retail distribution.
-
2025: Geopolitical stability improvements across the Middle East and Africa, the largest basmati consumption region, supported a stronger export outlook for Indian and Pakistani producers.
-
August 2025: Tilda launched a new line of low glycemic index rice products aimed at health-conscious consumers, part of a broader premiumization push across branded rice categories.
-
September 2025: Lundberg Family Farms announced a partnership with a leading health food retailer to expand distribution of its low glycemic index and specialty rice offerings.
Rice Market Key Players
-
LT Foods Limited
-
KRBL Limited
-
Ebro Foods S.A.
-
Olam Agri
-
Wilmar International Limited
-
Riceland Foods, Inc.
-
SunRice Group
-
Tilda Limited
-
Charoen Pokphand Foods Public Company Limited
-
Thai Hua Co., Ltd.
-
Asia Golden Rice Co., Ltd.
-
Vietnam Southern Food Corporation (Vinafood 2)
-
Farmers' Rice Cooperative
-
Doguet's Rice Milling Company
-
SunFoods, LLC
-
REI Agro Ltd.
-
Kohinoor Foods Limited
-
Amira Nature Foods Ltd.
-
Lundberg Family Farms
-
Capitol Rice Products Co.
Rice Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 320.0 Billion |
| Market Size by 2035 | USD 435.0 Billion |
| CAGR | CAGR of 3.1% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Regular/White Rice, Basmati Rice, Jasmine Rice, Parboiled Rice, Glutinous & Sushi Rice, Others) • By Grain Size (Long Grain, Medium Grain, Short Grain) • By Color (White Rice, Brown Rice, Red Rice, Black Rice) • By Nature (Conventional, Organic) • By Distribution Channel (Supermarkets & Hypermarkets, Convenience Stores, Online Retail, Others) • By Application (Residential & Household, Food Service & HoReCa, Food Processing & Industrial) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | LT Foods Limited, KRBL Limited, Ebro Foods S.A., Olam Agri, Wilmar International Limited, Riceland Foods, Inc., SunRice Group, Tilda Limited, Charoen Pokphand Foods Public Company Limited, Thai Hua Co., Ltd., Asia Golden Rice Co., Ltd., Vietnam Southern Food Corporation (Vinafood 2), Farmers' Rice Cooperative, Doguet's Rice Milling Company, SunFoods, LLC, REI Agro Ltd., Kohinoor Foods Limited, Amira Nature Foods Ltd., Lundberg Family Farms, Capitol Rice Products Co. |

Frequently Asked Questions
Key players include LT Foods Limited, KRBL Limited, Ebro Foods S.A., Olam Agri, and Wilmar International Limited, among others.
Key opportunities include basmati rice demand, branded premiumization, online retail expansion, food fortification programs, climate-resilient cultivation, and foodservice demand.
Continued global population growth across rice-dependent regions, alongside premiumization of branded basmati, jasmine, and other aromatic rice varieties.
Regular (White) Rice dominated with approximately 52.4% share in 2025, while Basmati Rice is the fastest growing segment with a CAGR of approximately 5.0%.
Asia Pacific dominated the Rice Market in 2025, while Middle East & Africa is the fastest-growing region.
