
Septic Tanks Market Report Scope & Overview:
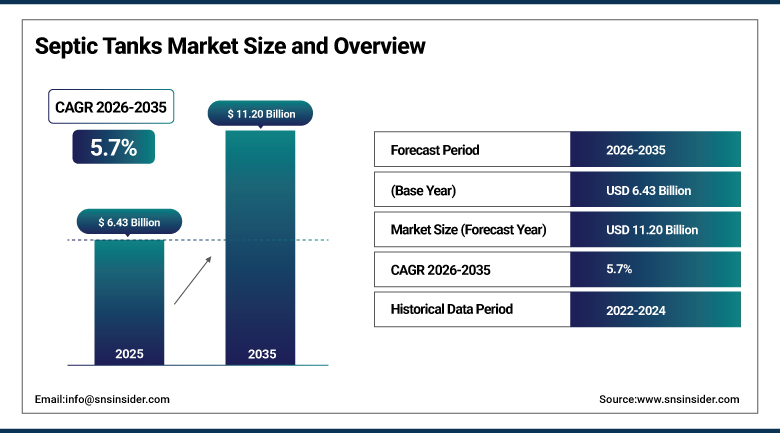
The Septic Tanks Market was valued at USD 6.43 billion in 2025 and is projected to reach USD 11.20 billion by 2035, expanding at a CAGR of 5.7% during the forecast period.
The septic tank is an underground waterproof container made up of materials like concrete, plastic, fiberglass, or steel which is used for treating wastewater using the process of sedimentation and anaerobic digestion and then the effluent is discharged into drain fields. The rural residential markets have been the biggest adopters so far since decentralized wastewater treatment is the basic method of sanitation in areas where there is no municipal sewer system available. Increasing regulatory oversight of effluent quality along with the usage of newer technology like the aerobic treatment units is continually changing the landscape.
There are EPA rules and state environmental codes which are increasingly requiring regular inspection periods and effluent quality criteria and thus pushing homeowners and business proprietors to upgrade or replace their tanks irrespective of any population growth in numbers. Concrete products retain the largest installed base given decades of building code grandfathering and contractor familiarity, though plastic tank segments continue to gain ground based on lighter transport logistics and corrosion immunity in acidic soil conditions. Manufacturers increasingly bundle extended warranty and inspection service programs with tank sales, reflecting growing consumer expectation for lifecycle support beyond the initial equipment purchase. This service bundling trend is particularly pronounced among manufacturers targeting the commercial and institutional segment, where facility owners increasingly prefer a single accountable vendor relationship over separately contracting tank supply and installation.
The U.S. tariff changes that have been made up until 2025 have impacted the supply of septic tank components and the choice of suppliers, due to the increased tariffs on some components and raw materials leading to a need to reevaluate their supply chain and diversify suppliers.
To Get more information Septic Tanks Market - Request Free Sample Report
Septic Tanks Market Trends
-
Rising adoption of aerobic treatment units enhancing waste breakdown and reducing pumping frequency
-
Growing shift toward plastic and fiberglass tanks for lighter transport logistics and corrosion resistance
-
Increasing regulatory scrutiny of effluent quality driving accelerated tank upgrade and replacement cycles
-
Rising integration of Internet-of-Things telemetry for remote septic system monitoring and maintenance alerts
-
Growing use of precast concrete tanks in commercial and government applications requiring traffic-bearing structural ratings
U.S. Septic Tanks Market Outlook
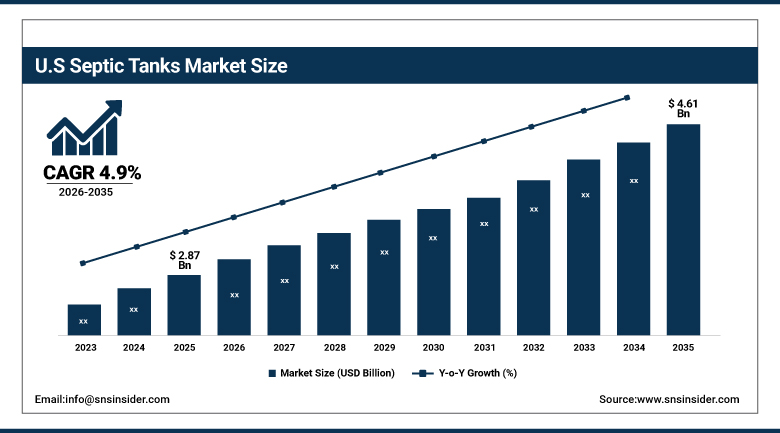
The U.S. septic tanks market was valued at USD 2.87 billion in 2025 and is projected to reach USD 4.61 billion by 2035, growing at a CAGR of 4.9% during 2026-2035.
The U.S. market benefits from a substantial installed base of rural and exurban residential septic systems, with demand concentrated in the American Southeast, where clay-heavy soils and low population density make conventional septic systems the default sanitation approach relative to centralized sewer infrastructure. State-level environmental codes increasingly mandate regular inspection and effluent quality compliance, driving steady replacement demand across an aging installed tank base regardless of new residential construction activity.
U.S. manufacturers are increasingly diversifying component sourcing in response to recent tariff adjustments affecting imported raw materials, with several suppliers nearshoring key production steps to reduce exposure to continued trade policy volatility affecting procurement timing and cost. Real estate transaction requirements in several states now mandate septic system inspection disclosure at time of sale, further reinforcing steady replacement demand independent of new residential construction cycles. Contractor certification and licensing requirements also vary meaningfully by state, adding a further layer of market fragmentation that favors installers and suppliers with strong regional relationships over national footprints alone.
Continued population growth and residential construction across exurban and rural U.S. regions lacking centralized sewer access continue to sustain steady new septic system installation demand, even as replacement and upgrade activity on the existing installed base increasingly represents the larger share of total market revenue.
Septic Tanks Market Segment Analysis
Segmentation of the septic tanks market by material type, installation type, and end use reflects the durability, cost, and regulatory compliance trade-offs property owners and contractors weigh when specifying decentralized wastewater treatment systems.
-
By Material Type, the Concrete segment dominated the Septic Tanks Market with approximately 47.8% share in 2025, while the Plastic segment is the fastest growing with a CAGR of approximately 7.9%.
-
By Installation Type, the Below-Ground segment dominated the Septic Tanks Market with approximately 81.6% share in 2025, while the Above-Ground segment is the fastest growing with a CAGR of approximately 7.2%.
-
By End Use, the Residential segment dominated the Septic Tanks Market with approximately 64.3% share in 2025, while the Commercial segment is the fastest growing with a CAGR of approximately 7.6%.
By Material Type, Concrete Dominates the Septic Tanks Market While Plastic Registers the Fastest Growth
Concrete dominated the Septic Tanks Market in 2025 due to the fact that this material offers exceptional durability, structural load capacity, and decades of proven performance that has become deeply embedded in building codes and contractor installation practices across most jurisdictions. Concrete tanks retain their largest-segment position particularly in commercial and government specifications where structural load ratings and traffic-bearing requirements make precast concrete the preferred choice.
The most rapidly expanding product segment within the market for septic tanks is plastics due to the fact that polyethylene tanks are much more lightweight, easily and economically transported, and have better corrosion resistance compared to their concrete counterparts in acid soils. Increasing requirements for residential installers for a faster and less costly process of installing the tanks due to their light weight are growing.
Tanks made of fiberglass and steel are still used in smaller applications; however, fiberglass is preferable due to its lightweight and good resistance to chemicals, whereas steel tanks are no longer installed in new residential buildings due to better corrosion resistance of modern plastic and fiberglass tanks.
By Installation Type, Below-Ground Dominates the Septic Tanks Market While Above-Ground Registers the Fastest Growth
Below-Ground dominated the Septic Tanks Market in 2025 due to the fact that underground installation remains the standard configuration for both residential and commercial septic systems, offering protection from surface disturbance, temperature fluctuation, and the discreet integration property owners and regulatory codes typically require.
Above-Ground is the fastest-growing segment in the Septic Tanks Market due to the fact that this installation type is increasingly specified for sites with high water tables, rocky terrain, or other subsurface conditions that make conventional below-ground installation impractical or costly, expanding the addressable market to previously underserved geographic areas.
By End Use, Residential Dominates the Septic Tanks Market While Commercial Registers the Fastest Growth
Residential dominated the Septic Tanks Market in 2025 due to the fact that rural and exurban single-family and multi-family residential properties represent the largest and most established base of decentralized wastewater treatment demand globally, sustained by ongoing population growth and continued residential construction in areas lacking centralized sewer access.
Commercial is the fastest-growing segment in the Septic Tanks Market due to the fact that education, healthcare, hospitality, and retail properties in areas without centralized sewer access increasingly require advanced septic systems capable of handling higher and more variable wastewater volumes, while facing more stringent effluent quality compliance requirements than typical residential installations.
Industrial end use remains a smaller but steady demand category, with food processing, manufacturing, and mining facilities in areas without centralized sewer access requiring specialized high-capacity septic and wastewater pretreatment systems engineered to handle process-specific effluent characteristics.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.0% |
|
Europe |
Germany |
21.0% |
|
Asia Pacific |
India |
37.0% |
|
Middle East & Africa |
South Africa |
24.0% |
|
Latin America |
Brazil |
39.0% |
North America Septic Tanks Market Insights
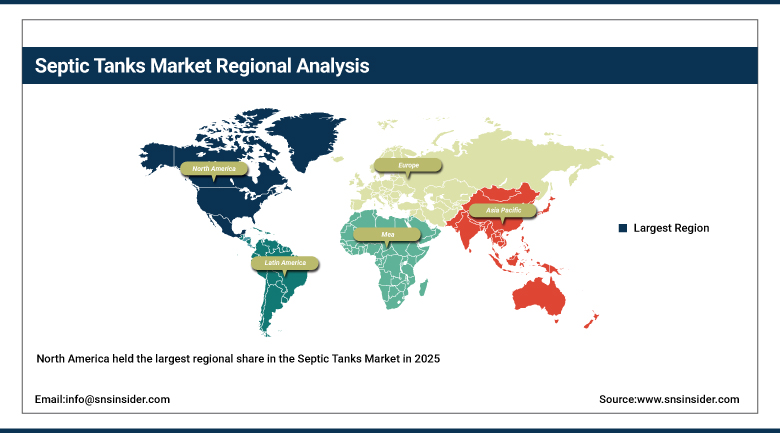
North America held the largest regional share in the Septic Tanks Market in 2025, with demand concentrated in the American Southeast, where clay-heavy soils and low population density make conventional septic systems the default sanitation approach relative to centralized municipal sewer infrastructure.
Canadian septic system demand continues to expand across rural Ontario and the Atlantic provinces, supported by similar decentralized wastewater treatment needs in areas without access to municipal sewer connections.
Mexican septic tank demand continues to grow steadily alongside broader North American residential construction trends, though the market remains smaller in scale than the deeply established U.S. rural residential installed base.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Septic Tanks Market Insights
The European market for wastewater treatment is dependent upon different national regulations regarding this process, where rural areas of France, Germany, and Eastern Europe still make use of decentralized septic tanks due to the expensive process of extending the centralized sewer system in those areas.
The rural areas of Eastern Europe, especially those of Poland and Romania, still largely use decentralized septic tanks, although the gradual financial assistance from the EU has contributed towards modernizing the existing tank system.
Asia Pacific Septic Tanks Market Insights
Asia Pacific is the fastest-growing region in the Septic Tanks Market, led by India and Southeast Asian markets, where rapid rural and peri-urban population growth continues to expand demand for decentralized sanitation infrastructure in areas where centralized sewer network expansion lags behind population growth.
Indian government sanitation initiatives continue to drive substantial rural septic system installation, while Southeast Asian markets including Indonesia and Vietnam are expanding decentralized wastewater treatment infrastructure to serve rapidly growing peri-urban populations.
Chinese rural sanitation modernization programs continue to expand alongside India's, though centralized sewer infrastructure investment in China's rapidly urbanizing regions is progressively reducing the addressable decentralized wastewater treatment market in the country's more developed coastal provinces.
Middle East & Africa and Latin America Septic Tanks Market Insights
The Middle East & Africa region continues to grow on an ongoing basis as there has been continued investment in sanitation infrastructure in the rural areas of both South Africa and North African countries due to government programs designed to enhance waste water treatment in areas without centralized sewer infrastructure. Municipal and provincial sanitation projects in South Africa continue to grow in relation to the installation of rural septic systems in communities where investment in centralized sewer infrastructure does not make economic sense due to the lower population densities.
Latin America continues to grow due to ongoing residential construction in the rural areas of Brazil and Mexico. Residential construction in Mexico has seen increasing demand for decentralized septic systems in areas that lack municipal sewer infrastructure, especially areas around fast-growing secondary cities.
Market Dynamics
Growth Drivers: Population growth and tightening effluent regulations sustaining replacement demand
Continued global population growth and residential construction in areas lacking centralized sewer access remains the primary structural driver of septic tank demand, as decentralized wastewater treatment continues to be the default sanitation solution for rural and low-density residential development worldwide. Rising regulatory scrutiny of effluent quality, including EPA regulations and state-level environmental codes mandating regular inspection intervals, continues to drive accelerated tank upgrade and replacement cycles that extend demand well beyond simple new installation growth. Growing adoption of advanced treatment technologies, including aerobic treatment units that enhance waste breakdown efficiency and reduce pumping frequency, is expanding average system value even where overall unit volume growth remains moderate.
Aging installed septic tank infrastructure across mature markets, particularly the United States, continues to generate substantial replacement demand as decades-old concrete tanks reach the end of their structural service life and require full system replacement. Growing homebuyer and lender awareness of septic system condition as a factor in residential property transactions is increasingly driving pre-sale inspections that surface replacement needs earlier than they might otherwise be identified, indirectly accelerating market-wide replacement activity. Rising insurance industry scrutiny of septic system age and condition, increasingly factored into property insurance underwriting decisions in some markets, is creating an additional incentive for property owners to proactively replace aging systems before they become a barrier to obtaining affordable coverage.
Restraints: Tariff-driven input costs and centralized sewer expansion limiting growth
The impact of United States tariffs in terms of imports of components and raw materials used in construction is an issue still causing uncertainty, which has prompted manufacturers to seek other suppliers, thus making their relationships costly and more complex than before. Extension of centralized sewerage systems within the cities into the suburbs will reduce the need for septic tanks in areas that have been served, thus acting as a headwind in areas that have been urbanized quickly with investment in infrastructure keeping up with the pace of population growth.
The high installation costs linked to the precast concrete tanks have been a problem preventing the uptake in the market of cost-sensitive customers. Labor shortages among septic tank installers and inspectors in various markets have slowed down the fulfillment of demand.
Opportunities: Smart monitoring technology and emerging-market sanitation investment widening addressable demand
Growing integration of Internet-of-Things telemetry for remote septic system monitoring presents a significant opportunity for manufacturers and service providers to offer value-added maintenance alerting services, differentiating from commodity tank sales through ongoing service revenue. Expanding government rural sanitation infrastructure investment across Asia Pacific and parts of Africa presents a substantial growth opportunity for septic tank manufacturers able to offer cost-effective, easily transportable plastic and fiberglass tank solutions suited to developing-market installation conditions.
Growing commercial and institutional demand for advanced septic systems capable of meeting stricter effluent quality standards offers manufacturers an opportunity to develop higher-margin, technology-enhanced product lines beyond basic residential tank offerings. Growing homeowner interest in extended-life, low-maintenance tank materials presents an opportunity for manufacturers to develop premium product lines that command higher margins than standard commodity concrete and plastic tank offerings. Growing manufacturer interest in offering septic system design and installation services alongside tank sales presents an opportunity to capture a larger share of total project value, moving beyond commodity product sales into higher-margin, full-service project delivery.
Recent Developments
-
In 2024, Infiltrator Water Technologies expanded its plastic septic tank and leach field manufacturing capacity in the United States to serve growing residential replacement and new installation demand.
-
In 2023, Norwesco Inc. introduced an updated polyethylene septic tank line featuring enhanced structural reinforcement for both residential and light commercial applications.
-
In 2023, Roth Global Plastics announced expanded septic tank production capacity in Europe to serve growing rural sanitation infrastructure demand across the continent.
-
In 2023, Snyder Industries expanded its polyethylene tank manufacturing capacity in the Midwest to serve growing agricultural and residential septic system demand.
-
In 2023, Advanced Drainage Systems Inc. announced expanded polyethylene septic tank and leach field production capacity to serve growing U.S. residential replacement demand.
Septic Tanks Market key players are:
-
Infiltrator Water Technologies
-
Norwesco Inc.
-
Xerxes Corporation (Shawcor)
-
Roth Global Plastics
-
Zoeller Company
-
Snyder Industries
-
Anua International
-
Bio-Microbics Inc.
-
Clarus Environmental
-
Jet Inc.
-
Polylok Inc.
-
Wieser Concrete Products
-
Oldcastle Infrastructure
-
Rehau Group
-
Graf GmbH
-
Premier Tech Water and Environment
-
Orenco Systems Inc.
-
Presby Environmental Inc.
-
National Precast Concrete Association Members
-
Advanced Drainage Systems Inc.
Septic Tanks Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 6.43 Billion |
| Market Size by 2035 | USD 11.20 Billion |
| CAGR | CAGR of 5.7% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Material Type (Concrete, Plastic, Fiberglass, Steel) • By Installation Type (Below-Ground, Above-Ground) • By End Use (Residential, Commercial, Industrial) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Infiltrator Water Technologies, Norwesco Inc., Xerxes Corporation (Shawcor), Roth Global Plastics, Zoeller Company, Snyder Industries, Anua International, Bio-Microbics Inc., Clarus Environmental, Jet Inc., Polylok Inc., Wieser Concrete Products, Oldcastle Infrastructure, Rehau Group, Graf GmbH, Premier Tech Water and Environment, Orenco Systems Inc., Presby Environmental Inc., National Precast Concrete Association Members, Advanced Drainage Systems Inc. |
Frequently Asked Questions
Leading companies include Infiltrator Water Technologies, Norwesco Inc., Xerxes Corporation, Roth Global Plastics, and Zoeller Company, among other major concrete, plastic, and fiberglass tank manufacturers.
Opportunities include growing integration of Internet-of-Things telemetry for remote system monitoring, expanding government rural sanitation infrastructure investment across Asia Pacific and Africa, and growing commercial demand for advanced, technology-enhanced septic systems.
Growth is driven by continued population growth and residential construction in areas lacking centralized sewer access, rising regulatory scrutiny of effluent quality driving replacement cycles, and aging installed infrastructure across mature markets.
Concrete dominates by material type with approximately 47.8% share, Below-Ground dominates by installation type with roughly 81.6% share, and Residential dominates by end use with about 64.3% share; Plastic, Above-Ground, and Commercial are the fastest-growing segments within their respective categories.
North America is the largest regional market, led by the United States, while Asia Pacific, led by India, is the fastest-growing region through 2035.
