
Soup Market Report Scope & Overview:
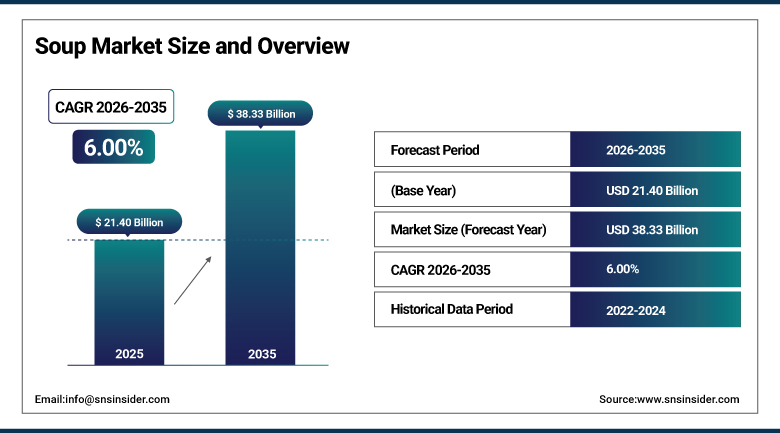
The Soup Market was valued at USD 21.40 Billion in 2025 and is expected to reach USD 38.33 Billion by 2035, growing at a CAGR of 6.00% from 2026 to 2035.
The Soup Market is growing at a rapid pace owing to growing consumer demand for convenient, ready-to-eat packaged food products. Soup is a primarily liquid food, often served warm or hot, made by combining various ingredients of meat or vegetables with stock, juice, water, or another liquid, available across canned, dried, refrigerated, frozen, and instant formats meeting rising demand for convenience, seasonal comfort, and evolving dietary habits. Moreover, the growth of the market is also fueled by the rising consumer demand for soups made from clean ingredients with reusable and sustainable packaging options, growing preference for ready-to-eat foods, and the shift towards a plant-based diet in consumers.
Based on dietary assessment studies in America, 94% of adults aged 19 to 64 eat soup, whereby 60% of them eat soup less than four times per month during winter, while more than 80% of them do the same during other months of the year.
To Get more information Soup Market - Request Free Sample Report
Soup Market Trends
-
Rising urbanization and dual-income households are encouraging higher adoption of ready-made soups, supported by improved supply chains and strong retail penetration.
-
Growing chilled soup segment appeal is resonating with health-conscious consumers willing to pay a premium for fresh quality, supported by advancements in cold chain infrastructure.
-
Increasing manufacturer product innovation is delivering a wide array of flavors and dietary options, addressing consumer health consciousness favoring nutrient-rich soup variants.
-
Expanding e-commerce penetration and subscription-based delivery models are broadening online soup distribution, driven by digital grocery adoption and direct-to-consumer models.
-
Strategic partnerships among soup manufacturers, retailers, and cold chain logistics providers are supporting development of increasingly diverse, premium soup product portfolios.
U.S. Soup Market Outlook
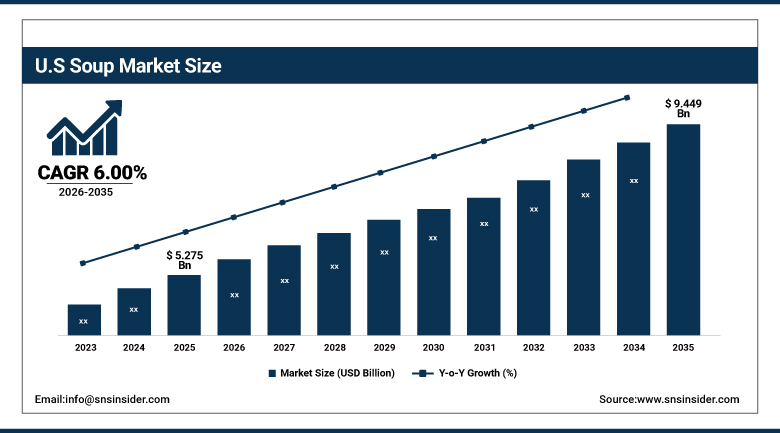
The U.S. Soup Market was valued at USD 5.275 Billion in 2025 and is projected to reach USD 9.449 Billion by 2035, growing at a CAGR of 6.00% during 2026–2035.
Leading soup producers in the nation have been consistently expanding their product lines owing to the rising health awareness among consumers which leads them to opt for healthy soup variants and an increasing demand for convenience foods because of busy lifestyles. Innovation in products that offer a variety of flavors and dietary choices continues to support high levels of domestic demand for soup in the country.
US soup market size was valued at USD 3.0 Billion in 2025 and expected to reach USD 3.6 Billion by 2034, driven by increasing consumer health consciousness favoring nutrient-rich soup variants and escalating demand for convenience foods due to fast-paced lifestyles.
Soup Market Segment Analysis
-
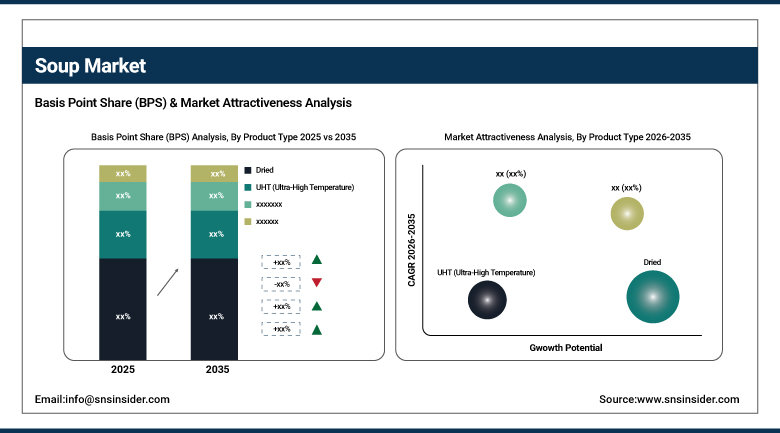
By Product Type, Dried dominated the Soup Market with a 59.50% share in 2025, while UHT (Ultra-High Temperature) is the fastest-growing product type segment with a CAGR of 7.20% from 2026–2035.
-
By Category, Vegetarian dominated the Soup Market with a 53.59% share in 2025, while Vegetarian is also the fastest-growing category segment with a CAGR of 2.06% from 2026–2035.
-
By Distribution Channel, Supermarkets/Hypermarkets dominated the Soup Market with a 56.90% share in 2025, while Online Retail is the fastest-growing distribution channel segment with a CAGR of 11.50% from 2026–2035.
-
By Packaging, Canned/Preserved dominated the Soup Market with a 44.90% share in 2025, while Pouches/Flexible Packaging is the fastest-growing packaging segment with a CAGR of 8.20% from 2026–2035.
By Product Type, Dried dominated the Soup Market, while UHT (Ultra-High Temperature) is the fastest-growing segment.
From a product perspective, the dried product segment had the highest market revenue share of 59.5% in 2023. Dried soups are the leading product category in terms of revenue due to their high shelf life, lower manufacturing costs, and easy cooking process, which makes them the easiest and most popular types of soups.
UHT (Ultra-High Temperature) segment will experience the highest CAGR over the forecast period. Growth of UHT soups comes from its longer-lasting components which do not need refrigeration and fit into the busy lifestyle of consumers while at the same time reducing food waste because companies produce these soups with minimal amounts of salts and sugars.
By Category, Vegetarian dominated the Soup Market and is also the fastest-growing segment.
The market share of vegetarian soup was at 53.59% in 2025, and it is also forecasted to grow with a CAGR of 2.06% till 2031, exceeding non-vegetarian soup due to the rise of flexitarian diets and plant-based nutrition beyond niche groups. Such an expansion of the segment is facilitated by various drivers such as increasing consciousness about the environment, ethical questions related to animals, health optimization, and technological improvements in plant proteins in terms of taste and texture similar to meat broths.
The coexistence of leadership in market share and CAGR of vegetarian soup makes it the leading segment in the category. However, the group of non-vegetarian soups, such as chicken, beef, and seafood, have their followers, especially the elderly population and cold regions, where such rich protein meals correspond to local cultural traditions.
By Distribution Channel, Supermarkets/Hypermarkets dominated the Soup Market, while Online Retail is the fastest-growing segment.
In 2025, supermarkets and hypermarkets held the largest market share of distribution channels with 56.9%. There are several types of soups offered in the supermarket chain in different brands catering to the nutritional needs of consumers in the supermarkets and hypermarkets, offering customers a huge variety of soups.
The Online Retail market segment is estimated to have a share of 9%-13% in 2025 and growing at a rate of 11.0%-12.0% CAGR due to factors such as digital grocer adoption, larger variety of products available, subscription options, direct-to-consumer offerings, and enhanced delivery systems in favor of the fast-growing segment.
By Packaging, Canned/Preserved dominated the Soup Market, while Pouches/Flexible Packaging is the fastest-growing segment.
Canned/preserved soup constitutes the largest share in 2025 with 44.9% of the total market share. Canned/preserved soups are processed soups that are cooked under high temperature and packed in cans/jars. This type of soups do not need refrigeration and can last for a long time and provide a fast and easy food choice that requires minimal efforts. These soups can be used in emergencies and by those people who don’t have cooking facilities.
The Pouches/Flexible Packaging category is anticipated to witness the fastest CAGR of 8.20% during 2026-2035. The increasing consumer demand for environmentally friendly and reusable soups packaging is responsible for the rapid growth of the pouches category.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.00% |
|
Europe |
United Kingdom |
27.60% |
|
Asia Pacific |
China |
44.60% |
|
Middle East & Africa |
UAE |
25.60% |
|
Latin America |
Brazil |
37.70% |
North America Soup Market Insights
North America held a 28%-32% share in 2025, growing at a CAGR of 5.5%-6.5%, supported by established packaged food consumption, convenience-driven lifestyles, premium product innovation, and demand for healthier formulations across the region.
The US was the leading country within the North America Soup Market in 2025, expanding at a CAGR of 5.3%-6.3%, supported by household convenience, premium soups, functional ingredients, and wider online grocery availability. Canada is contributing to regional growth through its own expanding packaged food retail sector.
Europe Soup Market Insights
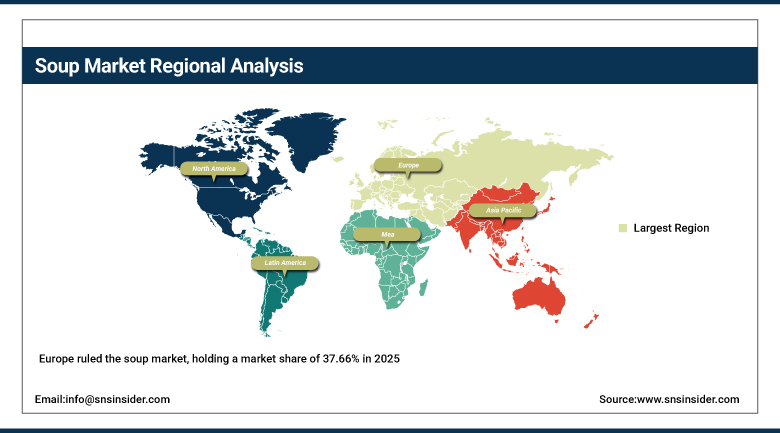
Europe ruled the soup market, holding a market share of 37.66% in 2025, owing to the long history of soup eating in the region, strong presence of soup manufacturing companies, and the existing network of packaged foods retails across the member nations.
It is expected that the United Kingdom will have a strong growth rate in the coming years due to the presence of soup manufacturing companies in the country such as Baxters Food Group and New Covent Garden Soup Co. Germany and France are also contributing to the growth in the market.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Soup Market Insights
Asia Pacific held a 25%-29% share in 2025, growing at a CAGR of 8.0%-9.0%, supported by urbanization, expanding middle-class populations, convenience food adoption, modern retail development, and increasing availability of international and localized soup formats.
China is one of the main growth drivers in the Asia Pacific Soup Market, owing to its massive consumer base and rapidly expanding modern retail infrastructure. India and Japan are also contributing to regional growth through expanding packaged food manufacturing capacity and rising consumer interest in convenient, ready-to-eat meal solutions.
Middle East & Africa and Latin America Soup Market Insights
Middle East & Africa and Latin American regions are gradually expanding soup market participation as packaged food retail infrastructure develops across both regions, supported by increasing regional consumer awareness of convenient meal solution benefits.
Brazil is set to be a prominent Latin American market fueled by growing packaged food manufacturing capacity and rising consumer demand for convenient, ready-to-eat meal solutions. The Middle East & Africa region has UAE and Saudi Arabia investing in modern retail infrastructure that is expanding access to premium soup product categories across their growing packaged food sectors.
Growth Drivers: Rising convenience food demand and healthier formulation innovation driving market growth
Growing consumer demand for convenient, ready-to-eat packaged food products is primarily driving the Soup Market. The rising demand for soups with clean ingredients in reusable and sustainable packaging solutions, shifting consumer preferences toward ready-to-eat food products, and increasing adoption of vegan and vegetarian dietary habits among individuals continue to support sustained market expansion across increasingly diverse global consumer markets.
Increasing consumer health consciousness favoring nutrient-rich soup variants, escalating demand for convenience foods due to fast-paced lifestyles, and a surge in product innovation delivering a wide array of flavors and dietary options continue to drive market growth. Growing urbanization and rising dual-income households encouraging higher adoption of ready-made soups, supported by improved supply chains and strong retail presence, are further supporting demand across the forecast period.
Restraints: Sodium content concerns and fresh alternative competition limiting market expansion
A major limitation in terms of market development is the increasing fear among consumers regarding the sodium level in packaged soups, limiting the growth of the market among health-conscious consumers who prefer the use of low-sodium fresh or homemade options.
Another limitation for the packaged soup category growth is the presence of competing categories such as fresh soups or homemade soup preparations, especially among consumers who have the ability to access fresh vegetables and can spare some time for preparing their meals. This includes the changing prices of vegetables, meat, and packaging commodities.
Opportunities: Expansion of plant-based innovation and premium chilled formats creating new growth avenues
Vegetarian soup's continued outpacing of non-vegetarian offerings as flexitarian diets become mainstream represents a substantial market opportunity for manufacturers capable of developing differentiated plant-protein soup formulations delivering taste and texture comparable to meat-based broths.
There is a considerable growth opportunity in the continued expansion of chilled soup segments resonating with health-conscious consumers willing to pay a premium for fresh quality. The expansion of e-commerce distribution and modern retail infrastructure in emerging markets across Asia Pacific and Latin America is likely to unlock substantial new demand throughout the forecast period.
Recent Developments
-
2025: Campbell Soup Company launched an updated reduced-sodium condensed soup product line, offering health-conscious consumers a lower-sodium alternative within its established condensed soup portfolio.
-
2025: Baxters Food Group expanded its chilled soup production capacity, strengthening its ability to supply growing premium retail market demand for fresh, minimally processed soup products.
-
2026: Amy's Kitchen launched a new organic plant-based soup range, targeting health-conscious consumers seeking certified organic, vegetarian, and vegan soup formulations.
-
2026: Unilever, through its Knorr brand, expanded its instant soup manufacturing capacity for emerging Asia Pacific markets, strengthening its ability to supply growing regional convenience food demand.
Soup Companies are:
-
Campbell Soup Company
-
Nestlé S.A.
-
General Mills, Inc.
-
Unilever plc (Knorr)
-
Baxters Food Group Limited
-
The Kraft Heinz Company
-
Conagra Brands, Inc.
-
New Covent Garden Soup Co. Ltd.
-
Yorkshire Provender
-
McCormick & Company, Incorporated
-
Ajinomoto Co., Inc.
-
Premier Foods plc
-
Symington's Ltd.
-
Kraft Heinz (Wattie's)
-
House Foods Group Inc.
-
Hormel Foods Corporation
-
Blount Fine Foods Corp.
-
Progresso (General Mills)
Soup Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 21.40 Billion |
| Market Size by 2035 | USD 38.33 Billion |
| CAGR | CAGR of 6.00% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Dried, UHT (Ultra-High Temperature)) • By Category (Vegetarian, Non-Vegetarian) • By Distribution Channel (Supermarkets/Hypermarkets, Online Retail) • By Packaging (Canned/Preserved, Pouches/Flexible Packaging) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Campbell Soup Company, Nestlé S.A., General Mills, Inc., Unilever plc (Knorr), Baxters Food Group Limited, Amy's Kitchen, Inc., The Kraft Heinz Company, Conagra Brands, Inc., New Covent Garden Soup Co. Ltd., Yorkshire Provender, McCormick & Company, Incorporated, Ajinomoto Co., Inc., Premier Foods plc, Symington's Ltd., Bonduelle Group, Kraft Heinz (Wattie's), House Foods Group Inc., Hormel Foods Corporation, Blount Fine Foods Corp., Progresso (General Mills) |
Frequently Asked Questions
Key players in the Soup Market include Campbell Soup Company, Nestlé S.A., General Mills, Inc., and Unilever plc (Knorr) among others.
Key opportunities include premium soups, plant-based formulations, convenient packaging, clean-label ingredients, and online retail expansion.
The market is driven by growing consumer demand for convenient, ready-to-eat packaged food products.
The Dried segment dominated the Soup Market, accounting for approximately 59.50% market share.
The Europe region dominated the Soup Market in 2025 with a market share of 37.66%.
