
Squash Drinks Market Report Scope & Overview:
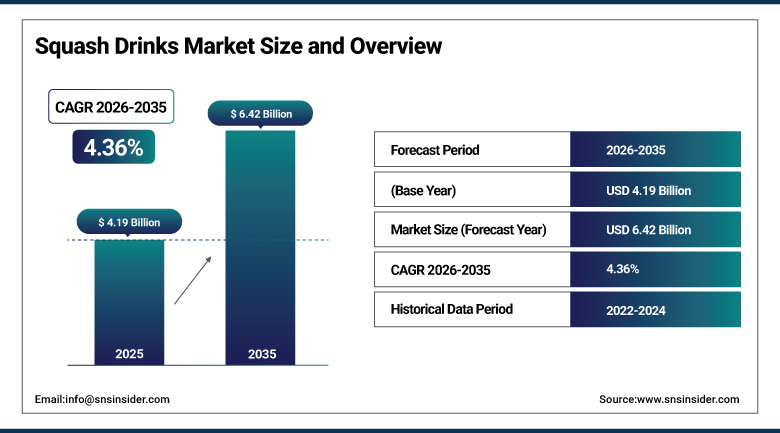
The Squash Drinks Market was valued at USD 4.19 Billion in 2025 and is expected to reach USD 6.42 Billion by 2035, growing at a CAGR of 4.36% from 2026 to 2035.
The Squash Drinks Market is experiencing a steady growth rate due to value consciousness, experimentation with taste preferences, and the trend shifting away from carbonated soft drinks towards customized hydration products. Squash drink is a concentrated base for a beverage, normally flavored with fruits and diluted with water before drinking. The squash drink comes in between ready-to-drink juice beverages, cordials, syrups, and powdered beverages. Also, growth in the market is being enhanced by healthy living practices, increased demand for beverages, introduction of new flavors, development of distribution networks, and competition among companies to reduce sugar content, use natural flavors, provide shelf-stable packaging, and make claims that pass regulation process.
Squash drinks are consumed by people on a large scale to help fulfill nutrient requirements including Vitamin C and minerals, reflecting the category's positioning as both a flavorful hydration format and a source of nutritional value across households worldwide seeking convenient, customizable beverage options.
To Get more information Squash Drinks Market - Request Free Sample Report
Squash Drinks Market Trends
-
Rising manufacturer competitive focus on sugar reduction, natural flavor systems, and clean-label claims is reshaping formulation priorities across the squash drinks category.
-
Growing demand for customizable hydration formats is driving continued shift away from carbonated soft drinks toward concentrate-based beverages offering household portion and dilution flexibility.
-
Increasing flavor experimentation, including mixed berry and exotic fruit variants, is expanding product variety beyond traditional orange and blackcurrant flavor profiles.
-
Expanding shelf-stable packaging innovation, including pouches and convenient dilution ratio formats, is improving product accessibility and household storage convenience.
-
Strategic partnerships among squash drink manufacturers, retailers, and organic fruit suppliers are supporting development of increasingly natural, sustainably sourced concentrate beverage portfolios.
U.S. Squash Drinks Market Outlook
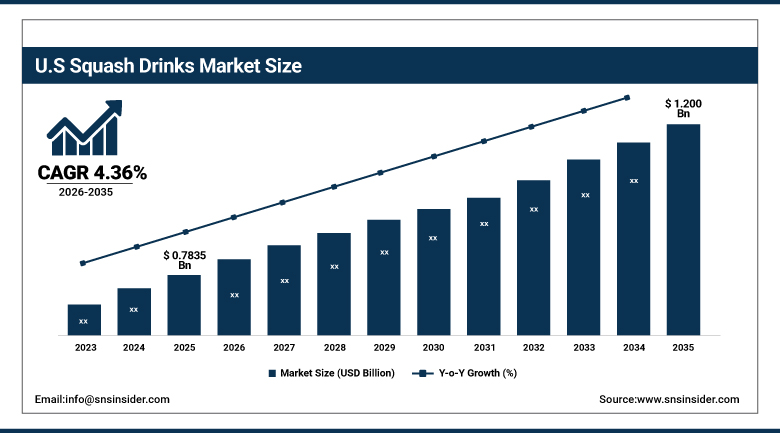
The U.S. Squash Drinks Market was valued at USD 0.7835 Billion in 2025 and is projected to reach USD 1.200 Billion by 2035, growing at a CAGR of 4.36% during 2026–2035.
The major players within the beverages industry in the nation have seen an increase in production of squash drinks, spurred on by household value considerations and the ongoing trend of movement away from carbonated drinks towards customizable hydration options. Rising interest in reduced sugar content, natural flavors and "clean label" formulations, as well as growing retail distribution channels, further reinforces ongoing domestic demand for squash drinks.
Within North America, squash drinks face competition from ready-to-drink juices and powdered soft drinks, influenced by factors such as household value consideration, experimentation with flavors and movement away from carbonated drinks towards customizable hydration.
Squash Drinks Market Segment Analysis
-
By Flavor Type, Orange dominated the Squash Drinks Market with a 41.70% share in 2025, while Mixed Berry is the fastest-growing flavor type segment with a CAGR of 5.71% from 2026–2035.
-
By Sugar Content, Added-Sugar dominated the Squash Drinks Market with a 76.15% share in 2025, while No-Added-Sugar is the fastest-growing sugar content segment with a CAGR of 5.27% from 2026–2035.
-
By Distribution Channel, Hypermarkets/Supermarkets dominated the Squash Drinks Market with a 46.30% share in 2025, while Online Retail is the fastest-growing distribution channel segment with a CAGR of 8.60% from 2026–2035.
-
By Packaging Type, Bottles dominated the Squash Drinks Market with a 58.60% share in 2025, while Pouches is the fastest-growing packaging type segment with a CAGR of 6.80% from 2026–2035.
By Flavor Type, Orange dominated the Squash Drinks Market, while Mixed Berry is the fastest-growing segment.
Orange Squash holds the largest market share at 41.70%. The orange flavor category is still leading due to high consumer awareness and versatility, and is the conventional squash flavor that has remained the backbone of household buying behavior for most of the squash drinks consumed globally.
Mixed berry flavors will have the highest growth rate in the global squash drinks market with an anticipated CAGR of 5.71% during the forecast period ending 2031. The increased interest among consumers in different flavors rather than just citrus flavors is fueling the growth of this flavor category in the market.
By Sugar Content, Added-Sugar dominated the Squash Drinks Market, while No-Added-Sugar is the fastest-growing segment.
Sugar-added products dominated the global squash drinks market, occupying 76.15% of its share in 2025. Such high shares are explained by the longstanding preferences of consumers towards the classic taste of the products and their widespread availability through various channels of retail, being affordable and familiar to consumers of any age, despite an increasing attention to health and wellness issues.
The no-added-sugar segment will demonstrate the fastest growth during 2031, reaching 5.27% of CAGR during the forecast period. The growing awareness of consumers about the negative impact of excessive sugar intake encourages them to buy more healthy beverages, which positively influences the growth of this segment.
By Distribution Channel, Hypermarkets/Supermarkets dominated the Squash Drinks Market, while Online Retail is the fastest-growing segment.
In terms of distribution channel, hypermarkets or supermarkets segment commands a 46.30% share in the squash drink market in 2025. Hypermarkets and supermarkets remain the dominant distribution channel owing to their broad product assortment spanning conventional, premium, and specialty squash drink varieties, offering consumers convenient, single-trip access across the majority of household purchasing occasions worldwide.
The Online Retail segment is expected to witness the fastest CAGR of 8.60% during the forecast period 2026-2035. Expanding distribution channels and growing consumer comfort with purchasing shelf-stable grocery items online are driving rising online squash drink sales, particularly for bulk purchasing and recurring household pantry replenishment.
By Packaging Type, Bottles dominated the Squash Drinks Market, while Pouches is the fastest-growing segment.
The Bottles segment dominated the Squash Drinks Market owing to their established, widely recognized packaging format offering resealability and convenient household storage, representing the standard packaging category across the majority of squash drink retail and household consumption applications worldwide.
The Pouches segment is expected to register the fastest CAGR of 6.80% during the forecast period 2026-2035. Growing manufacturer and consumer preference for lightweight, cost-effective, and space-efficient packaging formats is driving rising pouch adoption, particularly for value-oriented and refill-sized squash drink products seeking to reduce packaging costs and environmental footprint.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.00% |
|
Europe |
United Kingdom |
27.60% |
|
Asia Pacific |
China |
44.60% |
|
Middle East & Africa |
UAE |
26.80% |
|
Latin America |
Brazil |
37.70% |
North America Squash Drinks Market Insights
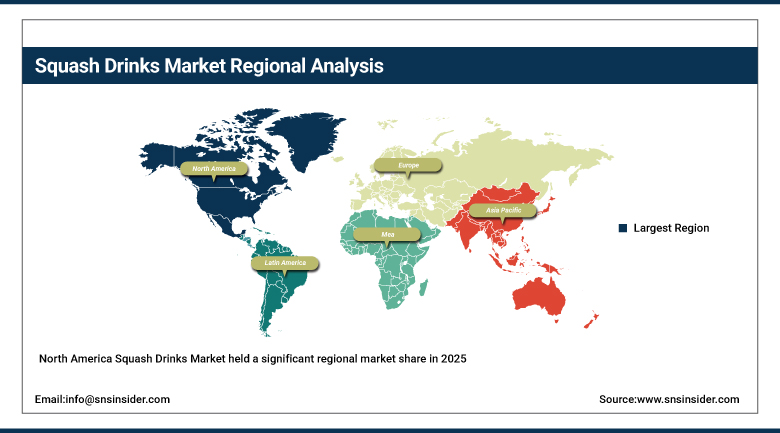
The North America Squash Drinks Market held a significant regional market share in 2025 owing to household value seeking, flavor experimentation, and the continued shift from carbonated soft drinks toward customizable hydration formats across the region.
The US was the leading country within the North America Squash Drinks Market in 2025, driven by growing consumer interest in sugar reduction, natural flavor systems, and clean-label claims. Canada is contributing to regional growth through its own expanding retail distribution and growing consumer interest in customizable, dilution-based beverage formats.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Squash Drinks Market Insights
Europe Squash Drinks Market is one of the key contributors in 2025. The factors behind Europe becoming a major contributor include the existing cultural background of the consumption of squash drinks, leading brands present in the region, and increasing demand among consumers for natural and reduced sugar beverages.
United Kingdom is one of the leading markets in Europe due to the existing cultural background of consumption of squash drinks and the presence of leading brands including Nichols plc's Vimto and Suntory's Ribena and Robinsons. Other countries including Germany and France are contributing towards market growth through increased distribution of squash drinks.
Asia Pacific Squash Drinks Market Insights
The Asia Pacific region is anticipated to hold a significant share of the squash drinks market, driven by global squash drink consumption projected to expand steadily across the region's major and emerging economies.
China is capturing a 7.6% growth rate and India is accounting for a 7.0% CAGR from 2025 to 2035, positioning both countries as key growth drivers in the Asia Pacific Squash Drinks Market. Growing disposable incomes, expanding modern retail infrastructure, and rising demand for natural fruit extract combinations continue to support regional market momentum.
Middle East & Africa and Latin America Squash Drinks Market Insights
Middle East & Africa is turning out to be an interesting growth opportunity for squash drinks, driven by developments in the retail infrastructure and increasing consumer demand for customized beverages, and Latin American regions are increasing their market presence gradually.
Brazil will be a major market in Latin America driven by the development in beverage production facilities and increasing consumer demand for concentrate-based convenient flavors. Middle East & Africa region is witnessing investments in modern retail infrastructure in countries like UAE and Saudi Arabia to make available the premium and natural squash drinks.
Market Dynamics
Growth Drivers: Rising health-conscious trends and flavor innovation demand driving market growth
Health-conscious trends, rising demand for natural beverages, innovative flavors, and expanding distribution channels are among the primary drivers of the Squash Drinks Market. Household value seeking, flavor experimentation, and the continued shift from carbonated soft drinks toward customizable hydration formats continue to support sustained market demand across increasingly diverse global consumer markets.
As modern consumers balance busy schedules with heightened awareness of nutrition, brands have responded with formulations that offer convenience without compromising on naturalness or taste. Natural, no-sugar squash-based products providing numerous nutritional benefits, growing demand from diabetic consumers seeking sugar-free options, and manufacturers' focus on sugar reduction and clean-label claims are further supporting demand across the forecast period.
Restraints: Substitute beverage competition and regulatory scrutiny limiting market expansion
One of the key challenges in the development of the market includes an increase in the competitive environment from ready-to-drink juices and other beverage types which will continue to be a problem in the growth of the market since people will have to choose between concentrates which have to be diluted and instant drinks.
Furthermore, another challenge will include an increase in regulation in terms of sugar levels in products. This means that companies will be forced to ensure that they formulate their products in such a way that they meet these requirements.
Opportunities: Expansion of sugar-free formulations and functional ingredient integration creating new growth avenues
Increasing popularity of functional drinks incorporating added vitamins and minerals represents a substantial market opportunity, as manufacturers increasingly develop squash drink formulations offering nutritional value beyond basic hydration and flavor.
There is a considerable growth opportunity in the continued development of no-added-sugar squash formulations addressing growing health-conscious consumer demand. The expansion of retail distribution and rising disposable incomes in emerging markets across Asia Pacific and the Middle East is likely to unlock substantial new demand throughout the forecast period.
Recent Developments:
-
2024: Nestlé launched a new organic squash drink line targeting health-conscious consumers, reflecting a strategic shift toward clean-label, plant-based beverages meeting rising demand for transparency and natural ingredients.
-
2024: PepsiCo announced a strategic partnership with a regional organic fruit supplier to enhance its supply chain sustainability and product authenticity, aiming to secure high-quality raw materials and reduce environmental impact.
-
2025: Britvic PLC expanded its Robinsons no-added-sugar squash product line for European retail markets, targeting health-conscious consumers seeking reduced-sugar hydration options.
-
2026: Suntory Beverage & Food expanded its Ribena concentrate production capacity, strengthening its ability to supply growing export market demand for premium fruit squash concentrate products.
Squash Drinks Market key players are:
-
Unilever plc
-
Suntory Beverage & Food Limited
-
Nichols plc (Vimto)
-
Britvic PLC (Robinsons)
-
J Sainsbury Plc
-
Tesco PLC
-
Keurig Dr Pepper Inc.
-
PepsiCo, Inc.
-
The Coca-Cola Company
-
Nestlé S.A.
-
Refresco Group B.V.
-
Princes Group Limited
-
A.G. Barr p.l.c.
-
Rubicon Drinks (A.G. Barr)
-
Hindustan Unilever Limited (Kissan)
-
Dabur India Limited (Real)
-
Parle Agro Pvt. Ltd.
-
Rasna Private Limited
-
Dilmah Ceylon Tea Company
-
Frugal Foods Pvt. Ltd.
Squash Drinks Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 4.19 Billion |
| Market Size by 2035 | USD 6.42 Billion |
| CAGR | CAGR of 4.36% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Flavor Type (Orange, Mixed Berry, Blackcurrant, Others) • By Sugar Content (Added-Sugar, No-Added-Sugar) • By Distribution Channel (Hypermarkets/Supermarkets, Online Retail) • By Packaging Type (Bottles, Pouches) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Unilever plc, Suntory Beverage & Food Limited, Nichols plc (Vimto), Britvic PLC (Robinsons), J Sainsbury Plc, Tesco PLC, Keurig Dr Pepper Inc., PepsiCo, Inc., The Coca-Cola Company, Nestlé S.A., Refresco Group B.V., Princes Group Limited, A.G. Barr p.l.c., Rubicon Drinks (A.G. Barr), Hindustan Unilever Limited (Kissan), Dabur India Limited (Real), Parle Agro Pvt. Ltd., Rasna Private Limited, Dilmah Ceylon Tea Company, Frugal Foods Pvt. Ltd. |
Frequently Asked Questions
Key players in the Detox Drinks Market include Unilever plc, Suntory Beverage & Food Limited, Nichols plc (Vimto), Britvic PLC (Robinsons), and J Sainsbury Plc among others.
Key opportunities include expanding premium flavors, healthier formulations, functional ingredients, and convenient ready-to-drink formats.
The market is driven by health-conscious trends, rising demand for natural beverages, innovative flavors, and expanding distribution channels.
The Orange segment dominated the Squash Drinks Market, accounting for approximately 41.70% market share.
The Asia Pacific region held a significant share of the Squash Drinks Market in 2025, driven by strong growth in China and India.
