
Sugar Alcohol Market Report Scope & Overview:
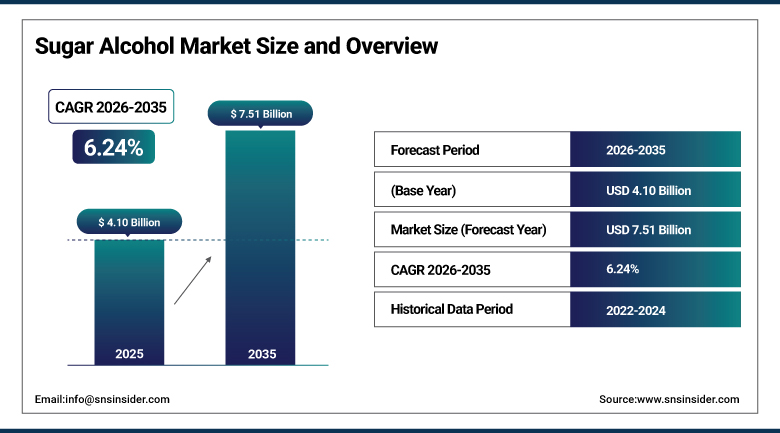
The Sugar Alcohol Market was valued at USD 4.10 Billion in 2025 and is expected to reach USD 7.51 Billion by 2035, growing at a CAGR of 6.24% from 2026 to 2035.
The Sugar Alcohol Market is witnessing rapid growth due to the change in behavior of consumers towards health consciousness in their food choices, in addition to the increased cases of diabetes across the globe along with regulation of sugar content in various food products. Sugar alcohols or polyols are sweeteners that come from carbohydrates as a result of hydrogenation of sugars, providing a sweetener option with low calories and glycemic index which are extensively used in food, beverage, and pharmaceutical industries. In addition, the market is driven by increased demand for low-carb diets, obesity, diabetes, and sugar-free foods.
In the global market for sugar alcohols, over 1.4 million metric tons of sugar alcohols are consumed annually, where over 60% of this amount is used in food and pharmaceutical industries globally, while in the United States, sugar alcohols are responsible for widespread applications in chewing gums and oral care.
To Get more information Sugar Alcohol Market - Request Free Sample Report
Sugar Alcohol Market Trends
-
Rising erythritol adoption is being driven by its zero-calorie profile and superior digestive tolerance compared to other sugar alcohols, which can cause gastrointestinal discomfort at higher consumption levels.
-
Growing regulatory pressure on sugar content across major food categories is accelerating manufacturer reformulation toward sugar alcohol-based sweetening solutions in mainstream packaged food and beverage products.
-
Increasing research into alternative starch sources beyond corn is expanding potato and wheat-based sugar alcohol production, diversifying raw material supply chains and reducing dependency concentration.
-
Expanding pharmaceutical excipient applications are driving demand for high-purity sugar alcohols suited to tablet formulation, oral care products, and controlled-release drug delivery systems.
-
Strategic partnerships among sugar alcohol producers, food manufacturers, and pharmaceutical companies are supporting development of increasingly diverse, application-specific polyol ingredient solutions.
U.S. Sugar Alcohol Market Outlook
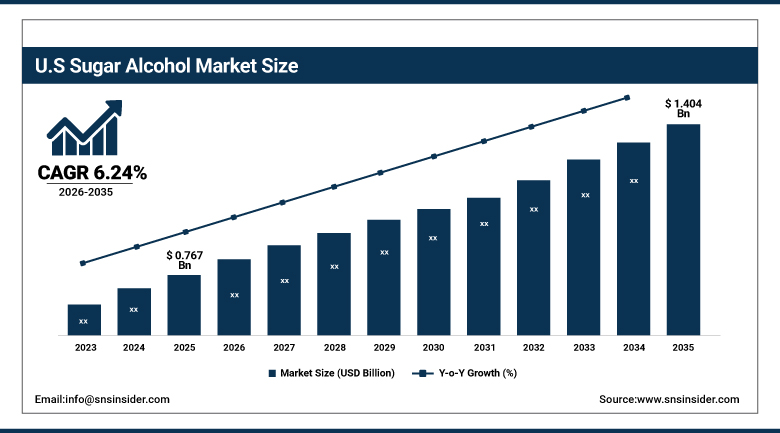
The U.S. Sugar Alcohol Market was valued at USD 0.767 Billion in 2025 and is projected to reach USD 1.404 Billion by 2035, growing at a CAGR of 6.24% during 2026–2035.
The country's leading players in foods and pharmaceuticals manufacturing continue to drive sugar alcohol consumption due to the high domestic consumption of sugar-free and reduced calorie foods within chewing gum, oral care, and confectionary products. The increasing consumer inclination towards low carbohydrate diets, coupled with an increasing incidence of diabetes, in addition to growing uses of sugar alcohol in pharmaceuticals where stable non-hygroscopic sweeteners are required, have continued to drive high domestic consumption of sugar alcohols among the diverse range of the country's food and pharmaceuticals manufacturing companies.
Within the United States, the market of sugar alcohols drives wide consumption within chewing gums, oral care, and sugar-free foods, owing to the country's well-developed confectionery and personal care manufacturing base.
Sugar Alcohol Market Segment Analysis
-
By Type, Sorbitol dominated the Sugar Alcohol Market with a 27.00% share in 2025, while Erythritol is the fastest-growing type segment with a CAGR of 7.43% from 2026–2035.
-
By Source, Corn dominated the Sugar Alcohol Market with a 58.60% share in 2025, while Potato is the fastest-growing source segment with a CAGR of 7.60% from 2026–2035.
-
By Form, Powder & Crystal dominated the Sugar Alcohol Market with a 65.50% share in 2025, while Syrup is the fastest-growing form segment with a CAGR of 7.20% from 2026–2035.
-
By Application, Food & Beverage dominated the Sugar Alcohol Market with a 68.90% share in 2025, while Pharmaceuticals is the fastest-growing application segment with a CAGR of 7.80% from 2026–2035.
By Type, Sorbitol dominated the Sugar Alcohol Market, while Erythritol is the fastest-growing segment.
Sorbitol is a widely used sugar alcohol and holds a dominant position in the market, accounting for approximately 27.00% of total sugar alcohol revenue. Sorbitol remains the dominant type category owing to its extensive established use across chewing gum, oral care formulations, confectionery, and pharmaceutical excipient applications, supported by well-developed corn-based production infrastructure across major manufacturing regions worldwide.
Erythritol is forecast to grow at 7.43% CAGR during the forecast period on account of its zero-calorie profile and digestive tolerance. Growing consumer preference for sugar alcohols that avoid the gastrointestinal discomfort associated with higher-dosage polyol consumption is driving rapid erythritol adoption, as manufacturers increasingly favor this well-tolerated sweetener across sugar-free beverage and confectionery reformulation.
By Source, Corn dominated the Sugar Alcohol Market, while Potato is the fastest-growing segment.
The Corn category had a huge share of the market in terms of revenues owing to the large availability of corn starch as well as its efficient conversion to sugar alcohols including sorbitol and maltitol. Sugar alcohols made from corn are favored in food and drink manufacturing because of their high-quality, large-scale manufacturing capability and easy integration thanks to the reliable supply chain available in producing countries.
The Potato category is projected to be the fastest-growing CAGR category, registering 7.60%, owing to the research going on in the area of starch sources and the rising need for non-corn sugar alcohols. Manufacturers are increasingly interested in sources of raw material other than corn leading to increased investments in making sugar alcohols from potatoes.
By Form, Powder & Crystal dominated the Sugar Alcohol Market, while Syrup is the fastest-growing segment.
Powder and Crystal Segment is the market leader in terms of the highest revenue share of 65.50% on account of extensive usage in confectionery, bakery, and beverages due to easy handling, accurate dosing, and quality consistency. This form of sugar alcohol is highly soluble, offers a uniform particle size, and increases sweetness perception, thereby making it best suitable for large scale manufacturing and processing.
Syrup segment is estimated to register the highest CAGR of 7.20%. Increasing demand for syrup form of sugar alcohol that can be used for the manufacturing of beverages and some of the confectionery products owing to their instant solubility property is expected to fuel the syrup segment growth.
By Application, Food & Beverage dominated the Sugar Alcohol Market, while Pharmaceuticals is the fastest-growing segment.
The Food & Beverage segment dominated the Sugar Alcohol Market owing to sugar alcohols' extensive use across sugar-free confectionery, chewing gum, baked goods, and beverage formulations, representing the largest and most established application category driving overall sugar alcohol demand as manufacturers continue reformulating products to reduce sugar content amid tightening regulatory requirements.
The Pharmaceuticals segment is expected to register the fastest CAGR of 7.80% during the forecast period 2026-2035. Growing use of sugar alcohols as stable, non-hygroscopic pharmaceutical excipients supporting tablet formulation, oral care products, and controlled-release drug delivery systems is driving strong segment growth as pharmaceutical formulators increasingly rely on sugar alcohols' versatile functional properties.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.00% |
|
Europe |
Germany |
27.60% |
|
Asia Pacific |
China |
44.60% |
|
Middle East & Africa |
UAE |
25.60% |
|
Latin America |
Brazil |
37.70% |
North America Sugar Alcohol Market Insights
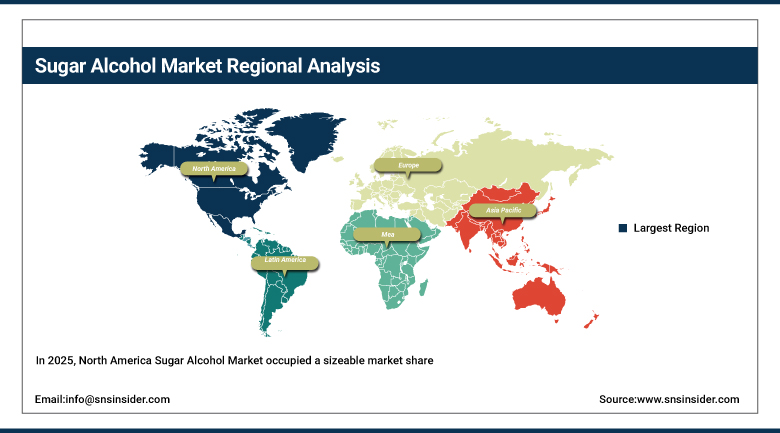
In 2025, North America Sugar Alcohol Market occupied a sizeable market share in the region due to high domestic demand for sugar free and calorie-reduced products in chewing gum, oral care, and confectionery segments backed up by developed manufacturing industry of food and drugs.
In 2025, the USA had become the dominant country in North America Sugar Alcohol Market due to the presence of advanced sugar-free foods and personal care products manufacturing industry. Canada has been making its contribution to the growth of the region through developing food processing industry and increasing popularity of low calorie sweeteners.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Sugar Alcohol Market Insights
In 2023, Europe accounted for roughly 32% share of global sugar alcohol consumption by volume, driven by the region's strong pharmaceutical excipient manufacturing base, growing potato-based sugar alcohol production investment, and stringent regulatory frameworks promoting sugar reduction across food categories.
Germany is one of the major markets in Europe owing to its strong pharmaceutical excipient manufacturing base and growing consumer demand for sugar-reduced food products. Other countries such as France and the Netherlands, benefiting from established potato starch processing infrastructure, are also contributing to market growth through expanding non-corn sugar alcohol production.
Asia Pacific Sugar Alcohol Market Insights
The Asia Pacific Sugar Alcohol Market is expected to witness the fastest growth rate during the forecast period 2026-2035. The market growth is driven by rising diabetes prevalence, growing consumer health consciousness, and expanding confectionery and sugar-reduced bakery manufacturing capacity across the region's major economies.
China is one of the main growth drivers in the Asia Pacific Sugar Alcohol Market, boosted by confectionery and sugar-reduced bakery growth alongside expanding domestic corn processing infrastructure. India is also contributing significantly to regional growth, led by rising low-calorie food consumption and growing domestic sugar alcohol manufacturing investment.
Middle East & Africa and Latin America Sugar Alcohol Market Insights
The Middle East and Africa is projected to post a strong CAGR through the forecast period as urbanization and diabetes awareness rise, driving growing regional demand for sugar-free and reduced-calorie food and personal care products.
Brazil is set to be a prominent Latin American market, propelled by sugar-free product adoption in confectionery and growing domestic food processing capacity. The Middle East & Africa region has UAE and Saudi Arabia investing in modern food processing infrastructure that is gradually increasing demand for sugar alcohols across their expanding sugar-free and diabetic-friendly product categories.
Market Dynamics
Growth Drivers: Rising health consciousness and diabetes prevalence driving market growth
Fundamental changes in consumer behavior, particularly the growing emphasis on health-conscious food choices, coupled with the increasing prevalence of diabetes worldwide, are among the primary drivers of the Sugar Alcohol Market. Regulatory bodies implementing stricter controls on sugar content across various food categories continue to compel manufacturers to reformulate products with low-calorie, low-glycemic sugar alcohol alternatives, sustaining broad-based demand across food, beverage, and pharmaceutical applications.
The growing popularity of low-carb diets and rising concerns over obesity and diabetes continue to drive demand for sugar-free and reduced-calorie products. Increasing demand for low-carbohydrate options and growing health consciousness among consumers worldwide, combined with expanding pharmaceutical excipient applications and rising research into alternative starch sources beyond corn, are further supporting demand across the forecast period.
Restraints: Gastrointestinal tolerance concerns and raw material price volatility limiting market expansion
Another critical obstacle facing market expansion is the gastro-intestinal issues that come with the consumption of sugar alcohols at increased dosage levels, such as bloating, which may hinder market expansion despite the fact that the sugar alcohols have benefits such as low calorie and low glycemic value.
On the other hand, variations in the cost of corn and potato commodities owing to the cycles of agricultural output in various parts of the world continue to be a source of instability in terms of pricing for the sugar alcohol producers and subsequent manufacturers of food and pharmaceutical products who seek to enter into long-term agreements.
Opportunities: Expansion of alternative sourcing and pharmaceutical excipient demand creating new growth avenues
Increasing research on alternative starch sources and the rising demand for non-corn sugar alcohols represent substantial opportunities for manufacturers seeking to diversify raw material sourcing and reduce dependency on any single agricultural commodity, particularly as potato and wheat-based production investment continues expanding across European markets.
There is a considerable growth opportunity in the continued development of well-tolerated, zero-calorie sugar alcohols such as erythritol addressing consumer concerns around digestive comfort. The expansion of sugar-reduction regulatory initiatives and diabetes-focused product development in emerging markets across Asia Pacific and the Middle East is likely to unlock substantial new demand throughout the forecast period.
Recent Developments:
-
2025: Roquette Frères expanded its erythritol production capacity, strengthening its ability to supply growing clean-label, zero-calorie sweetener demand across food and beverage manufacturing customers.
-
2025: Cargill launched an updated maltitol product line designed for sugar-free confectionery applications, offering manufacturers improved sweetness profile and texture performance in reduced-calorie candy formulations.
-
2026: Archer Daniels Midland expanded its xylitol production capacity, targeting growing demand from oral care and chewing gum manufacturers seeking reliable, high-purity polyol supply.
-
2026: Ingredion introduced a new corn-derived sorbitol grade designed for pharmaceutical excipient applications, offering drug formulators enhanced stability and compressibility for tablet manufacturing.
Sugar Alcohol Market key players are:
-
Roquette Frères
-
Cargill, Incorporated
-
Archer Daniels Midland Company
-
Ingredion Incorporated
-
Tereos S.A.
-
IFF (DuPont de Nemours, Inc.)
-
Merck KGaA
-
SPI Pharma, Inc.
-
ZuChem, Inc.
-
Qingdao Bright Moon Seaweed Group Co., Ltd.
-
Zhejiang Huakang Pharmaceutical Co., Ltd.
-
Shandong Sanyuan Biotechnology Co., Ltd.
-
B Food Science Co., Ltd.
-
Foodchem International Corporation
-
Anhui Sunhere Pharmaceutical Excipients Co., Ltd.
-
Danisco A/S (IFF)
-
Novagreen Inc.
-
Mitsubishi Corporation Life Sciences Limited
-
BENEO GmbH (Südzucker AG)
-
Lonza Group AG
Sugar Alcohol Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 4.10 Billion |
| Market Size by 2035 | USD 7.51 Billion |
| CAGR | CAGR of 6.24% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Sorbitol, Xylitol, Mannitol, Maltitol, Erythritol, Others) • By Source (Corn, Potato, Wheat) • By Form (Powder & Crystal, Liquid, Syrup) • By Application (Food & Beverage, Pharmaceuticals, Personal Care & Cosmetics) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Roquette Frères, Cargill, Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Tereos S.A., IFF (DuPont de Nemours, Inc.), Merck KGaA, SPI Pharma, Inc., ZuChem, Inc., Qingdao Bright Moon Seaweed Group Co., Ltd., Zhejiang Huakang Pharmaceutical Co., Ltd., Shandong Sanyuan Biotechnology Co., Ltd., B Food Science Co., Ltd., Foodchem International Corporation, Anhui Sunhere Pharmaceutical Excipients Co., Ltd., Danisco A/S (IFF), Novagreen Inc., Mitsubishi Corporation Life Sciences Limited, BENEO GmbH (Südzucker AG), Lonza Group AG |

Frequently Asked Questions
The Sugar Alcohol Market is expected to grow at a CAGR of 6.24% from 2026 to 2035.
The Sugar Alcohol Market was valued at USD 4.10 Billion in 2025.
The market is driven by growing emphasis on health-conscious food choices, increasing diabetes prevalence, and regulatory bodies implementing stricter controls on sugar content.
The Sorbitol segment dominated the Sugar Alcohol Market, accounting for approximately 27.00% market share.
The Europe region dominated the Sugar Alcohol Market in 2023, accounting for roughly 32% share of global sugar alcohol consumption by volume.
