
Vehicle Electrification Market Report Scope & Overview:
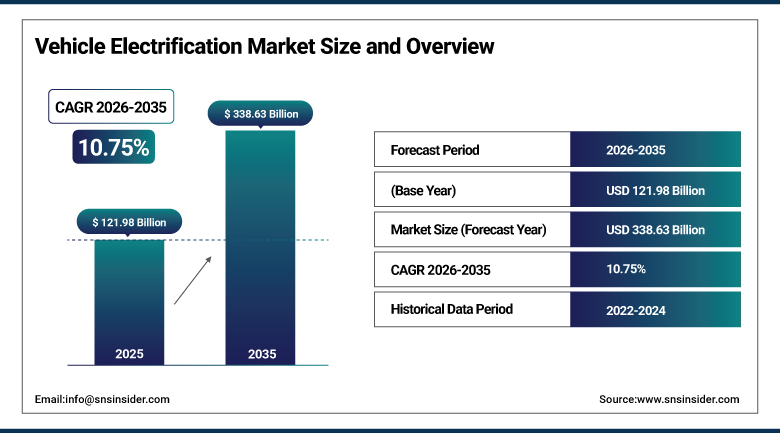
The Vehicle Electrification Market was valued at USD 121.98 Billion in 2025 and is expected to reach USD 338.63 Billion by 2035, growing at a CAGR of 10.75% from 2026-2035.
Vehicle electrification entails the use of electrical components rather than mechanical and hydraulic components within vehicles, from full electrical cars to hybrids and even ancillary components such as steering, pump, and compressor. Some advantages associated with vehicle electrification include energy efficiency, lower emissions, and ease of controlling of various components of the vehicle. The major forces that have driven this trend include tough emission standards, government incentives, lower prices of batteries, and creation of infrastructures for charging. As far as the suppliers of parts are concerned, they are gradually shifting to the utilization of high voltage systems, modular drives, and electrical architecture through software. The automakers employ different strategies including the production of both fully electric and hybrid cars.
In January 2025, Aptiv announced the planned separation of its Electrical Distribution Systems business into a standalone entity by March 2026. The move was intended to sharpen the company's focus on software-defined vehicle technologies and the power distribution systems that electric vehicles depend on.
To Get more information Vehicle Electrification Market - Request Free Sample Report
Vehicle Electrification Market Trends
- Rising adoption of 800V architectures enabling faster charging and higher efficiency.
- Growing use of 48V mild-hybrid systems as a cost-effective route to lower fuel consumption.
- Expanding integration of motors, inverters, and gearboxes into compact integrated drive modules.
- Increasing electrification of auxiliary systems including steering, pumps, and compressors.
- Rising interest in magnet-free motors that reduce dependence on rare earth materials.
- Growing partnerships between Tier-1 suppliers and automakers to co-develop electrical architectures.
U.S. Vehicle Electrification Market Overview
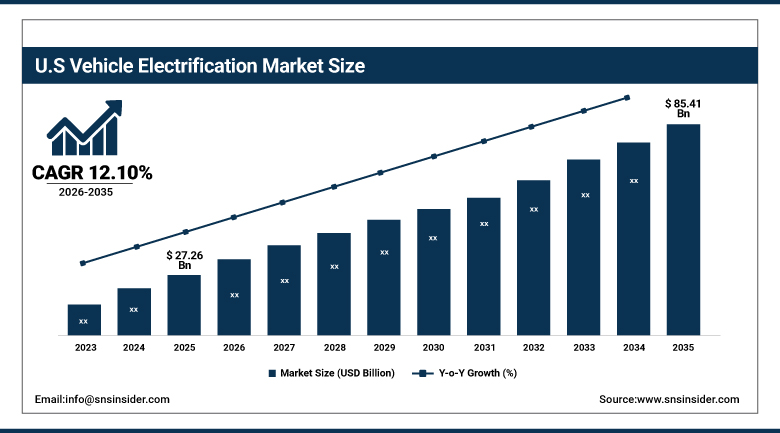
The U.S. Vehicle Electrification Market was valued at USD 27.26 Billion in 2025 and is expected to reach USD 85.41 Billion by 2035, growing at a CAGR of 12.10% from 2026-2035.
The U.S. Vehicle Electrification Market is driven by federal-state incentives, growing network of fast charging stations and strong commitment from manufacturers including Tesla, Ford, and General Motors. California holds a significant number of registrations in electric vehicles and others are following with zero emission standards and investments in charging infrastructure. Hybrids and plug-in hybrids are still favored by consumers who desire savings in terms of reduced fueling costs without limitations of range and, hence, support high demand for a variety of electrified systems. Leading suppliers based in the US are focusing their investments on integrated drive systems, inverters, battery management systems, among others, and are reorganizing their portfolios to focus more on electrified products.
In early 2025, BorgWarner made an acquisition of the eMotor business of Santroll that improved its capacity for the integrated drive module. The deal is inline with the Charging Forward 2027 strategy of BorgWarner that aims at exceeding 45% of sales from electrified products.
Vehicle Electrification Market Segment Analysis
- By Vehicle Type, the Passenger Cars segment dominated the market with a 68.40% share in 2025, while the Commercial Vehicles segment is the fastest growing with a CAGR of 13.05% during 2026-2035.
- By Propulsion Type, the Battery Electric Vehicles segment dominated the market with a 46.30% share in 2025, while the Plug-in Hybrid Electric Vehicles segment is the fastest growing with a CAGR of 12.80% during 2026-2035.
- By Component, the Batteries segment dominated the market with a 41.20% share in 2025, while the Power Electronics segment is the fastest growing with a CAGR of 12.20% during 2026-2035.
- By Voltage Architecture, the 400V segment dominated the market with a 54.70% share in 2025, while the 800V and Above segment is the fastest growing with a CAGR of 15.40% during 2026-2035.
By Vehicle Type, Passenger Cars Dominates the Market and Commercial Vehicles Grows Fastest
Passenger cars were the most popular vehicles in 2025. They comprise by far the largest share of the world’s vehicle manufacturing, and car manufacturers have been focusing their efforts on launching electric and hybrid models in this segment. Incentives from governments, increased diversity in model options, and improved charging infrastructure have been attracting private consumers to the purchase of electric cars, whereas emission standards have been set the toughest for passenger cars.
Commercial vehicles are projected to be the fastest-growing category over the forecast period. Fleet operators are electrifying delivery vans, buses, and trucks to lower total cost of ownership and meet city emission rules. Predictable routes and depot charging make electrification practical for many duty cycles, and manufacturers are launching light, medium, and heavy-duty electric models. Corporate sustainability commitments and low-emission zones add further pressure to convert fleets.
By Propulsion Type, Battery Electric Vehicles Dominates the Market and Plug-in Hybrid Electric Vehicles Grows Fastest
Battery electric vehicles dominated the market in 2025. They carry the highest content of electrified components, including large battery packs, traction motors, inverters, on-board chargers, and thermal systems, so each unit generates far more supplier revenue than a hybrid. Falling battery prices, longer range, and rapid growth of charging networks have made them the centre of many automaker strategies, especially in China and Europe.
Plug-in hybrid electric vehicles are expected to be the fastest-growing propulsion type over the forecast period. They combine a rechargeable battery with an engine, allowing zero-emission city driving and long-distance flexibility, which reduces range anxiety. Buyers in markets with patchy charging coverage find them a practical bridge to full electrification, and automakers are extending range with larger batteries. Range-extended designs are also gaining attention in trucks and large sport utility vehicles.
By Component, Batteries Dominates the Market and Power Electronics Grows Fastest
Batteries dominated the market in 2025. The battery pack is the most valuable single component in an electrified vehicle, and its share of vehicle cost keeps it at the top of supplier spending. Lithium-ion technology is the mainstream choice, with continued work on cell chemistry, energy density, and safety, while solid-state batteries are being developed for the longer term. Growth in vehicle volumes and larger pack sizes underpin consistent demand.
Power electronics are projected to be the fastest-growing component over the forecast period. Inverters, converters, on-board chargers, and controllers determine efficiency, charging speed, and driving performance, and they are being redesigned around silicon carbide and gallium nitride devices. The move to 800V systems and to integrated drive units raises content per vehicle, and suppliers are securing long-term awards for high-volume inverter programs.
By Voltage Architecture, 400V Dominates the Market and 800V and Above Grows Fastest
The 400V architecture dominated the market in 2025. It is the established standard across most current electric and plug-in hybrid platforms, supported by mature components, a broad supplier base, and lower vehicle cost. Charging infrastructure built over the past decade also largely assumes this voltage, which keeps it the practical choice for mass-market models where price and compatibility take priority over maximum charging speed.
The 800V and above architecture is expected to be the fastest-growing segment over the forecast period. Higher voltage reduces current for the same power, allowing thinner cables, lower heat losses, and much faster charging, which appeals to premium and performance buyers and to commercial fleets that need short stops. Automakers are extending 800V platforms to more models, and suppliers are developing inverters and chargers to match. Expanding ultra-fast charging networks strengthen this shift.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 |
|---|---|---|
|
Asia Pacific |
China |
52.60% |
|
North America |
United States |
89.40% |
|
Europe |
Germany |
27.30% |
|
Latin America |
Brazil |
48.20% |
|
Middle East & Africa |
United Arab Emirates |
19.80% |
Asia Pacific Vehicle Electrification Market Insights
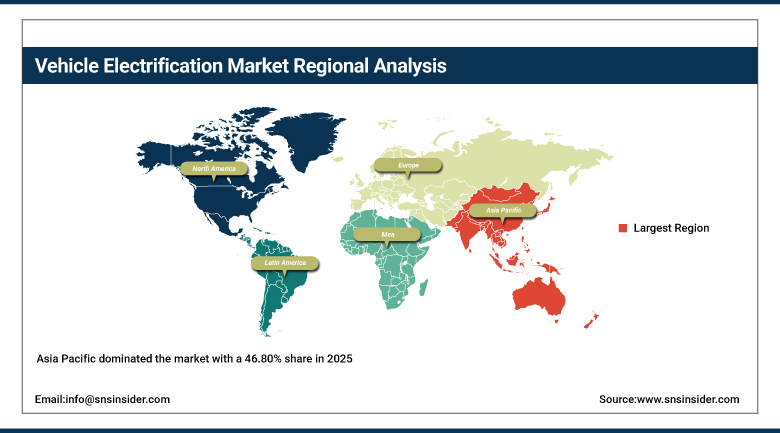
Asia Pacific dominated the market with a 46.80% share in 2025. The region is home to the world’s biggest electric car manufacturing center, most comprehensive battery supply chain, and supportive policies, where China is the biggest market in terms of countries. Consumers have shown considerable readiness for EVs, there is rapid development of charging infrastructure, and domestic automakers produce a variety of electric vehicles at affordable costs.
Japanese companies bring innovative technology for hybrids and power electronics; South Korean players contribute in batteries and components. India is seen to develop into a promising market with support for electric two-wheelers, three-wheelers, and cars provided by incentives and domestic production initiatives.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Vehicle Electrification Market Insights
North America is projected to be the fastest-growing region, registering a CAGR of 12.10% during 2026-2035. Government encouragement programs, investments in charging stations, and initiatives from major automobile companies are hastening their adoption. North America has a large percentage of regional sales of electric cars, and governments with emission-free vehicles have been making electric vehicles mainstream.
Canada boosts demand via federal and provincial sales targets and incentives, while Mexico acts as a major manufacturer of electric cars and components. Investments from suppliers in drive modules, inverters, and battery systems have also been rising thanks to localization of supply chain. This makes the region likely to experience growth higher than that of the global market.
Europe Vehicle Electrification Market Insights
Europe holds a significant share of the global market, shaped by coordinated policy, strict carbon dioxide rules for new vehicles, and plans to phase out internal combustion engines. Germany anchors regional demand, with Volkswagen and BMW among the leading producers of battery electric models, while Nordic countries show some of the highest electric vehicle penetration rates in the world.
Consistent demand from France, the United Kingdom, and Italy is driven by national incentives and zero-emission areas. There is significant regional expertise in the area of power electronics, thermal management, and electric distribution systems; European companies are making investments in 800V platforms and motor-less propulsion systems. One of the threats is the competition with cheaper imports.
MEA & Latin America Vehicle Electrification Market Insights
The Middle East & Africa region is at an earlier stage, with the United Arab Emirates and Saudi Arabia introducing electric mobility targets, charging networks, and local assembly plans as part of economic diversification. Public transport and fleet electrification pilots are widening demand for electrified buses and commercial vehicles.
Latin America consists of Brazil that has a sizeable automobile manufacturing sector along with strong heritage for hybrid vehicles using the flex-fuel technology. Mexico provides for the growing demand of manufacturing plants that are connected with North American logistics. Vehicle costs and limited coverage of charging stations hinder the uptake of electric vehicles.
Growth Drivers: Emission Regulation and Falling Battery Costs
Stringent emission regulation is the primary growth driver. Governments in major markets have set targets that push automakers to sell more electrified vehicles and to reduce fleet-wide carbon output, and financial penalties for non-compliance encourage rapid product change. Purchase incentives, tax credits, and low-emission zones reinforce the message to consumers and fleets.
Falling battery costs and the expansion of charging infrastructure form a second major driver. Lower pack prices narrow the cost gap with combustion vehicles, while wider public charging reduces range anxiety. Automaker investment in dedicated electric platforms, together with innovation in motors, power electronics, and thermal systems, keeps improving performance and value, which widens the buyer base.
Restraints: High Vehicle Costs and Supply Chain Constraints
However, despite the higher cost of electric vehicle compared to conventional automobiles at first purchase, the cost of purchasing the electric vehicle is still a hurdle, particularly in economies that lack incentive programs. Batteries and electronics continue to be costly parts of the automobile, and buyers evaluate this in terms of their value upon resell and convenience.
Supply chain constraints present a further restraint. Dependence on critical minerals such as lithium, nickel, cobalt, and rare earths concentrates risk in a few countries, and trade policy shifts add uncertainty. Shortages or price spikes can disrupt production, and the need to secure long-term supply agreements raises capital commitments for automakers and suppliers.
Opportunities: Integrated Drive Systems and 48V Electrification
Integrated drive systems offer a substantial opportunity. Combining the motor, inverter, and gearbox in one unit saves space, weight, and cost, and suppliers that win high-volume programs can secure revenue streams stretching many years ahead. Range-extended and hybrid architectures are also creating demand for new integrated modules.
The spread of 48V systems offers a further avenue for growth. They provide meaningful efficiency gains at lower cost than full hybridization, and they support electrified auxiliaries such as electric cross differentials, compressors, and steering. Emerging markets and commercial vehicles provide additional headroom as suppliers adapt products to local needs.
Recent Developments
- 2026: Continental partnered with Renault Group’s Garage Futurama to develop energy-efficient electric vehicles, using tires delivering up to 35% lower rolling resistance than the EU A-rating threshold.
- 2026: Valeo inaugurated a new Pune manufacturing line for integrated 3-in-1 e-Axles, supplying Mahindra’s Born Electric platform with locally developed and manufactured electric powertrains.
- 2026: ZF presented hybrid and electric driveline technologies for commercial vehicles, combining electrified propulsion, braking, air management, and software to support application-specific emissions reduction.
- 2026: Magna introduced its DHD REX range-extender hybrid drive, featuring a modular single-motor architecture designed for range-extended electric vehicles across B- through E-segment applications.
Vehicle Electrification Companies are:
- Robert Bosch GmbH
- Continental AG
- Denso Corporation
- BorgWarner Inc.
- Aptiv PLC
- Valeo SE
- ZF Friedrichshafen AG
- Magna International Inc.
- Hitachi Astemo, Ltd.
- Mitsubishi Electric Corporation
- Infineon Technologies AG
- Nidec Corporation
- Vitesco Technologies Group AG
- Lear Corporation
- Delphi Technologies
- Marelli Holdings Co., Ltd.
- Dana Incorporated
- Schaeffler AG
- Hyundai Mobis Co., Ltd.
- CATL (Contemporary Amperex Technology Co., Limited)
Vehicle Electrification Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 121.98 Billion |
| Market Size by 2035 | USD 338.63 Billion |
| CAGR | CAGR of 10.75% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Vehicle Type (Passenger Cars, Commercial Vehicles, Two-Wheelers) • By Propulsion Type (Battery Electric Vehicles, Plug-in Hybrid Electric Vehicles, Full Hybrid Electric Vehicles, Mild Hybrids) • By Component (Electric Power Steering, Start/Stop System, Electric A/C Compressor, Electric Pump, Batteries, Electric Motors, Power Electronics, Charging Infrastructure, Thermal Management, Others) • By Voltage Architecture (48V, 400V, 800V and Above) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Robert Bosch GmbH, Continental AG, Denso Corporation, BorgWarner Inc., Aptiv PLC, Valeo SE, ZF Friedrichshafen AG, Magna International Inc., Hitachi Astemo, Ltd., Mitsubishi Electric Corporation, Infineon Technologies AG, Nidec Corporation, Vitesco Technologies Group AG, Lear Corporation, Delphi Technologies, Marelli Holdings Co., Ltd., Dana Incorporated, Schaeffler AG, Hyundai Mobis Co., Ltd., CATL (Contemporary Amperex Technology Co., Limited) |
Frequently Asked Questions
Key players include Robert Bosch GmbH, Continental AG, Denso Corporation, BorgWarner Inc., Aptiv PLC, and Valeo SE, among other automotive suppliers.
Integrated drive systems and the spread of 48V electrification represent the primary opportunities for suppliers.
Growth is primarily driven by stringent emission regulation, falling battery costs, and expanding charging infrastructure.
By Vehicle Type, Passenger Cars dominated the market with a 68.40% share in 2025, reflecting their dominant share of global vehicle production.
Asia Pacific dominated the market with a 46.80% share in 2025, supported by the world's largest electric vehicle production base and battery supply chain.
