
Wheat Protein Market Report Scope & Overview:
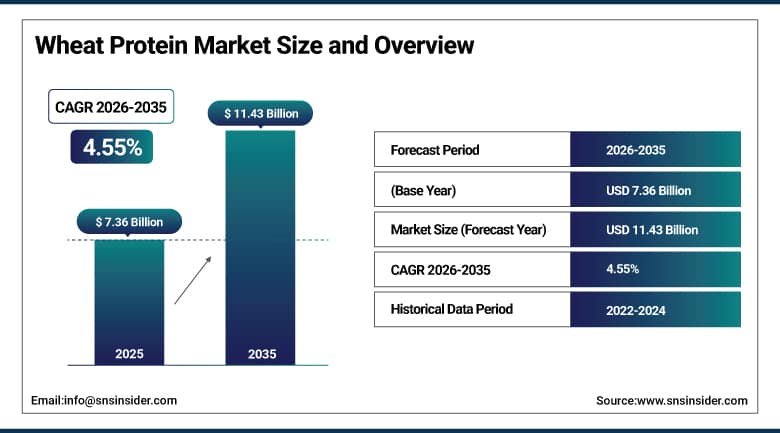
The wheat protein market was valued at USD 7.36 Billion in 2025 and is expected to reach USD 11.43 Billion by 2035, growing at a CAGR of 4.55% from 2026 to 2035.
Market for wheat protein is showing tremendous growth due to its conventional usage in food and bakery items, high nutrition and protein content, and increased consumer demand for protein-based foods. Wheat protein includes protein substances that are insoluble, including gliadin and glutenin proteins that have the characteristics similar to that of wheat flour, thus making it possible to use in various bakery items such as breads, nutritional bars, nutraceutical supplements, and many other types of food items. Additionally, the market growth is being driven due to meat substitutes and vegetarianism, increasing food processing and bakery industry, and health consciousness of consumers who have started to decrease their meat consumption in order to decrease fat intake.
Weight management has always been a problem among the population, but over the years it has turned into an epidemic, with rising aging populations, increasing income levels, and rapid urbanization continuing to fuel demand for protein-enriched products, while technological advancements in the cosmetics industry are simultaneously expanding wheat protein's role in natural and organic personal care formulations across major markets including India and China.
To Get More Information On Wheat Protein Market - Request Free Sample Report
Wheat Protein Market Trends
- Rising demand for meat alternatives and plant-based diets is driving strong textured wheat protein adoption, reflecting growing consumer interest in sustainable, high-protein food options.
- Growing hydrolyzed wheat protein adoption in personal care products is expanding the ingredient's reach beyond food applications into natural and organic cosmetics formulations.
- Increasing sports nutrition product adoption is being driven by wheat protein's high amino acid content and easy digestibility, appealing to fitness-focused, protein-conscious consumers.
- Expanding innovation in processing technologies is enhancing the quality and functionality of wheat protein products, supporting integration into an increasingly diverse range of functional foods.
- Strategic partnerships among wheat protein manufacturers, plant-based food companies, and personal care brands are supporting development of increasingly diverse, application-specific ingredient solutions.
The U.S. Wheat Protein Market Outlook
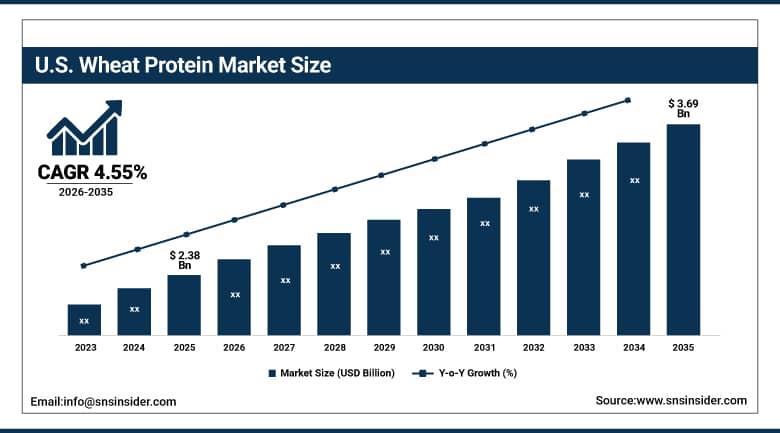
The U.S. wheat protein market was valued at USD 2.38 Billion in 2025 and is projected to reach USD 3.69 Billion by 2035, growing at a CAGR of 4.55% during 2026–2035.
Top food and beverages producers in the country are constantly looking into expanding the use of wheat protein, considering the prevalence of the plant-based food market in the region and the high level of consumer knowledge regarding protein-rich diets. High demand for wheat protein from sports nutrition and growing health consciousness along with increased applications in the food industry along with the increased use of wheat protein in meat substitutes and bakery formulations keep the demand strong in the country.
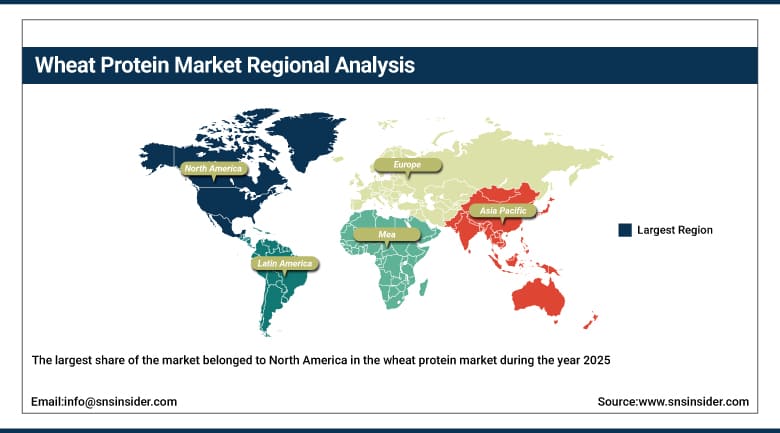
North America is expected to dominate the wheat protein market with a market share of 38% of the total revenue generated by the global market, as it has an established market for plant-based foods and consumer awareness regarding the benefits of protein-rich diets.
Wheat Protein Market Segment Analysis
- By Form, dry dominated the wheat protein market with a 60.60% share in 2025, while liquid is the fastest-growing form segment with a CAGR of 9.11% from 2026–2035.
- By Product Type, wheat gluten dominated the wheat protein market with a 44.60% share in 2025, while textured wheat protein is the fastest-growing product type segment with a CAGR of 8.98% from 2026–2035.
- By Application, bakery & snacks dominated the wheat protein market with a 46.80% share in 2025, while sports nutrition & nutritional bars is the fastest-growing application segment with a CAGR of 8.00% from 2026–2035.
- By Concentration, wheat protein concentrate dominated the wheat protein market with a 58.60% share in 2025, while wheat protein isolate is the fastest-growing concentration segment with a CAGR of 7.80% from 2026–2035.
By Form, dry dominated the wheat protein market, while liquid is the fastest-growing segment.
Based on form, the dry segment led the global wheat protein market share in 2025 due to its superior shelf life, ease of transportation, simple storage requirements, and widespread compatibility with industrial food manufacturing processes. Wheat proteins in their dry form are used more widely in bakery mixes, snacks, extruded foods, meat substitutes, and animal feeds because they are easy to handle and mix with the rest of the ingredients in the production process.
The liquid segment is expected to be the most rapidly growing segment with a CAGR of 9.11%. The segment is growing due to an increasing demand for liquid formats of wheat proteins for application in various food and beverages where instant solubility is desired. This is because manufacturers are now preferring efficient manufacturing processes where the rehydration process for dry formats is not required.
By Product Type, wheat gluten dominated the wheat protein market, while textured wheat protein is the fastest-growing segment.
In 2025, the wheat gluten market was the major revenue generator for the wheat protein market, owing to its extensive application in bakery, confectionery, noodles, snack food, and meat substitutes. The excellent viscoelastic characteristics and dough strengthening capacity of wheat gluten, along with its cost-effectiveness, make it the most commercially successful form of wheat protein.
When comparing different categories of products, textured wheat protein is expected to record the highest CAGR of 8.98%. This can be attributed to the presence of intense innovation activities within the market and increasing applications of the product in plant-based future generation foods. Textured wheat protein continues to gain demand among consumers who are looking forward to sustainable and protein-rich diets owing to its excellent binding ability.
By Application, bakery & snacks dominated the wheat protein market, while sports nutrition & nutritional bars is the fastest-growing segment.
The bakery & snacks segment dominated the wheat protein market owing to wheat gluten's fundamental role strengthening dough structure and improving texture across bread, confectionery, and snack manufacturing, representing the largest and most established application category for wheat protein products across both developed and emerging food manufacturing markets worldwide.
The growing acceptance of wheat protein in sports nutrition applications is linked to the high amount of amino acids it contains as well as to its easy digestibility; the segment is anticipated to exhibit a 8.00% CAGR during the forecast period. The increasing number of health-conscious consumers interested in protein intake is fueling high growth in wheat protein-based nutritional bars and sports supplements.
By Concentration, wheat protein concentrate dominated the wheat protein market, while wheat protein isolate is the fastest-growing segment.
The wheat protein concentrate segment dominated the wheat protein market owing to its cost-effective production and broad functional applicability across bakery, confectionery, and general food manufacturing applications, representing the more commonly used concentration category among the majority of mainstream commercial food formulation applications worldwide.
The wheat protein isolate segment is expected to register the fastest CAGR of 7.80% during the forecast period 2026-2035. Growing demand for higher-purity, higher-protein-content wheat protein formulations suited to premium sports nutrition, meat analogue, and specialty dietary supplement applications is driving rising segment growth as manufacturers increasingly pursue differentiated, premium-positioned protein ingredient offerings.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.00% |
|
Europe |
Germany |
27.60% |
|
Asia Pacific |
China |
44.60% |
|
Middle East & Africa |
UAE |
25.60% |
|
Latin America |
Brazil |
37.70% |
North America Wheat Protein Market Insights
The largest share of the market belonged to North America in the wheat protein market during the year 2025, accounting for 38% of global revenue due to the already developed market for plant-based foods and high consumer awareness regarding protein-rich diets in the region.
The US led the North America wheat protein market in the year 2025 due to the presence of well-developed infrastructure for the production of plant-based foods and consumers' preference for sports nutrition and meat alternatives. The Canadian contribution to the regional market is through their own food processing industry and consumers' growing interest in plant-based protein.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Wheat Protein Market Insights
Europe wheat protein market is considered one of the key contributors in 2025. This is because of the region's rich history of baking and candy production, the growing number of vegetarians in the region, and the strong presence of top-notch wheat protein players in the region.
Germany is one of the major markets in Europe owing to its strong food processing base and growing vegan and vegetarian consumer population. Other countries such as France, home to major wheat protein producer Roquette Frères, and the Netherlands are also contributing to market growth through extensive wheat processing infrastructure.
Asia Pacific Wheat Protein Market Insights
The Asia-Pacific region witnessed the fastest growth, with China and India leading due to their expanding processed food markets and growing health-conscious population, positioning the region as the fastest-growing wheat protein market during the forecast period.
China is one of the main growth drivers in the Asia Pacific wheat protein market, owing to its rapidly expanding processed food manufacturing base and growing consumer demand for natural and organic substitutes. India is also contributing significantly to regional growth through its expanding health-conscious population and growing plant-based protein consumption across the country's rapidly developing food manufacturing sector.
Middle East & Africa and Latin America Wheat Protein Market Insights
Middle East & Africa and Latin American regions are gradually expanding wheat protein adoption as food processing investment grows and consumer awareness of protein-enriched diets increases across both regions.
Brazil is set to be a prominent Latin American market fueled by growing food processing capacity and rising consumer demand for protein-enriched food products. The Middle East & Africa region has UAE and Saudi Arabia investing in modern food processing infrastructure that is gradually increasing demand for wheat protein across their expanding bakery and food manufacturing sectors.
Market Dynamics
Growth Drivers: Rising plant-based protein demand and bakery industry expansion driving market growth
Traditional use in food and bakery products, high nutritional value and protein content, and increased consumer demand for protein-enriched foods are among the primary drivers of the wheat protein market. Growth in meat alternatives and vegetarian diets, along with expansion of the food processing and bakery industry, continues to support sustained wheat protein demand across an increasingly diverse range of food manufacturing applications worldwide.
Increasing demand for plant-based nutrition along with a growing vegan population in emerging economies is driving wheat protein market growth, while rising income levels and increased urbanization are likely to further fuel product demand. Technological advancements in processing technologies enhancing product quality and functionality, growing integration into functional foods, and expanding cosmetics industry demand for natural and organic substitutes are further supporting demand across the forecast period.
Restraints: Gluten sensitivity concerns and raw material price volatility limiting market expansion
One of the most prominent challenges to growth in the market is the increasing awareness by the consumer about sensitivity to gluten and the celiac condition, limiting the uptake of wheat protein in spite of its multiple advantages in the health and nutrition category, due to the presence of this disease.
The unpredictable pricing of the wheat commodity due to the cycles of agriculture and weather conditions is another challenge that affects wheat protein producers and food manufacturers in negotiating long-term deals for their supply needs. The increasing competition from other plant-based protein sources such as pea, soy, and rice protein limits wheat protein market share in some specific premium categories.
Opportunities: Expansion of personal care applications and sports nutrition demand creating new growth avenues
Hydrolyzed wheat protein is emerging as a preferred ingredient in personal care products, creating substantial opportunities for manufacturers capable of delivering natural, plant-derived alternatives to synthetic personal care ingredients across an increasingly clean-label-focused beauty and skincare product category.
In terms of development of textured wheat protein-based products to cater to the increasing demand for meat alternatives based on plants, there are numerous opportunities for growth. The increase in consumption of sports nutrition products and processed food products in developing nations like China and India in the Asia Pacific region is likely to present a huge demand opportunity in future.
Recent Developments:
- 2025: Cargill expanded its wheat gluten production capacity, strengthening its ability to supply plant-based meat alternative manufacturers seeking reliable, high-functionality protein ingredients.
- 2025: Roquette Frères launched an updated textured wheat protein product line, offering plant-based food manufacturers enhanced binding properties and meat-like texture for meat analogue applications.
- 2026: MGP Ingredients expanded its wheat protein isolate manufacturing capacity, targeting growing demand from premium sports nutrition and specialty dietary supplement customers.
- 2026: Archer Daniels Midland launched a new hydrolyzed wheat protein ingredient designed for personal care applications, targeting cosmetics manufacturers seeking natural, plant-derived formulation alternatives.
Wheat Protein Market key players are:
- Cargill, Incorporated
- Archer Daniels Midland Company
- Roquette Frères
- MGP Ingredients, Inc.
- Kerry Group plc
- IFF (DuPont de Nemours, Inc.)
- Ingredion Incorporated
- GLICO NUTRITION CO., LTD.
- Manildra Group
- Tereos S.A.
- Crespel & Deiters GmbH & Co. KG
- Sonic Biochem Extractions Ltd.
- Bunge Limited
- ADM Milling Co.
- Bühler Group
- Tate & Lyle plc
- Emsland Group
- BENEO GmbH (Sudzucker AG)
- Batory Foods
- Glutenin GmbH
Wheat Protein Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 7.36 Billion |
| Market Size by 2035 | USD 11.43 Billion |
| CAGR | CAGR of 4.65% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Wheat Gluten, Wheat Protein Isolate, Textured Wheat Protein, Hydrolyzed Wheat Protein) • By Form (Dry, Liquid) • By Application (Bakery & Snacks, Animal Feed, Sports Nutrition & Nutritional Bars, Personal Care & Cosmetics) • By Concentration (Wheat Protein Concentrate, Wheat Protein Isolate) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Cargill, Incorporated, Archer Daniels Midland Company, Roquette Frères, MGP Ingredients, Inc., Kerry Group plc, IFF (DuPont de Nemours, Inc.), Ingredion Incorporated, GLICO NUTRITION CO., LTD., Manildra Group, Tereos S.A., Crespel & Deiters GmbH & Co. KG, Sonic Biochem Extractions Ltd., Bunge Limited, ADM Milling Co., Bühler Group, Tate & Lyle plc, Emsland Group, BENEO GmbH (Südzucker AG), Batory Foods, Glutenin GmbH. |

Frequently Asked Questions
The Wheat Protein Market is expected to grow at a CAGR of 4.55% from 2026 to 2035.
The Wheat Protein Market was valued at USD 7.36 Billion in 2025.
The market is driven by traditional use in food and bakery products, high nutritional value and protein content, and increased consumer demand for protein-enriched foods.
The Wheat Gluten segment dominated the Wheat Protein Market in 2025, driven by widespread use in bakery, confectionery, and meat analogue applications.
The North America region dominated the Wheat Protein Market in 2025, contributing 38% of global revenue, driven by an established plant-based food market.
