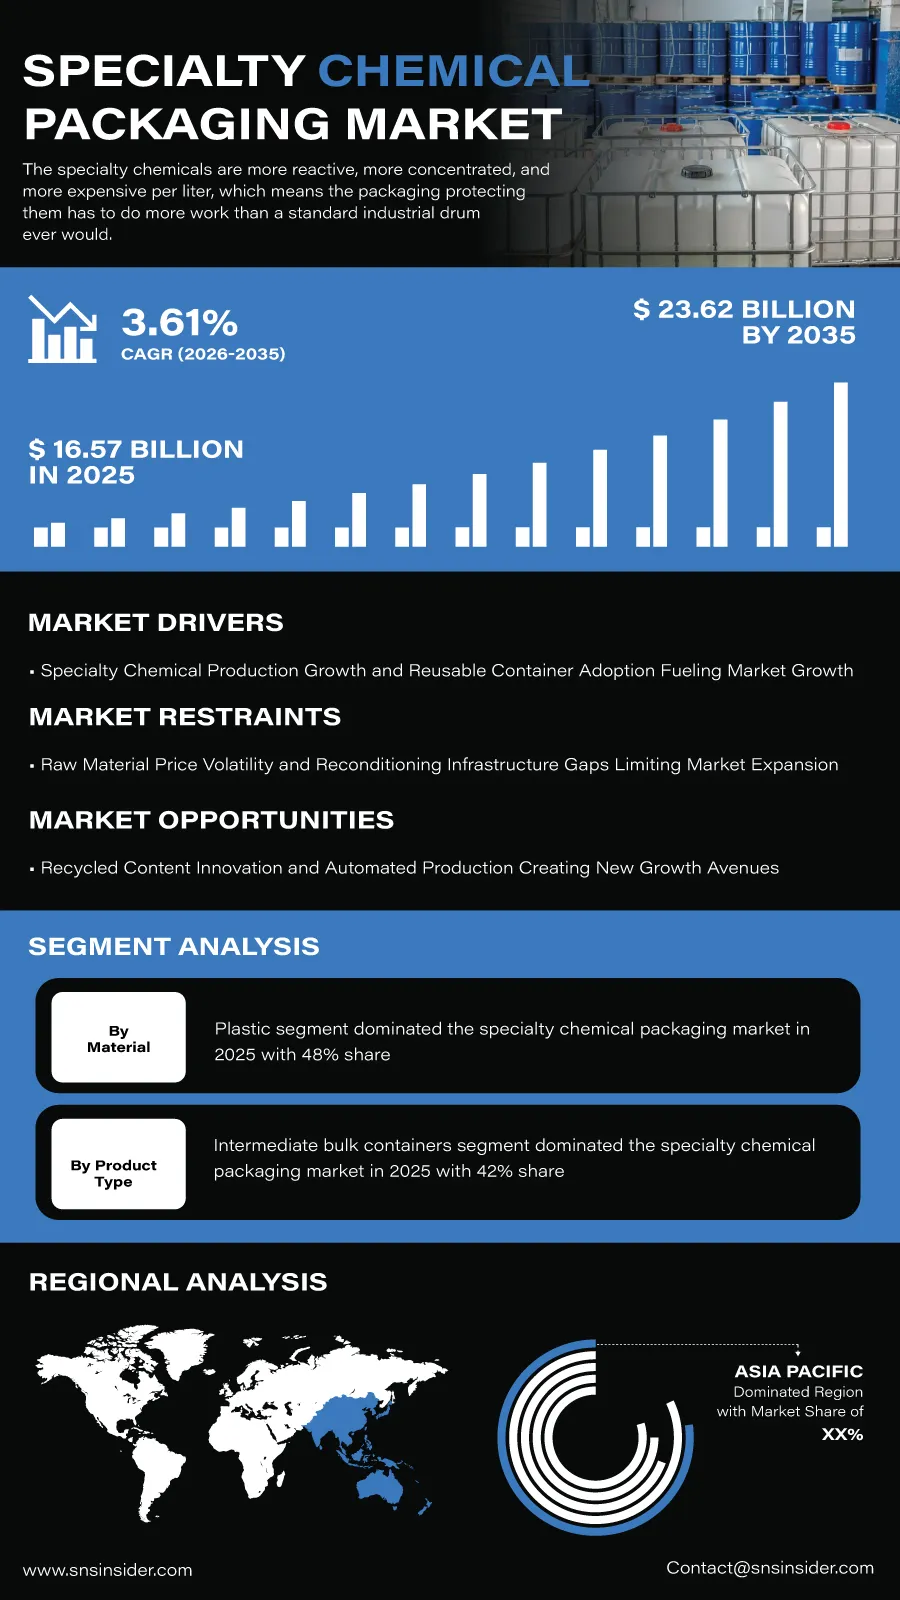
The global Specialty Chemical Packaging Market is on a steady growth path through 2035, as expanding specialty and petrochemical production capacity continues reshaping packaging requirements worldwide. “According to a recent study by SNS Insider, the global Specialty Chemical Packaging Market size valued at USD 16.57 billion in 2025, is anticipated to grow to USD 23.62 billion by 2035, registering a CAGR of 3.61% over the 2026-2035 forecast period.”
Specialty chemicals carry more value and more risk per liter than commodity chemicals, and the packaging protecting them has to account for both, chemical resistance, spill control, and UN dangerous goods certification are not optional extras in this category, they are the baseline requirement. That heightened bar has made specialty chemical packaging a genuine proving ground for material and container design innovation.
Reusability, more than any single new material, is reshaping how chemical producers think about packaging costs right now, as container fleet management programs increasingly let producers treat IBCs as a long-term asset rather than a one-time purchase.
To Get Detailed Insights on the Specialty Chemical Packaging Market – Request a Sample Report
Container Fleet Management Reshapes Packaging Economics
Where specialty chemical packaging was once evaluated almost entirely on upfront purchase price, producers are increasingly weighing total cost of ownership across a container's full reconditioning and reuse lifecycle.
This shift is changing how packaging suppliers structure their customer relationships, since tracking and servicing a reusable container fleet requires a fundamentally different operational model than one-time drum or IBC sales.
Suppliers investing early in reconditioning infrastructure and fleet tracking capability are positioning themselves to win larger, more sophisticated chemical industry contracts as this shift continues.
Key Market Findings Highlight High-Growth Segments
Plastic held the largest share of the Specialty Chemical Packaging Market in 2025, at 48%, reflecting its chemical resistance and cost efficiency relative to metal alternatives.
Metal is the fastest-growing material, expanding at a 6.20% CAGR, pulled forward by producers handling highly reactive or flammable specialty formulations requiring structural integrity.
By product type, intermediate bulk containers led with 42% share in 2025, while bags are growing fastest, at a 6.60% CAGR, as powdered chemical producers favor lighter shipping formats.
Specialty chemicals remained the largest application at 38% share, but petrochemical applications are climbing fastest, at a 6.80% CAGR, driven by expanding regional production capacity.
Certification Depth and Reconditioning Capability Anchor Competitive Positioning
Chemical producers are increasingly evaluating packaging suppliers on certification depth and reconditioning capability nearly as much as on unit price, particularly for higher-value specialty formulations.
Investment in automated production and closed-loop reconditioning infrastructure is becoming a genuine competitive differentiator among larger suppliers, while smaller regional players without that investment increasingly compete only on price.
This divide is expected to sharpen further as chemical producers consolidate their packaging sourcing with fewer, more capable suppliers.
Asia Pacific Leads on Both Scale and Growth
Asia Pacific holds both the largest share of global market revenue and the fastest growth rate, driven by rapid industrialization and substantial specialty and petrochemical production investment across China and India. North America holds a steady, mature share as well, anchored by extensive Gulf Coast chemical manufacturing capacity.
Europe's share is shaped heavily by the EU Packaging and Packaging Waste Regulation, which is accelerating the region's transition toward recycled content and reusable container designs.
Leading Companies Drive Innovation and Competition
Competition in this market centers on certification capability, reconditioning infrastructure, and regional manufacturing scale nearly as much as on unit pricing, with major players investing in automated production to differentiate.
Some of the major companies that operate in the global specialty chemical packaging market are Greif, Inc., Mauser Packaging Solutions, SCHÜTZ GmbH & Co. KGaA, Balmer Lawrie & Co. Ltd., Time Technoplast Ltd., TPL Plastech Ltd., Mondi Group, Amcor plc.
An SNS Insider Analyst Himanshu Sharma commented, “Specialty chemical packaging has become a genuine proving ground for container innovation, and the suppliers capturing the fastest-growing parts of this market are the ones treating reconditioning capability and certification depth as competitive advantages rather than back-office logistics. As specialty and petrochemical production keeps expanding globally, packaging suppliers with strong regional manufacturing and fleet management capability are best positioned to lead.”
About the Author

Get in touch