
Aerostat Systems Market Report Scope & Overview:
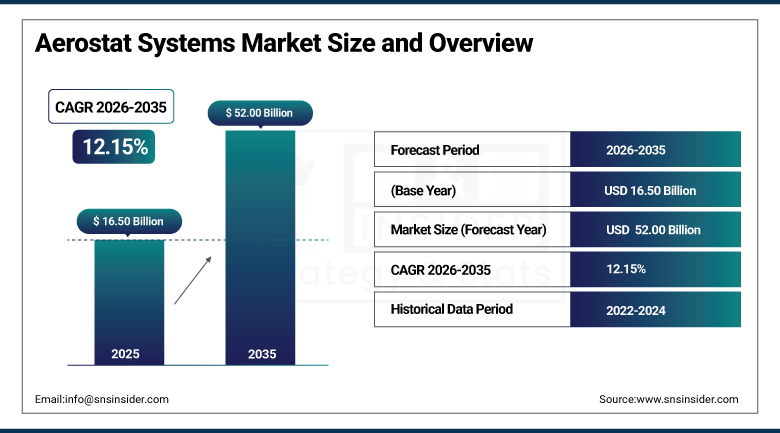
The Aerostat Systems Market was valued at USD 16.50 Billion in 2025 and is expected to reach USD 52.00 Billion by 2035, growing at a CAGR of 12.15% from 2026-2035.
The Aerostat Systems Market growth is being driven primarily by rising government investment in persistent, wide-area surveillance capability, as tethered aerostat platforms offer significantly lower operating costs per flight hour than crewed surveillance aircraft while sustaining continuous coverage for extended periods without requiring a sortie. Growing border security modernization programs, expanding military intelligence, surveillance, and reconnaissance requirements, and rising demand for advanced communication relay platforms continue to reinforce this underlying demand trajectory across both established and emerging defense markets. Traditional balloon designs continue to anchor the market given their ability to deliver roughly 30 days of continuous endurance without fuel burn, even as hybrid and powered variants gain traction among operators seeking heavier payload capacity and greater station-keeping control.
The U.S. Army granted QinetiQ US a prime position on a $4.2 billion Multiple Award Task Order Contract under the Product Director Aerostats program on April 14, 2025, a 10-year Indefinite Delivery/Indefinite Quantity contract supporting system integration, procurement, engineering, and program management for the Army's tethered aerostat surveillance platforms.
To Get more information On Aerostat Systems Market - Request Free Sample Report
Aerostat Systems Market Trends:
-
Rising deployment of tethered aerostats for southern-border surveillance and wide-area radar coverage across major defense markets.
-
Growing adoption of hybrid and powered aerostat variants offering heavier payload capacity beyond traditional balloon designs.
-
Expanding integration of hyperspectral and multi-modal sensing technologies into persistent surveillance aerostat platforms.
-
Increasing use of tethered aerostats for battlefield electronic warfare and intelligence gathering in active conflict zones.
-
Growing commercial and civil adoption of aerostat platforms for disaster response and temporary communications infrastructure.
-
Rising government procurement programs validating long-duration airborne sensor technology as a cost-effective surveillance alternative.
U.S. Aerostat Systems Market Outlook:
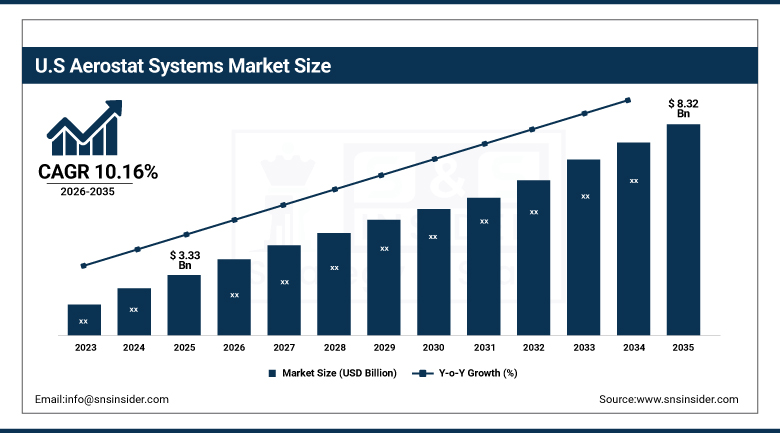
The U.S. Aerostat Systems Market was valued at USD 3.33 Billion in 2025 and is expected to reach USD 8.32 Billion by 2035, growing at a CAGR of 10.16% from 2026-2035.
The U.S. Aerostat Systems Market growth continues to be reinforced by sustained Department of Homeland Security and Department of Defense investment in tethered aerostat radar systems supporting southern-border surveillance and overseas defense operations. Continued congressional appropriations toward persistent surveillance modernization programs, combined with the technology's demonstrated cost advantage over crewed surveillance aircraft, continue to support sustained domestic procurement across multiple aerostat platform categories and mission profiles.
QinetiQ US secured a five-year, $170 million contract from the Department of Homeland Security's Customs and Border Protection in November 2023 to provide operations and maintenance support for the Tethered Aerostat Radar System, covering eight fixed sites including six along the U.S.-Mexico border, one over the Florida Straits, and one over the northern Caribbean.
Aerostat Systems Market Segment Analysis:
-
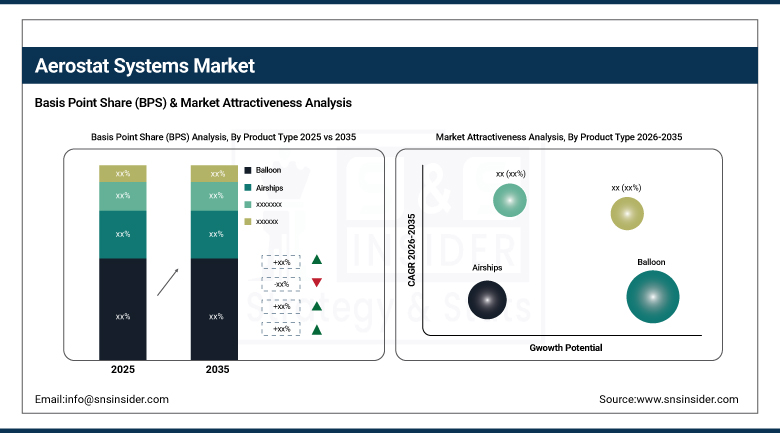
By Product Type, the Balloon segment dominated the Aerostat Systems Market with approximately 42.00% share in 2025, while the Airships segment is the fastest growing with a CAGR of approximately 15.80%.
-
By Class, the Compact-Sized segment dominated the Aerostat Systems Market with approximately 42.51% share in 2025, while the Large-Sized segment is the fastest growing with a CAGR of approximately 15.43%.
-
By Propulsion System, the Unpowered segment dominated the Aerostat Systems Market with approximately 65.54% share in 2025, while the Powered segment is the fastest growing with a CAGR of approximately 17.69%.
-
By End-User, the Military/Defense segment dominated the Aerostat Systems Market with approximately 68.98% share in 2025, while the Commercial/Civil segment is the fastest growing with a CAGR of approximately 15.24%.
By Product Type, Balloon Dominates the Aerostat Systems Market and Airships Grows Fastest
Balloon platforms remain the standard configuration across the product-type segment, valued for their simple, proven design and their ability to sustain roughly 30 days of continuous operation without fuel burn, a real endurance advantage over powered aerial platforms requiring regular refueling or battery replacement. Growing defense budgets earmarked specifically for multi-sensor, multi-mission platforms continue to widen the addressable market for larger airship configurations capable of carrying radar, electro-optical, and signals intelligence payloads simultaneously.
Airships represent the fastest-growing product category, as operators increasingly favor their greater internal volume and payload flexibility for missions requiring multiple simultaneous sensor packages. Continued defense investment in multi-sensor, multi-mission aerostat platforms is reinforcing this above-average growth trajectory relative to the broader balloon-dominated product mix.
By Class, Compact-Sized Dominates the Aerostat Systems Market and Large-Sized Grows Fastest
Compact-sized aerostats hold the largest class share, favored for their lower acquisition cost, easier field deployment, and suitability for tactical-level surveillance missions requiring rapid setup and relocation across changing operational areas. Rising defense budgets in several countries specifically earmarked for strategic-level, high-altitude surveillance infrastructure continue to widen the addressable market for large-class platforms beyond their traditional concentration in a handful of established defense markets.
Large-sized platforms represent the fastest-growing class, as strategic surveillance missions increasingly demand higher-altitude operation, extended endurance, and heavier multi-sensor payloads that only larger envelope designs can practically support. Growing national-level border security and homeland defense programs continue to reinforce this segment's accelerating adoption.
By Propulsion System, Unpowered Dominates the Aerostat Systems Market and Powered Grows Fastest
Unpowered aerostats continue to dominate the propulsion segment, reflecting their fundamentally simpler design, lower maintenance requirements, and proven reliability across decades of tethered surveillance deployment worldwide. Coastal and maritime border surveillance programs in particular continue to favor powered configurations, since the ability to adjust position in response to shifting weather or operational priorities offers a real tactical advantage over fixed tethered deployment.
Powered aerostats represent the fastest-growing propulsion category, as operators increasingly value the station-keeping control and limited repositioning capability powered systems offer relative to purely tethered, wind-dependent platforms. Growing demand for maritime surveillance applications, where positional flexibility matters more than in fixed land-based deployment, continues to support this segment's above-average growth.
By End-User, Military/Defense Dominates the Aerostat Systems Market and Commercial/Civil Grows Fastest
Military and defense clients comprise a large share of aerostats systems demand due to the military nature of their development and their continuous significance in the architecture of national intelligence, surveillance, and reconnaissance, as well as the use of the technology as a solution for battlefield and border surveillance. Telecommunications operators in particular become more and more interested in the application of aerostats as temporary communication networks after natural disasters, thus extending the application range of the technology even further from its military origin.
Commercial and civil users are currently the fastest growing group of potential clients due to the increasing demand for aerostats among disaster relief agencies and telecommunications operators for establishing temporary communication networks after natural disasters.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.20% |
|
Europe |
United Kingdom |
26.60% |
|
Asia Pacific |
India |
40.20% |
|
Latin America |
Brazil |
27.80% |
|
Middle East & Africa |
Israel |
33.60% |
North America Aerostat Systems Market Insights
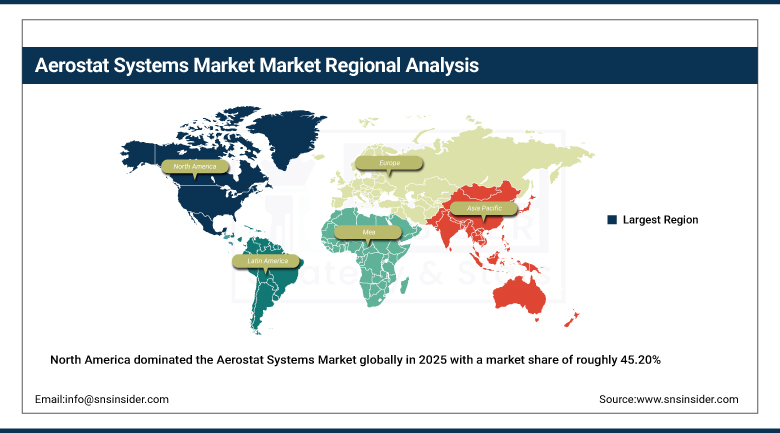
North America dominated the Aerostat Systems Market globally in 2025 with a market share of roughly 45.20%, owing to the ongoing investments by the U.S. Army and the Department of Homeland Security in the development of tethered aerostat systems through their funding of the $4.2 billion Product Director Aerostats contract announced in April 2025. The ongoing congressional appropriations for modernizing persistent surveillance systems also further reinforce the position of North America despite the relatively slower growth rates of the region compared to Asia Pacific regions.
Canada generates further regional demand due to its involvement in North American military procurements as well as joint border security programs. Congressional appropriations for modernizing persistent surveillance systems also further reinforce the position of North America as the leader. The participation of Mexico in the joint North American border surveillance programs also further binds the demand for the region's aerostats.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Aerostat Systems Market Insights
Asia Pacific is expected to register the highest CAGR throughout the forecasted 2026-2035 period due to increasing investments into border security modernization projects in Asia Pacific's most populated countries, estimated at about 14.25% per annum. The Indian nation plays an important role in driving the regional market due to the continuing investment into border surveillance systems that operate on the nation's vast territory. Government-sponsored research funds within Asia Pacific's largest economies are also facilitating faster commercialization of locally-developed aerostat systems, reducing technological gap between local solutions and the offerings provided by more experienced Western companies.
China and South Korea are adding to the regional demand, backed up by growing budgets of military modernization projects and increasing demand for coastal surveillance systems. Increasing regional tensions are contributing to rapid growth in the region. The ongoing investments into Japan's coastal maritime domain awareness project, alongside the increasing domestic production of aerostat systems within several regional economies, are supporting Asia Pacific's rapid growth compared to more mature Western markets.
Europe Aerostat Systems Market Insights
The European region is an important market for aerostat systems due to its well-established military research capabilities in the United Kingdom, in addition to the presence of most of the aerostat producers such as Lindstrand Technologies and Allsopp Helikites. Furthermore, the ongoing commitment of the United Kingdom in producing aerostats in addition to the rising demands on such platforms in NATO countries would ensure continuous demand on aerostat systems within Europe.
The continued use of aerostat systems during the wars of Ukraine to carry out electronic warfare and intelligence operations, including the launching of the latest tethered aerostat system by the company Aerobavovna in May 2025, which can lift six kilograms of payload, reflects the importance of aerostat systems in warfare. France and Germany are contributing to regional demand on aerostat systems due to their modernization efforts for the defense of their forces as members of NATO.
MEA & Latin America Aerostat Systems Market Insights
The Middle East and Africa region reflects a strategically significant market, with Israel accounting for the largest regional contribution through its established aerospace and defense industrial base, home to Israel Aerospace Industries, a leading global aerostat systems developer. Growing recognition among regional governments of the strategic value persistent aerial surveillance offers against asymmetric and border security threats continues to support gradual, if measured, investment across markets that have historically prioritized conventional defense procurement.
Latin America remains a smaller contributor to global demand, with Brazil accounting for the majority of regional interest on the strength of its growing border and coastal surveillance requirements. Gradual expansion of regional defense budgets continues to support steady market development. Mexico and Argentina contribute additional secondary demand tied to their respective border security and coastal monitoring programs, with both countries continuing to explore aerostat-based alternatives to more expensive crewed surveillance aircraft.
Market Dynamics:
Growth Drivers: Persistent Surveillance Demand and Border Security Modernization
The increase in government funding into the development of wide-area surveillance capability emerges as the key factor driving the market as the tethered aerostats exhibit relatively cheaper cost-per-hour of operation as compared to manned aircrafts with continuous and uninterrupted surveillance. The increasing requirement for communication relay systems especially in areas that lack ground infrastructure is another underlying factor driving this growth in the market. Modernization efforts of border security programs in some of the leading defense markets emerge as another underlying driver of growth in the market.
Modernization of border security programs in some of the top defense markets is yet another important driver of growth in the market. Increased requirement of battlefield electronic warfare and intelligence gathering applications emerges as another underlying factor driving the growth in the market. The increased demand for communication relay platforms especially in areas that lack ground infrastructure is another underlying factor driving this growth in the market.
Restraints: Weather Sensitivity and Operational Limitations
Aerostat platforms remain notably sensitive to severe weather conditions, including high winds and lightning, which can force temporary deployment suspension and limit continuous operational availability relative to satellite-based surveillance alternatives. Ground infrastructure requirements, including mooring stations and tether maintenance facilities, also add meaningful upfront capital cost relative to more mobile surveillance alternatives, a consideration that can slow adoption among budget-constrained operators.
Fixed or limited positional flexibility for tethered systems adds a further restraint, as unpowered aerostats cannot reposition to track fast-moving threats or adapt quickly to shifting operational priorities the way mobile surveillance platforms can. Ground infrastructure requirements, including mooring stations and tether maintenance facilities, also add meaningful upfront capital cost relative to more mobile surveillance alternatives, a consideration that can slow adoption among budget-constrained regional operators evaluating long-term procurement options.
Opportunities: Commercial Diversification and Multi-Sensor Integration
Expanding commercial and civil applications present a substantial growth opportunity, as disaster response agencies and telecommunications providers increasingly recognize aerostat platforms' value for temporary infrastructure deployment following natural disasters or planned events. Suppliers that successfully validate compact, rapidly deployable multi-sensor packages suited to disaster response and temporary infrastructure applications are positioned to capture meaningful new commercial revenue beyond traditional defense procurement cycles.
Continued integration of hyperspectral and multi-modal sensing technologies represents a further opportunity, as manufacturers developing next-generation payload packages capable of simultaneous radar, electro-optical, and signals intelligence collection are positioned to capture premium value from defense customers. Suppliers that successfully validate compact, rapidly deployable multi-sensor packages suited to disaster response and temporary infrastructure applications are positioned to capture meaningful new commercial revenue beyond traditional defense procurement cycles and budget constraints.
Recent Developments:
-
In September 2026, TCOM secured a defense contract valued at more than $600 million to deliver Airspace and Surface Radar Reconnaissance (ASRR) Aerostat Systems to the Polish Armed Forces. The systems will provide persistent surveillance for airborne, maritime, and ground threats.
-
In July 2026, Aerostar and Icarus expanded their strategic partnership to develop a tactically deployable stratospheric surveillance platform. The solution is intended to provide persistent sensing and intelligence capabilities across large geographic areas, including contested Indo-Pacific environments.
Aerostat Systems Market Key Players:
-
TCOM, L.P.
-
Israel Aerospace Industries Ltd.
-
Aerostar International, Inc.
-
Lockheed Martin Corporation
-
RT LTA Systems Ltd.
-
Raytheon Company (RTX)
-
ILC Dover LP
-
Worldwide Aeros Corporation
-
Lindstrand Technologies Ltd.
-
RosAeroSystems International Ltd.
-
Drone Aviation Corp.
-
QinetiQ Group plc
-
Elbit Systems Ltd.
-
Vaisala Oyj
-
Allsopp Helikites Ltd.
-
RAFAEL Advanced Defense Systems Ltd.
-
Near Space Corporation
-
Aerial Products Corporation
-
Raven Industries, Inc.
-
A-NSE
Aerostat Systems Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 16.50 Billion |
| Market Size by 2035 | USD 52.00 Billion |
| CAGR | CAGR of 12.15% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Product Type (Balloon, Airships, Hybrid) • by Class (Compact-Sized, Mid-Sized, Large-Sized) • by Propulsion System (Powered, Unpowered) • by Payload (Surveillance Radar, Electro-Optical/Infrared Sensor, Communication Intelligence, Electronic Intelligence, Inertial Navigation System) • by Application (Military ISR, Border & Coastal Surveillance, Communication Relay, Scientific Research) • by End-User (Military/Defense, Commercial/Civil) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | TCOM, L.P., Israel Aerospace Industries Ltd., Aerostar International, Inc., Lockheed Martin Corporation, RT LTA Systems Ltd., Raytheon Company (RTX), ILC Dover LP, Worldwide Aeros Corporation, Lindstrand Technologies Ltd., RosAeroSystems International Ltd., Drone Aviation Corp., QinetiQ Group plc, Elbit Systems Ltd., Vaisala Oyj, Allsopp Helikites Ltd., RAFAEL Advanced Defense Systems Ltd., Near Space Corporation, Aerial Products Corporation, Raven Industries, Inc., A-NSE |
Frequently Asked Questions
Key players include TCOM, L.P., Israel Aerospace Industries Ltd., Aerostar International, Inc., Lockheed Martin Corporation, and RT LTA Systems Ltd., among other leading defense and aerospace manufacturers.
Expanding commercial and civil applications and continued integration of hyperspectral and multi-modal sensing technologies represent the primary opportunities.
Growth is primarily driven by rising government investment in persistent, wide-area surveillance capability combined with border security modernization programs worldwide.
By Product Type, Balloon dominated the market with approximately 42.00% share in 2025, valued for its 30-day continuous endurance without fuel burn.
North America dominated the market with approximately 45.20% share in 2025, supported by sustained U.S. Army and Department of Homeland Security investment.
