
AI Image Editor Market Report Scope & Overview:
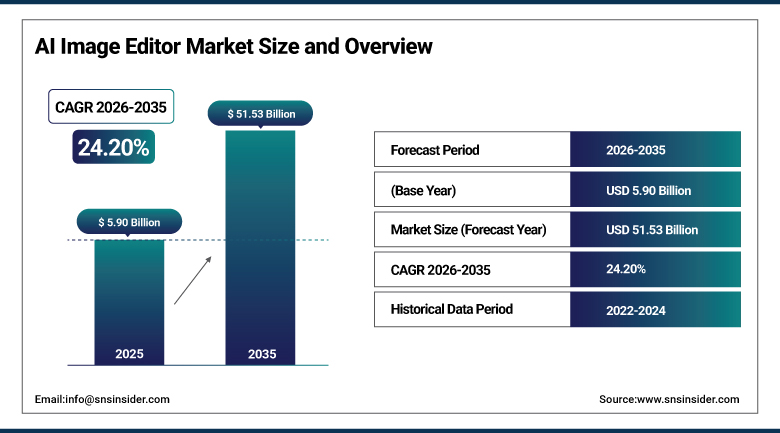
The AI Image Editor Market was valued at USD 5.90 Billion in 2025 and is expected to reach USD 51.53 Billion by 2035, growing at a CAGR of 24.20% from 2026-2035.
The AI Image Editor Market covers software, apps and cloud services that use generative and machine learning models to retouch, restyle, extend, remove objects from, upscale and create images from text or visual instructions. Users range from consumers editing photos on phones to marketing teams producing product imagery at scale and professional photographers automating retouching. Demand is rising because generative models now follow natural-language edits, keep faces, products and styles consistent across versions, and run inside tools people already use. Vendors are bundling editing with design suites, adding agents that operate several apps from one prompt, and licensing models from partners. Competition spans creative software incumbents, design platforms, mobile app makers and model developers.
To Get more information AI Image Editor Market - Request Free Sample Report
⮞On April 15, 2026, Adobe unveiled the Firefly AI Assistant, which lets users describe an outcome in natural language and carries out multi-step tasks across Creative Cloud apps using about 100 tools and skills. It offers prebuilt Creative Skills such as portrait retouching and delivers results as native PSD, AI and PRPROJ files that can be refined in the full applications. Adobe also added Kling 3.0 video models to Firefly, bringing its model library to more than 30, and began a public beta for the assistant.
AI Image Editor Market Trends
- Shift from manual tools to natural-language and agent-driven editing
- Bundling of generative editing inside design suites and creative software
- Growth of character, product and style consistency across multi-step edits
- Move to on-device and mobile editing for social content
- Integration of third-party and partner models into single editing platforms
- Rising use of content credentials and watermarks for provenance
U.S. AI Image Editor Market Outlook
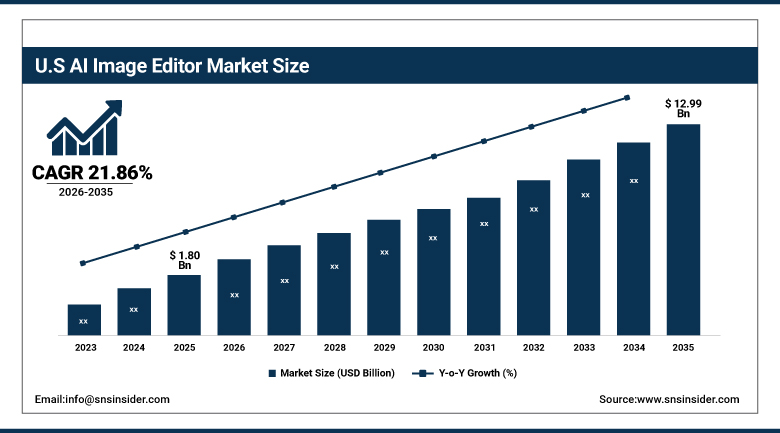
The U.S. AI Image Editor Market was valued at USD 1.80 Billion in 2025 and is expected to reach USD 12.99 Billion by 2035, growing at a CAGR of 21.86% from 2026-2035.
The U.S. AI Image Editor Market is the largest national market in North America, supported by the headquarters of leading creative software, search, social and AI companies and a large base of creators, agencies and e-commerce sellers. American brands use generative editing to produce product shots, social posts and advertising variants quickly, and consumers adopt photo features built into phones and social apps. Competition is intense among established design suites, cloud platforms and image-model start-ups, and pricing is shifting toward bundled subscriptions with usage credits. Copyright, likeness and disclosure rules shape how enterprises deploy the tools.
⮞In August 2024, Midjourney released a unified web editor that combines inpainting, outpainting and canvas extension in one interface, moving the company from prompt-based generation toward direct, region-level editing of existing images. The release placed one of the best-known U.S. image generators in direct competition with design suites and photo editing apps, and it showed demand among creators for precise control over generated and uploaded images.
AI Image Editor Market Segment Analysis
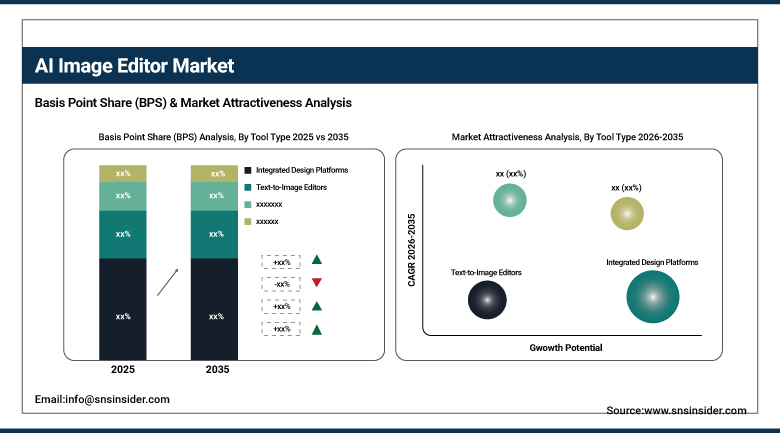
- By Tool Type, the Integrated Design Platforms segment dominated the AI Image Editor Market with approximately 41.60% share in 2025, while the Text-to-Image Editors segment is the fastest growing with a CAGR of approximately 31.80%.
- By Deployment, the Cloud-Based segment dominated the AI Image Editor Market with approximately 52.00% share in 2025, while the On-Device segment is the fastest growing with a CAGR of approximately 27.40%.
- By End-User, the Individual Creators segment dominated the AI Image Editor Market with approximately 44.70% share in 2025, while the Enterprise and Marketing Teams segment is the fastest growing with a CAGR of approximately 26.90%.
- By Application, the Social Media Content Creation segment dominated the AI Image Editor Market with approximately 33.80% share in 2025, while the E-Commerce and Product Visualization segment is the fastest growing with a CAGR of approximately 28.60%.
- By Pricing Model, the Subscription segment dominated the AI Image Editor Market with approximately 47.80% share in 2025, while the Pay-per-Use segment is the fastest growing with a CAGR of approximately 27.10%.
By Tool Type, Integrated Design Platforms Dominates the AI Image Editor Market and Text-to-Image Editors Grows Fastest
Integrated design platforms lead because users prefer generative editing inside the layout, photo and publishing tools they already use, with shared libraries, brand controls and collaboration. Adobe's Firefly features in Photoshop and Express, Canva's design suite and similar offerings add editing, background removal, expansion and restyling next to templates and export options. Bundling lowers switching effort, supports enterprise governance and gives vendors a base of paying subscribers to which new AI features can be sold.
Text-to-image editors are growing fastest as models such as Black Forest Labs' FLUX.1 Kontext and Google's Gemini 2.5 Flash Image let users change an existing picture simply by describing the edit. These models keep people, products and styles consistent across steps, which makes iterative editing practical without masks or layers. Developers embed them in apps and APIs, creating a broad ecosystem of specialized editors. As quality improves and prices fall, instruction-based editing is becoming the default interface.
By Deployment, Cloud-Based Dominates the AI Image Editor Market and On-Device Grows Fastest
Cloud deployment is superior due to the requirement for robust GPUs for large generative models and the ease of updating and billing of software that requires less storage space. End users access editors via browsers and phones without installing software. Large organizations can manage software policies centrally. Software vendors will be able to push new models and provide credit for usage. Cloud delivery also supports team workflows such as asset review, brand approvals and automated batch processing of product images.
On-device editing is growing fastest as phone makers and software vendors run smaller models locally for tasks such as object removal, background replacement and enhancement. Local processing reduces latency and cost, keeps private photos on the device and works offline. Improvements in mobile chips make features once reserved for the cloud available to hundreds of millions of users. Vendors are adopting hybrid designs that handle simple edits locally and send complex generation to servers, which supports both performance and privacy.
By End-User, Individual Creators Dominates the AI Image Editor Market and Enterprise and Marketing Teams Grows Fastest
Individual creators lead by user volume and revenue because hobbyists, influencers, students and small sellers adopt low-cost or freemium editors for social posts, profile images and quick retouching. Mobile apps make generative features accessible, and viral effects drive downloads. Photoroom, for example, reported more than 150 million downloads and about 5 billion images processed each year by early 2024. This large, price-sensitive base supports advertising, in-app purchases and subscription conversion for many vendors.
Enterprise and marketing teams are growing fastest as brands use generative editing to localize campaigns, produce product variants and shorten creative cycles. Enterprises require brand controls, commercially safe training data, access management and audit trails, so they buy premium plans and API access. Agencies automate resizing, retouching and background changes across thousands of images. As governance features mature and agent tools orchestrate multi-step tasks, corporate spending is rising faster than consumer spending.
By Application, Social Media Content Creation Dominates the AI Image Editor Market and E-Commerce and Product Visualization Grows Fastest
Social media content creation leads because billions of images are posted every day and creators constantly seek fast, eye-catching edits. AI tools remove backgrounds, apply styles, retouch portraits, extend canvases and resize images for different platforms in seconds. Templates and trends encourage frequent use, and platforms integrate editing into their own apps. This high-frequency demand makes social content the largest application and a key source of subscription and credit revenue for consumer editors.
E-commerce and product visualization is growing fastest as sellers need clean, consistent images in large volumes and are replacing studio shoots with generated backgrounds, lifestyle scenes and model imagery. Tools such as Photoroom focus on product photos, and enterprise platforms connect with catalogs and marketplaces. Better control of lighting, shadows and brand style improves conversion, while faster turnaround supports seasonal campaigns. Marketplaces encouraging AI-enhanced listings strengthen this adoption over the forecast period.
By Pricing Model, Subscription Dominates the AI Image Editor Market and Pay-per-Use Grows Fastest
Subscriptions lead because vendors have moved from perpetual licenses to monthly or annual plans that bundle software, cloud storage and a set of generative credits. Predictable recurring revenue supports heavy model costs, and customers prefer a single fee that covers editing, templates and updates. Adobe, Canva and others tie plans to credit allowances, and premium tiers add higher quality, faster generation and commercial licensing. This model gives vendors a stable base to fund research and acquisitions.
Pay-per-use is growing fastest as developers, agencies and occasional users prefer to pay only for images they create or edit, and as APIs from model providers charge by image or token. Google priced Gemini 2.5 Flash Image at roughly USD 0.039 per image, making large-scale editing affordable. Usage-based pricing suits e-commerce batch jobs and apps that embed editing, and it lowers the barrier for new entrants. Many vendors now combine subscriptions with extra purchasable credits.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
79.80 |
|
Asia Pacific |
China |
38.70 |
|
Europe |
United Kingdom |
26.40 |
|
Latin America |
Brazil |
47.30 |
|
Middle East & Africa |
United Arab Emirates |
30.20 |
North America AI Image Editor Market Insights
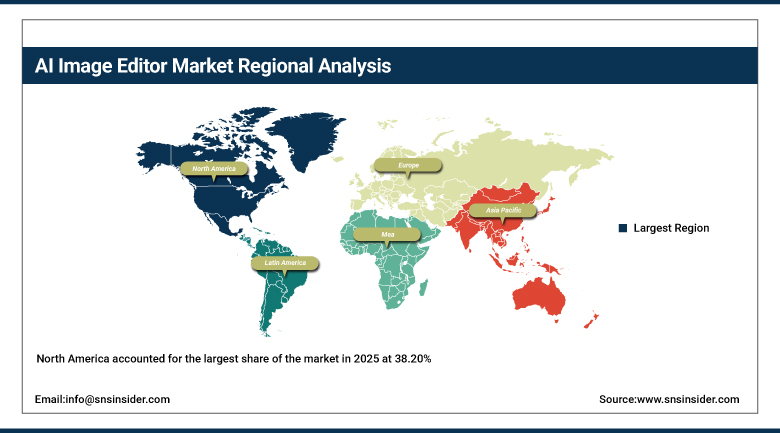
North America accounted for the largest share of the market in 2025 at 38.20%. The United States holds most regional revenue because Adobe, Google, Microsoft, OpenAI, Midjourney and a large number of start-ups are based there, and because consumers and brands adopt new tools quickly. Canada contributes through creative agencies and software developers.
Enterprises are the fastest-growing buyers, adding governance, brand controls and agents to marketing workflows. Growth is slower than in Asia Pacific because the base is large and many consumers already use bundled AI features. Copyright cases, likeness protection and disclosure requirements are shaping vendor practices, and companies that offer commercially safe models and content credentials have an advantage with large buyers.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific AI Image Editor Market Insights
Asia Pacific is the fastest-growing region, advancing at a CAGR of 28.10% during 2026-2035. China leads regional demand through Meitu, Alibaba, ByteDance and other platforms that build photo and video editing into social and e-commerce apps, while Japan, South Korea and India add large smartphone populations and creator economies. Mobile-first usage makes the region a major source of downloads.
Local models and apps compete strongly, and Chinese developers such as Kuaishou supply models that global platforms license, as shown by Adobe adding Kling 3.0 to Firefly. E-commerce sellers on regional marketplaces use automated image tools at very high volume. Government support for artificial intelligence and improving device capability further accelerate adoption among young, mobile-focused users.
Europe AI Image Editor Market Insights
Europe held significant share of the market in 2025 and is growing steadily through 2035. The United Kingdom, Germany and France lead, supported by strong advertising, publishing and e-commerce sectors, and by European developers such as Photoroom in France and Black Forest Labs in Germany. Black Forest Labs released FLUX.1 Kontext, a model that generates and edits images, in May 2025, strengthening the region's model ecosystem.
Regulation impacts buying decisions. The European Union's AI Act and data privacy laws encourage transparency concerning the generated output and caution regarding personal information, thus favoring suppliers with clear origins and compliance capabilities. Photoroom has managed to raise USD 43 Million at an estimated valuation of USD 500 Million in February 2024. Demand is steady across professional photographers, agencies and retailers.
MEA & Latin America AI Image Editor Market Insights
Latin America is growing significantly. Brazil and Mexico lead through social media usage, online retail and small creative businesses that rely on mobile editing apps. Affordable freemium tools and credit-based pricing suit price-sensitive users, and local marketplaces encourage sellers to improve product photos.
The Middle East and Africa held contributive share of the market in 2025. The United Arab Emirates and Saudi Arabia are investing in artificial intelligence and creative industries, and young populations are heavy social media users. South Africa, Nigeria and Egypt add mobile-first demand. Connectivity gaps and payment limits still restrain paid adoption, but cheaper smartphones and local-language tools are widening the user base.
Market Dynamics
Growth Drivers: Generative Model Quality, Content Volume and Platform Bundling
Rapid improvement in generative models is the main driver. Systems such as Gemini 2.5 Flash Image and FLUX.1 Kontext follow plain-language instructions, keep subjects consistent and edit in seconds, which removes the need for advanced skills. Falling inference costs make large-scale use practical, and a wider range of users can now produce professional-looking results.
Growing content volume and platform bundling add momentum. Social media, e-commerce and advertising need constant streams of visual assets, and creative suites embed generative tools so that users adopt them within existing workflows. Adobe's agentic assistant and Canva's acquisition of Leonardo.ai show vendors investing to keep users on their platforms and to raise average revenue per subscriber.
Restraints: Copyright Uncertainty, Quality Control and Model Costs
Copyright uncertainty is a significant restraint. Doubts arise regarding issues around training data, ownership of the images created, and even the image of actual individuals leading to lawyers being on edge, and even restrictions being imposed by clients. Vendors who are not able to show licenses for the data used as well as indemnity will experience slow adoption by enterprises.
Quality assurance and the cost of the models also become factors. The edited images may create artifacts, distort text, and change faces which need human intervention. Running large models is expensive, which squeezes margins on free tiers and forces vendors to limit credits or raise prices, creating friction with price-sensitive users.
Opportunities: Agentic Workflows, E-Commerce Automation and Enterprise Brand Tools
Agentic workflows offer a major opportunity, since assistants that plan and run multi-step edits across several applications reduce effort and open advanced tools to non-experts. Adobe's Firefly AI Assistant, with Creative Skills and native file output, shows how vendors can turn editing into outcome-based services and increase usage of paid features.
E-commerce automation and enterprise brand tools provide further opportunities. Automated creation of catalog images, backgrounds, and local variations is possible for retailers. Companies require brand-safe systems which are trained on authorized assets and audit paths. Providers who give APIs, governance, and integration capabilities in marketing technology stacks get into long-term deals, whereas those who provide content credentialing and provenance services meet their compliance and trust needs.
Recent Developments:
- 2025: Black Forest Labs launched FLUX.1 Kontext, a suite of models that generates and edits images from text and reference images, with Pro and Max variants that support multi-turn edits while preserving characters and styles.
- 2025: Google released Gemini 2.5 Flash Image in the Gemini app and through its API, Google AI Studio and Vertex AI, offering character consistency, multi-image merging and plain-language edits at roughly USD 0.039 per image.
- 2026: Canva Pty Ltd improved Magic Eraser for cleaner object removal and upgraded Image to Video to animate photos featuring human faces.
- 2026: Runway AI, Inc. launched Aleph 2.0 and Edit Studio, bringing image-level editing precision to video workflows. This is adjacent to image editing rather than a standalone photo-editor launch.
AI Image Editor Market Key Players are:
- Adobe Inc.
- Canva Pty Ltd
- Google LLC
- Microsoft Corporation
- OpenAI
- Midjourney, Inc.
- Photoroom SAS
- Lightricks Ltd.
- Runway AI, Inc.
- Stability AI Ltd.
- Black Forest Labs
- Picsart, Inc.
- Skylum Software
- Corel Corporation
- Meitu, Inc.
- Topaz Labs
- Freepik
- Pixlr (Inmagine Group)
- Fotor
- Leonardo.ai
AI Image Editor Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 5.90 Billion |
| Market Size by 2035 | USD 51.53 Billion |
| CAGR | CAGR of 24.20% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Tool Type (Integrated Design Platforms, Text-to-Image Editors, Retouching and Enhancement Tools, Others) • By Deployment (Cloud-Based, On-Device, Hybrid) • By End-User (Individual Creators, Enterprise and Marketing Teams, Professional Photographers, Educational Users, Others) • By Application (Social Media Content Creation, E-Commerce and Product Visualization, Advertising and Marketing, Photography Retouching, Others) • By Pricing Model (Freemium, Subscription, Pay-per-Use, Enterprise License) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Adobe Inc., Canva Pty Ltd, Google LLC, Microsoft Corporation, OpenAI, Midjourney, Inc., Photoroom SAS, Lightricks Ltd., Runway AI, Inc., Stability AI Ltd., Black Forest Labs, Picsart, Inc., Skylum Software, Corel Corporation, Meitu, Inc., Topaz Labs, Freepik, Pixlr (Inmagine Group), Fotor, Leonardo.ai |

Frequently Asked Questions
Key players include Adobe, Canva, Google, Microsoft, OpenAI, Midjourney, and Leonardo.ai, among others.
Key opportunities include agentic editing workflows, e-commerce image automation, enterprise brand-safe tools with governance, and on-device editing for mobile users.
The major growth factor is the rapid improvement of generative models that follow plain-language edits and keep subjects consistent, combined with rising demand for visual content across social media and e-commerce.
By Tool Type, the Integrated Design Platforms segment dominated the market with approximately 41.60% share in 2025, owing to the convenience of editing within existing design and publishing tools.
North America dominated the market with a share of 38.20% in 2025, supported by leading software and AI companies, large creator and brand communities and early adoption in the United States.
