
Anatomic Pathology Market Report Scope & Overview:
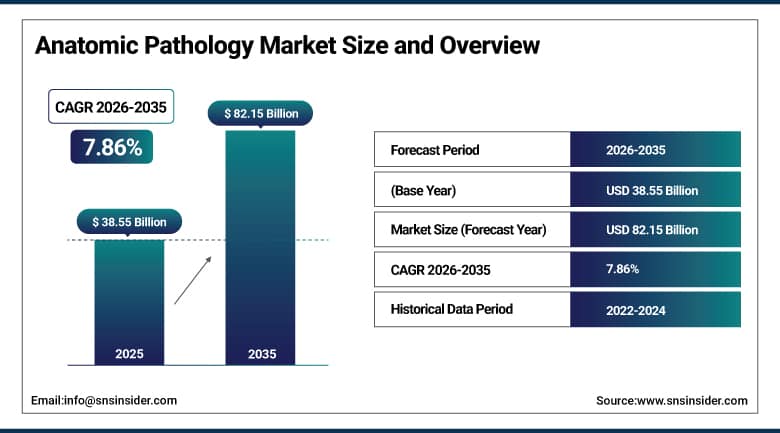
The Anatomic Pathology Market was valued at USD 38.55 Billion in 2025 and is estimated at USD 41.58 Billion in 2026. It is projected to reach USD 82.15 Billion by 2035, advancing at a CAGR of 7.86% from 2026 to 2035. Anatomic pathology covers the examination of tissue and cells to diagnose disease, and it underpins cancer care, drug development, and transplant medicine. Rising biopsy volumes, automated staining, whole-slide imaging, and artificial intelligence are expanding the range of tests that laboratories can run and the speed at which results reach clinicians.
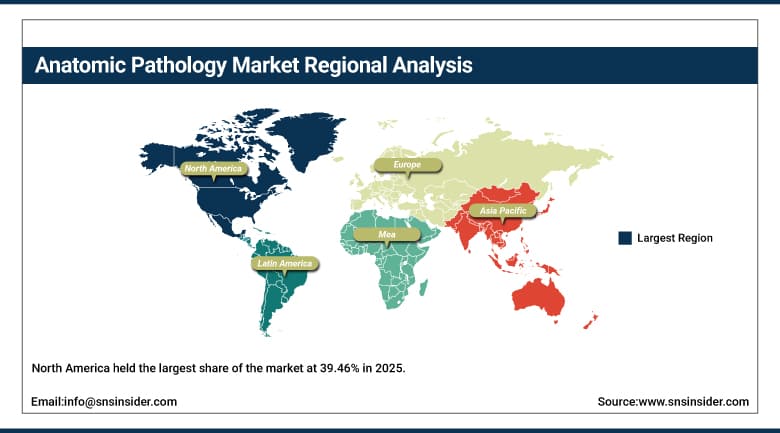
North America was the largest regional market in 2025 with a 39.46% share, supported by high cancer screening rates, large reference laboratory networks, and early adoption of digital workflows. Asia Pacific follows and is expected to grow fastest over the forecast period as hospital capacity and oncology programs expand in China, India, and Japan. Europe benefits from organized screening programs and a strong research base, while Latin America and the Middle East & Africa are building pathology capacity from smaller bases and are adding laboratory infrastructure through public and private investment.
To Get More Information On Anatomic Pathology Market - Request Free Sample Report
Key Report Takeaways:
-
By product and service, consumables held a 47.12% share in 2025, while services are the fastest growing.
-
By technology, histopathology accounted for a 32.64% share in 2025, while digital pathology is the fastest growing.
-
By application, disease diagnosis represented a 69.37% share in 2025, while drug discovery and development is the fastest growing.
-
By end user, hospitals commanded a 41.28% share in 2025, while diagnostic laboratories are the fastest growing.
-
By region, North America led with a 39.46% share in 2025, while Asia Pacific is the fastest growing.
Market Trends and Insights:
Digital pathology is moving from pilot projects to enterprise deployment. Laboratories are scanning slides at scale, linking images to laboratory information systems, and allowing pathologists to review cases remotely, which shortens turnaround times and allows subspecialty expertise to be shared across hospital networks and regions.
Artificial intelligence is entering routine review. Algorithms that screen prostate, breast, and skin specimens, flag quality problems, and quantify biomarkers are gaining regulatory clearances, and laboratories are using them as a second read that supports consistent grading and reduces the time spent on repetitive counting tasks.
Staining and assay automation is deepening. Immunohistochemistry and in situ hybridization platforms now run multiplex and RNA-based assays on routine stainers, which brings spatial and molecular detail into everyday diagnosis and reduces the manual steps that once limited throughput in smaller laboratories.
Drivers Impact Analysis:
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Rising Cancer Burden and Biopsy Volumes |
+2.78% |
Global |
Long term (4 years or more) |
|
Precision Medicine and Companion Diagnostics |
+2.28% |
North America and Europe |
Medium term (2 to 4 years) |
|
Digital Pathology and Artificial Intelligence Adoption |
+1.96% |
North America and Europe |
Medium term (2 to 4 years) |
|
Laboratory Automation to Offset Workforce Gaps |
+1.62% |
Global |
Short term (2 years or less) |
|
Healthcare Infrastructure Expansion in Emerging Regions |
+1.06% |
Asia Pacific, Middle East & Africa, and Latin America |
Long term (4 years or more) |
Rising Cancer Burden and Biopsy Volumes
Cancer incidence continues to rise as populations age, and nearly every new diagnosis begins with a tissue sample examined by a pathologist. The American Cancer Society projected 2,114,850 new cancer cases in the United States for 2026, a figure that translates directly into biopsies, resections, and follow-up staining. Screening programs for breast, cervical, colorectal, lung, and prostate cancer add further specimens each year. Laboratories respond by buying processors, stainers, and reagents, and by contracting reference services when internal capacity is stretched, which supports demand across instruments, consumables, and services.
Precision Medicine and Companion Diagnostics
Targeted therapies increasingly require a biomarker result from tissue before treatment begins, and that requirement expands the number of tests per patient. Immunohistochemistry and in situ hybridization assays that guide choices for breast, lung, gastric, and other cancers are now routine, and new antibody clones continue to enter clinical use. Drug developers also partner with diagnostic makers to validate assays alongside new therapies. In North America and Europe, reimbursement for biomarker testing is broadening, which encourages laboratories to add menus, buy automated platforms, and stock a wider range of antibodies and probes.
Digital Pathology and Artificial Intelligence Adoption
Whole-slide scanners and image management software let laboratories store, share, and analyze slides without moving glass. Regulators have cleared scanners for primary diagnosis, and several algorithms for prostate cancer detection and quality control have received clearance in the United States. Hospital systems value remote review, faster second opinions, and the ability to build image archives for research. As scanning costs fall and software matures, adoption is moving beyond academic centers toward community hospitals and reference laboratories, which lifts demand for scanners, storage, analysis software, and related services.
Laboratory Automation to Offset Workforce Gaps
Many regions report too few pathologists and histotechnologists to meet growing specimen volumes, and laboratories are turning to automation to protect turnaround times. Automated tissue processors, coverslippers, slide printers, and specimen tracking systems reduce manual handling and transcription errors, while barcode traceability supports accreditation. Larger networks also centralize work in high-volume hubs equipped with robotics. Automation lowers the labor needed per specimen, which makes laboratories more willing to invest in capital equipment and recurring consumables contracts even when hiring remains difficult.
Healthcare Infrastructure Expansion in Emerging Regions
Cancer centers are being developed, hospital laboratories are upgraded, and more insurance coverage is provided in the Asia Pacific, the Middle East, and Latin America regions, thus increasing access to histopathology and cytopathology services. The number of tertiary hospitals and private diagnostic chains is increasing in India and China, while the Gulf nations are investing in cancer programs and referral centers. The majority of these laboratories begin their operations using modern automated instruments rather than switching from manual solutions, and they like packages that include instruments, reagents, and training. Higher income and awareness of early diagnosis drive steady volumes after 2026.
Restraints Impact Analysis:
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Shortage of Pathologists and Histotechnologists |
-0.78% |
Global |
Long term (4 years or more) |
|
Stringent Regulatory and Accreditation Requirements |
-0.51% |
North America and Europe |
Medium term (2 to 4 years) |
|
High Capital Cost of Instruments and Imaging Systems |
-0.36% |
Global |
Short term (2 years or less) |
|
Data Interoperability and Standards Gaps |
-0.19% |
Global |
Medium term (2 to 4 years) |
Shortage of Pathologists and Histotechnologists
Laboratories in many countries struggle to recruit and retain pathologists, histotechnologists, and cytotechnologists. Training pipelines are long, and retirements are outpacing new entrants in several markets, which delays reporting and limits how many specimens a laboratory can accept. Some hospitals postpone expansion or new test menus until staffing improves. Automation and remote review ease the burden, but implementation requires trained staff and time, so the shortage slows market growth even as it encourages investment in labor-saving tools. Wage pressure for scarce specialists also raises laboratory operating costs.
Stringent Regulatory and Accreditation Requirements
Diagnostic products and laboratory processes face detailed rules on validation, quality, and reporting. In the European Union, the in vitro diagnostic regulation sets staged transition dates running from 2027 to 2029, and manufacturers must work with notified bodies to keep established products on the market. In the United States, the Food and Drug Administration formally vacated its laboratory developed test rule in September 2025, but clearance pathways for devices and software remain demanding. Compliance work lengthens launch schedules and raises costs for smaller suppliers.
High Capital Cost of Instruments and Imaging Systems
The tissue processor, the automated stainer, and the whole-slide scanner require a considerable initial investment, to be followed by service agreements, licensing, and storage. The digital solutions require networking and servers as well as changes in workflows, thus increasing the overall cost above the cost of the scanner alone. Small hospitals and laboratories from poor countries postpone their purchases or use manual processes. To counteract this situation, vendors resort to reagent rentals and leasing as well as subscription fees, yet payback periods remain long. Maintenance and reagent agreements add to the costs after purchasing.
Data Interoperability and Standards Gaps
Digital pathology depends on image formats, laboratory information systems, and analysis tools that do not always exchange data smoothly. Proprietary scanner formats, differing metadata practices, and uneven adoption of imaging standards make it harder to combine archives or switch vendors. Laboratories must invest in integration work, and algorithm developers face difficulty training models on varied slide sets. These gaps slow multi-site deployments and add cost, which limits the speed at which digital workflows scale across large health systems. Industry groups are working on common formats, though adoption remains uneven.
Anatomic Pathology Market Segment Analysis:
By Product and Service, Consumables Dominate Anatomic Pathology Market; Services to Register Fastest Growth.
Consumables led the market with a 47.12% share in 2025 because every specimen consumes reagents, antibodies, probes, stains, slides, and cassettes. These items are bought repeatedly, and their volumes rise with biopsy counts. Antibody panels and detection kits tied to targeted cancer therapies add further spending, while reagent rental agreements link instrument placements to steady purchases over many years. Suppliers also gain from recurring orders as laboratories standardize on one vendor menu. Pharmacy-style stock management helps laboratories avoid shortages.
Services are expected to register the fastest growth, with a CAGR of 10.56% from 2026 to 2035. Hospitals with limited staff are sending specimens to reference laboratories, and drug developers are contracting pathology work for clinical trials. Image analysis, remote review, and subspecialty consultation are sold as services. Instruments remain essential and benefit from automation and scanner adoption, but outsourced work is expanding faster. Recurring analysis fees and growing trial work add to this momentum. Quality oversight adds further value.
By Technology, Histopathology Dominates Anatomic Pathology Market; Digital Pathology to Register Fastest Growth.
Histopathology accounted for a 32.64% share in 2025 as the foundation of tissue diagnosis. Processing, embedding, sectioning, and staining of tissue are performed for nearly every surgical specimen, and routine hematoxylin and eosin slides remain the reference for most diagnoses. Immunohistochemistry and in situ hybridization build on histology workflows, so growth in biopsies keeps this technology central to laboratory operations. Pathologists still treat tissue morphology as the first step before any special test. All special stains start here too.
Digital pathology is expected to register the fastest growth, with a CAGR of 10.36% from 2026 to 2035. Scanners, image management platforms, and algorithms are moving from pilot use to routine practice as clearances widen and storage costs decline. Laboratories adopt them to speed second opinions, support remote review, and build searchable archives. Molecular pathology and cytopathology advance steadily, but the pace of digital adoption stands out. Vendors continue to improve scanning speed and storage efficiency to support this shift.
By Application, Disease Diagnosis Dominates Anatomic Pathology Market; Drug Discovery and Development to Register Fastest Growth.
Disease diagnosis held a 69.37% share in 2025 because most specimens are examined to confirm or exclude cancer and other conditions. Oncology dominates this use, covering breast, prostate, lung, colorectal, and skin cancers, while infectious and autoimmune diseases add smaller volumes. Biomarker testing for treatment selection has lengthened the list of tests per case, which supports spending on antibodies and automated platforms. Rising cancer incidence therefore anchors demand for routine diagnostic workflows. Oncology carries most of this spending.
Drug discovery and development is expected to register the fastest growth, with a CAGR of 10.06% from 2026 to 2035. Pharmaceutical and biotechnology companies use tissue analysis to assess target expression, safety, and response in preclinical and clinical programs. Spatial and multiplex methods are increasingly part of these studies. Growth in oncology pipelines and companion diagnostic partnerships raises the number of studies that depend on pathology. Academic centers and contract research groups sustain strong demand for specialized staining panels.
By End User, Hospitals Dominate Anatomic Pathology Market; Diagnostic Laboratories to Register Fastest Growth.
The share of hospitals was 41.28% in 2025 since they have their own in-house pathology laboratories that handle the surgeries, oncology, and emergency cases. The hospitals purchase the processors, stainers, microtomes, and scanners; they have the biggest volume of surgical specimens. The academic medical centers also take the lead on digital pathology and novel assays, which sets the standard for community hospitals to adopt. In general, the procurement process in such facilities prefers fully integrated solutions with a long-term contract. There are tumor boards and accreditation requirements that ensure the proximity of pathology to the hospitals.
The diagnostic laboratories are expected to see the highest growth at CAGR of 10.86% from 2026 to 2035. There are independent and reference laboratories that get the outsourced work from hospitals, invest in the automation and molecular and digital solutions. The consolidation of the large network will give them an ability to negotiate reagent contracts and centralized tests. The other users provide stable demands for the products, but there are outsourcing trends that will benefit the commercial laboratories.
Geography Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.10% |
|
Asia Pacific |
China |
23.17% |
|
Europe |
Germany |
24.35% |
|
Latin America |
Brazil |
41.82% |
|
Middle East & Africa |
Saudi Arabia |
22.64% |
North America Anatomic Pathology Market
North America held the largest share of the market at 39.46% in 2025, supported by high cancer screening rates, large reference laboratory networks, and early adoption of automated and digital workflows. The United States accounted for most regional demand, with a 2025 value of USD 12.95 Billion, and is expected to grow at a CAGR of 7.62% from 2026 to 2035. Canada adds steady demand through provincial screening programs. Provincial and state programs add predictable specimen volumes each year. Canada also supports growth through provincial programs and cancer agencies.
Biomarker testing reimbursement, cancer research funding from the government, and having a vast number of academic medical centers ensure continued investment in cutting-edge assays. Reference laboratories continue their investments in scanners and automation in order to deal with volumes, whereas hospitals are increasingly turning to artificial intelligence technologies in the review of prostates and breasts. Shortages of personnel are driving laboratories towards labor-reducing machines and remote reviewing. Pricing is influenced by group purchasing organizations, and competition between vendors takes the form of bundled kits and services.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Anatomic Pathology Market
Asia Pacific region is projected to show rapid growth in the regional market with a CAGR of 9.46% from 2026 to 2035. The region includes the development of tertiary hospitals, cancer centers, and private diagnostic chain in China and India, whereas Japan and South Korea include the development of digital pathology and staining technology. The insurance coverage along with the increasing awareness about the significance of early diagnosis results in the growing number of biopsies in the region. There is a presence of public insurance programs in India that facilitates access to biopsy based diagnostics. Digital pathology and staining is growing in South Korea and Australia as well, among other large hospital networks.
The growth of local players in the region is seen in addition to that of global players through their provision of cheaper stainers, microtomes, and reagents available to community hospitals. Government screening for cervical, breast, and gastric cancer provides more specimens, and telepathology connects smaller hospitals to large ones. Southeast Asian countries are now establishing labs, resulting in higher demand for equipment and reagents from distributors and trainers. Investment in the digital infrastructure of hospitals enables them to exchange imaging and expertise across provinces and countries.Singapore and Hong Kong become regional referral hubs.
Europe Anatomic Pathology Market
Europe represents a mature market with organized screening programs, strong public laboratory networks, and a deep research base. Germany, the United Kingdom, France, and Italy account for most regional spending, and hospital consolidation is pushing laboratories toward centralized, automated operations. Digital pathology programs are expanding in national health systems, supported by regional funding for cancer diagnostics and shared image archives. Public tenders usually reward suppliers that combine instruments, consumables, and long service coverage for large laboratory networks. The United Kingdom and the Nordic countries invest in digital pathology programs.
The in vitro diagnostic regulation is reshaping product portfolios, since manufacturers must recertify assays and reagents, and some smaller suppliers may withdraw products. At the same time, demand for companion diagnostics grows with new oncology drugs. Pathologist shortages in several countries encourage investment in scanners, remote review, and artificial intelligence tools to maintain reporting speed. Cross-border research collaborations also keep demand for specialized antibodies and imaging tools stable. Spending patterns differ widely by country, and Eastern Europe is building capacity more gradually than the western economies.
Latin America Anatomic Pathology Market
The Latin America market is a smaller one but a growing one, where Brazil and Mexico contribute to the majority of expenses in the region. Healthcare institutions increase the amount of screening activities and improve hospital laboratories while private hospitals and diagnostic laboratories invest in advanced staining equipment and imaging systems. Currencies' fluctuations and budgeting influence the purchase schedule but the trend is positive. Local distributors provide support to international manufacturers when introducing their products to the laboratories of smaller cities by providing trainings and maintenance. The presence of private hospital development, the medical tourism industry, and insurance reform makes Mexico an attractive destination for diagnostics.
Argentinean, Colombian, and Chilean market expands the oncology services, introduces new immunohistochemistry procedures. Local distributors have a significant influence on the introduction of instruments and reagents along with the training of laboratory personnel. Financing helps smaller laboratories implement automation technologies. Telepathology projects in the region make a connection between distant hospitals and the pathologists of large cities, which promotes the purchase of scanners and related software. Public-private partnerships can be found as one of the ways to finance pathology equipment for regional hospitals.
Middle East & Africa Anatomic Pathology Market
The Middle East & Africa region holds the smallest share, yet it is gaining attention from suppliers as governments build specialized hospitals and national cancer programs. Saudi Arabia and the United Arab Emirates lead in adopting advanced equipment, supported by public investment in healthcare infrastructure and partnerships with international medical centers. South Africa remains the main market in Africa. Regional medical cities and free zones are attracting international laboratory operators and specialist pathologists. Turkey and Egypt also contribute through large public hospital systems and growing private networks.
Many countries still rely on referral abroad or on limited local capacity, so new laboratories often start with automated equipment and imported reagents. Training programs and telepathology links with international centers are helping to address staffing gaps. Growth is steady from a small base, with demand concentrated in major urban hospitals and private diagnostic groups. Over time, new oncology centers and training partnerships should widen the base of laboratories that can purchase advanced equipment. Gulf health authorities are setting accreditation standards that encourage laboratories to adopt traceable, automated workflows.
Competitive Landscape:
The competitive landscape combines diversified diagnostics groups, specialist histology equipment makers, large reference laboratory operators, and a growing set of digital pathology and artificial intelligence developers. Leading suppliers compete on automated staining platforms, antibody and probe menus, scanner quality, and software integration, while service providers compete on turnaround time, subspecialty expertise, and test menus.
Strategies center on connecting hardware, reagents, and software into complete workflows, on securing regulatory clearances for scanners and algorithms, and on forming partnerships with hospital networks and reference laboratories. Acquisitions and take-private transactions are reshaping ownership, and companion diagnostic collaborations with drug developers are becoming a durable source of revenue. Smaller companies differentiate through specialized assays, tracking systems, and cloud image management.
Anatomic Pathology Market Industry Leaders:
1. Roche Diagnostics: Supplier of the VENTANA platform for automated immunohistochemistry and in situ hybridization, along with digital pathology scanners and image analysis software.
2. Danaher: Parent of Leica Biosystems, which offers histology equipment, BOND staining platforms, Aperio digital pathology scanners, and specimen tracking systems.
3. Agilent Technologies: Maker of Dako immunohistochemistry reagents, antibodies, and staining systems used for cancer diagnosis and companion diagnostics.
4. Sakura Finetek: Japanese maker of the Tissue-Tek line of tissue processors, microtomes, stainers, and coverslippers for histology laboratories.
5. Epredia: PHC Holdings company that supplies microtomes, tissue processing and cytology products, slides, slide printers, and archiving solutions for pathology laboratories.
Companies Covered in this Report:
-
Roche Diagnostics
-
Danaher
-
Agilent Technologies
-
Sakura Finetek
-
Epredia
-
Hologic
-
Hamamatsu Photonics
-
Labcorp
-
NeoGenomics
-
Sonic Healthcare
-
Tempus AI
-
PathAI
-
Ibex Medical Analytics
-
Indica Labs
Recent Industry Developments:
-
February 2025: Ibex Medical Analytics received U.S. FDA 510(k) clearance for Ibex Prostate Detect, an artificial intelligence second read for prostate core biopsy images.
-
August 2025: Tempus AI agreed to acquire Paige, an artificial intelligence pathology company with a large archive of digitized slides.
-
September 2025: Labcorp announced a collaboration to deploy Roche VENTANA DP 600 and DP 200 scanners for digital diagnosis.
-
March 2026: Leica Biosystems launched BOND-PRIME RNAscope Brown Detection in the United States, automating RNAscope in situ hybridization on the BOND-PRIME platform.
-
April 2026: Hologic completed its take-private transaction with funds managed by Blackstone and TPG.
-
May 2026: Epredia launched the SlideMate Thermal Slide Printer for pathology laboratories.
-
October 2026: NeoGenomics expanded its partnership with Indica Labs to adopt the HALO AP cloud platform for digital pathology.
-
October 2026: Roche Diagnostics launched the VENTANA BAP1 (SP527) immunohistochemistry test to support differential diagnosis of mesothelioma.
Scope and Research Methodology
This report defines the Anatomic Pathology Market as the commercial value of instruments, consumables, and services used to examine tissue and cells for diagnosis and research, including histology, cytology, immunohistochemistry, in situ hybridization, molecular pathology, and digital pathology. Clinical chemistry, hematology, and microbiology laboratory testing are excluded, as are stand-alone sequencing services that do not involve tissue examination. Values are stated in USD at the point of sale to laboratories and, for services, at the fee billed to payers or clients. The base year is 2025 and the forecast runs from 2026 to 2035. Software sold apart from pathology workflows and veterinary pathology are excluded as well.
Primary research comprised interviews with pathologists, laboratory directors, histotechnologists, procurement managers, distributors, and executives at instrument, reagent, and software companies. Secondary research drew on cancer registries, regulator databases, health ministry statistics, accreditation bodies, company filings, product catalogs, and clinical society publications. Specimen volumes were linked to cancer incidence, screening coverage, and hospital capacity in each country, then converted to value using test mix and price points. Each interview followed a structured guide covering specimen volumes, equipment purchase cycles, reagent contracts, outsourcing patterns, and adoption barriers, and responses were coded by region and by laboratory type so that patterns could be compared across countries.
A bottom-up build by product, technology, and country was cross-checked against a top-down view based on laboratory spending and disease burden. Forecasts apply growth rates by segment that reflect screening expansion, assay adoption, scanner placements, and pricing trends, with scenarios for regulatory change. Regional shares were validated against hospital counts and laboratory density, and the five regions sum to the global figure. Findings were reviewed by internal analysts and external experts before release. Where estimates differed, analysts revisited assumptions on pricing and specimen counts and consulted additional experts until the figures converged.
Anatomic Pathology Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 38.55 Billion |
| Market Size by 2035 | USD 82.15 Billion |
| CAGR | CAGR of 7.86% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product and Service (Instruments, Consumables, and Services) • By Technology (Histopathology, Cytopathology, Immunohistochemistry, In Situ Hybridization, Digital Pathology, Molecular Pathology, and Others) • By Application (Disease Diagnosis, Drug Discovery and Development, and Others) • By End User (Hospitals, Diagnostic Laboratories, Research Laboratories, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Roche Diagnostics, Danaher, Agilent Technologies, Sakura Finetek, Epredia, Hologic, Hamamatsu Photonics, Labcorp, NeoGenomics, Sonic Healthcare, Tempus AI, PathAI, Ibex Medical Analytics, Indica Labs |

Frequently Asked Questions
The market was valued at USD 38.55 Billion in 2025 and is estimated at USD 41.58 Billion in 2026. It is forecast to reach USD 82.15 Billion by 2035.
The market is projected to expand at a CAGR of 7.86% from 2026 to 2035.
North America led with a 39.46% share in 2025, while Asia Pacific is the fastest-growing region, with a CAGR of 9.46% from 2026 to 2035.
Digital pathology is expected to record the fastest growth, with a CAGR of 10.36% from 2026 to 2035.
Rising cancer burden, precision medicine and companion diagnostics, digital pathology and artificial intelligence, laboratory automation, and healthcare infrastructure expansion in emerging regions.
A shortage of pathologists and histotechnologists, regulatory and accreditation requirements, high capital cost, and data interoperability gaps.
