
Artificial Heart Market Report Scope & Overview:
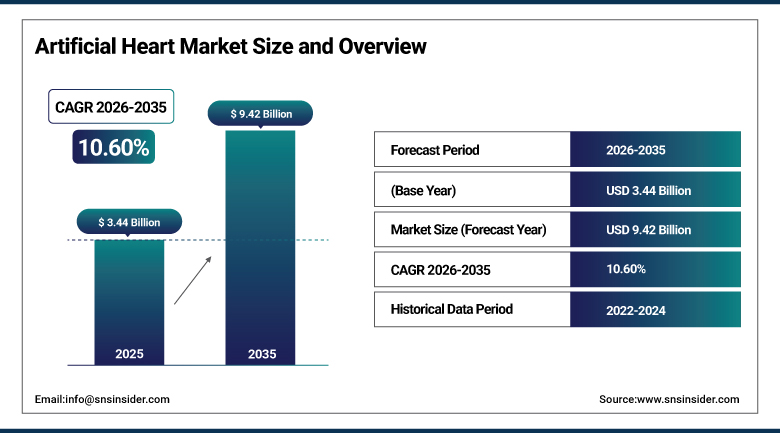
The Artificial Heart Market was valued at USD 3.44 Billion in 2025 and is expected to reach USD 9.42 Billion by 2035, growing at a CAGR of 10.60% from 2026-2035.
The Artificial Heart Market is advancing on the back of a growing population with advanced heart failure, a persistent shortage of donor hearts and steady technical progress in mechanical circulatory support. Revenue is concentrated in ventricular assist devices, which are implanted to support a failing heart for long periods, while total artificial hearts that replace both ventricles are moving from limited bridge-to-transplant use toward longer-term and fully implantable designs. Hospitals are expanding advanced heart failure programs, reimbursement for destination therapy is established in major markets, and newer magnetically levitated pumps have lowered complication rates, which is widening patient eligibility.
⮞On May 29, 2025, BiVACOR announced that its titanium total artificial heart, which uses a single magnetically levitated rotor to power both sides of the circulation, received FDA Breakthrough Device Designation as a bridge to transplant for adults who cannot be treated with other options. The first phase of its early feasibility study implanted five U.S. patients between July and November 2024, and the FDA approved expansion to 15 additional patients, a sign that rotary total artificial hearts are progressing toward wider clinical evaluation.
To Get more information Artificial Heart Market - Request Free Sample Report
Artificial Heart Market Trends
- Magnetically levitated pumps reducing stroke and pump thrombosis rates
- Development of fully implantable total artificial hearts with rotary designs
- Expanded use of destination therapy in patients ineligible for transplant
- Pediatric mechanical circulatory support gaining regulatory approvals
- Remote monitoring and smaller external controllers improving patient mobility
- Public research funding for next-generation bioengineered heart pumps
U.S. Artificial Heart Market Outlook
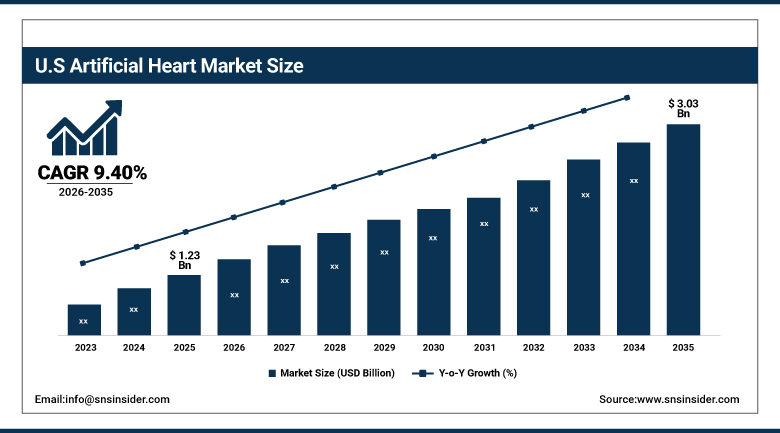
The U.S. Artificial Heart Market was valued at USD 1.23 Billion in 2025 and is expected to reach USD 3.03 Billion by 2035, growing at a CAGR of 9.40% from 2026-2035.
The U.S. Artificial Heart Market is the largest national market, supported by a high prevalence of heart failure, a long donor heart waiting list, established Medicare coverage for destination therapy and a dense network of advanced heart failure centers. Abbott's HeartMate 3 left ventricular assist device is the most widely implanted pump, while SynCardia's temporary total artificial heart is approved for bridge to transplant and several rotary designs are in clinical study. Federal agencies, including the National Institutes of Health, fund device research, and hospitals are expanding implant programs to meet growing demand.
⮞In 2023, the FDA cleared Abbott's HeartMate 3 left ventricular assist device for use in children, extending a magnetically levitated pump that had been used mainly in adults to a patient group with very limited device options. The clearance allows pediatric heart programs to offer longer-term support to children with severe heart failure who are waiting for a donor heart.
Artificial Heart Market Segment Analysis
- By Product, ventricular assist devices segment dominated the Artificial Heart Market in 2025 with an estimated 52.80% share; total artificial hearts segment is the fastest-growing segment, with an estimated CAGR of 15.20% during 2026–2035.
- By Application, destination therapy segment dominated the Artificial Heart Market in 2025 with 35.40% share; bridge to recovery segment is the fastest-growing segment, with an estimated CAGR of 8.90% during 2026–2035.
- By Technology, continuous flow segment dominated the Artificial Heart Market in 2025 with an estimated 82.00% share; pulsatile flow segment is the fastest-growing segment, with an estimated CAGR of 11.60% during 2026–2035.
- By End User, hospitals and ambulatory surgical centers segment dominated the Artificial Heart Market in 2025 with 73.80% share; specialty clinics segment is the fastest-growing segment, with an estimated CAGR of 13.20% during 2026–2035.
By Product, Ventricular Assist Devices Dominate Artificial Heart Market; Total Artificial Hearts to Register Fastest Growth.
Ventricular assist devices dominate the Artificial Heart Market because they are implanted far more often than total artificial hearts and support patients who retain some native heart function. Magnetically levitated pumps such as Abbott's HeartMate 3 have lowered stroke and pump thrombosis rates, which has widened patient eligibility and strengthened clinician confidence. Hospitals with established advanced heart failure programs can offer these devices as long-term therapy, and reimbursement in major markets supports routine adoption alongside heart transplantation. Training programs and proctoring from manufacturers help new centers reach proficiency with these systems.
Total artificial hearts are projected to register the fastest growth because they replace both ventricles in patients with biventricular failure who cannot be supported by a pump alone. The long waiting list for donor hearts keeps demand for bridge-to-transplant support high, and companies are developing fully implantable rotary designs with the aim of longer-term use. Clinical evidence from early feasibility studies and wider regulatory recognition are expected to expand the number of centers able to offer these systems. Pediatric programs also depend on smaller total artificial heart options.
By Application, Destination Therapy Dominates Artificial Heart Market; Bridge to Recovery to Register Fastest Growth.
Destination therapy dominates the Artificial Heart Market because many advanced heart failure patients are ineligible for transplantation owing to age, comorbidities or limited donor supply, and are therefore treated with permanent mechanical support. Coverage for destination therapy is established in major markets, and improved device durability allows patients to live for years with a pump. Hospitals are building dedicated programs that combine implantation, outpatient follow-up and remote monitoring to manage this growing patient group. Remote monitoring of pump parameters helps clinicians detect problems early.
Bridge to recovery is projected to register the fastest growth as temporary percutaneous support devices are used more often in cardiogenic shock and high-risk interventions, giving the heart time to heal. Randomized evidence on survival benefit and expanded regulatory indications, including selected pediatric patients, are encouraging wider use. Bridge to transplant and bridge to decision applications remain important for patients on waiting lists, and the line between temporary and long-term support is becoming less rigid as device options widen. Hospitals therefore keep both temporary and durable support devices available.
By Technology, Continuous Flow Dominates Artificial Heart Market; Pulsatile Flow to Register Fastest Growth.
Continuous flow technology dominates the Artificial Heart Market because axial and centrifugal pumps are smaller, quieter and more durable than earlier pulsatile designs, and they have become the standard for left ventricular support. Magnetic levitation removes mechanical contact and reduces blood trauma, which supports longer implant durations. The compact size also allows implantation through less invasive surgery and in a broader range of body sizes, including some pediatric and smaller adult patients. Fewer moving parts also help keep device noise and power needs low, which improves quality of life.
Pulsatile flow systems are projected to register the fastest growth from a smaller base because pneumatic and electrohydraulic total artificial hearts mimic the natural pumping action and are used to support patients with failure of both ventricles. Developers are refining control software, drivers and power sources to improve mobility and reduce the burden on patients, including portable drivers that allow discharge from hospital. Clinicians regard pulsatile designs as useful where continuous flow physiology is not appropriate. Clinical trials continue to compare both flow types across patient groups.
By End User, Hospitals and Ambulatory Surgical Centers Dominate Artificial Heart Market; Specialty Clinics to Register Fastest Growth.
Hospitals and ambulatory surgical centers dominate the Artificial Heart Market because implantation requires cardiac surgery teams, intensive care units, perfusion services and transplant coordination that exist mainly in large tertiary centers. Device makers train surgeons and support teams at these sites and provide proctoring for new indications. Volumes concentrate in institutions that run advanced heart failure and transplant programs, which also manage complications and follow-up for implanted patients. Reimbursement for implant episodes also steers volumes toward centers with proven outcomes.
Specialty clinics are projected to register the fastest growth as outpatient heart failure clinics take on long-term follow-up, pump parameter adjustment, driveline care and patient education after hospital discharge. Remote monitoring and smaller external controllers allow patients to live at home with support, and clinics provide a lower-cost setting for routine visits. As the number of implanted patients grows, demand for specialized follow-up capacity rises faster than demand for new implant centers. Telehealth visits further support this shift for patients living far from implant centers.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
90.50 |
|
Europe |
Germany |
31.84 |
|
Asia Pacific |
Japan |
38.46 |
|
Latin America |
Brazil |
49.28 |
|
Middle East & Africa |
Saudi Arabia |
33.17 |
North America Artificial Heart Market Insights
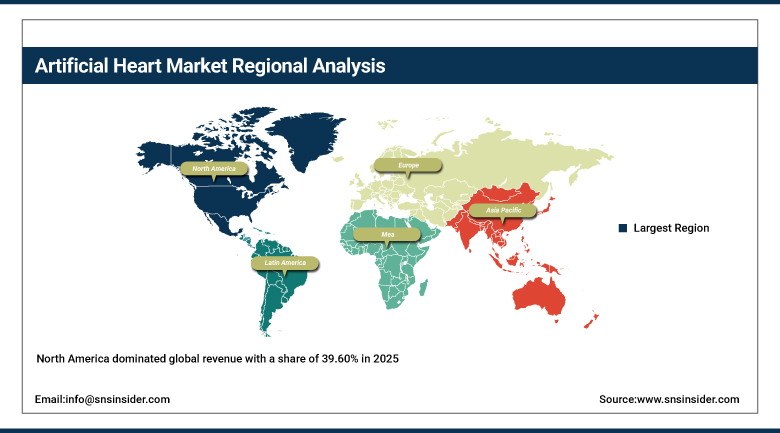
North America dominated global revenue with a share of 39.60% in 2025, supported by a high prevalence of heart failure, a long donor heart waiting list, established Medicare coverage for destination therapy and a dense network of advanced heart failure centers. The United States accounts for most regional demand, with Abbott and Abiomed, part of Johnson & Johnson MedTech, based in the region. Several leading heart failure centers also act as trial sites for new circulatory support devices.
Federal research funding and active clinical trial programs support next-generation devices, including rotary total artificial hearts in early feasibility studies. Canada adds demand through provincial heart failure programs. High device prices and complication risk moderate growth relative to emerging regions, and hospitals must balance implant volumes with intensive follow-up resources. Patient advocacy groups and transplant networks contribute to awareness of mechanical support options. Medicare coverage rules and center certification requirements shape which hospitals can offer durable support. Insurers are also paying closer attention to outcomes.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Artificial Heart Market Insights
Europe is growing at a CAGR of 9.90% during 2026-2035. Germany leads regional demand through a strong cardiac surgery base and manufacturers such as Berlin Heart and Xenios, followed by France, the United Kingdom, Italy and Spain. Getinge in Sweden and LivaNova in the United Kingdom also supply circulatory support systems to hospitals across the region. Scandinavian countries and the Netherlands also operate national registries that track outcomes of implanted devices. Spain and Italy add steady volumes through public hospital programs.
National health systems negotiate reimbursement for mechanical circulatory support, and European regulation under the medical device framework requires extensive clinical evidence, which raises entry barriers for new developers. The insolvency proceedings of CARMAT in 2025 showed the financing risk faced by independent developers, although public and private investors continue to fund research into smaller, durable pumps for both adults and children. Transplant waiting lists in several countries remain long, which sustains demand for devices that bridge patients safely to surgery.
Asia Pacific Artificial Heart Market Insights
Asia Pacific is projected to be the fastest-growing region, advancing at a CAGR of 12.80% from 2026-2035. Japan leads regional demand through established reimbursement for implantable pumps and local suppliers such as Sun Medical, which launched its EVAHEART 2 C03 system in 2024. China is expanding quickly, with local developers such as Shenzhen Core Medical Technology, while India and South Korea add volumes through growing cardiac surgery programs. Clinical collaborations between regional hospitals and international developers are expanding patient access to newer pumps. Japan also has a long clinical history with implantable pumps, which sustains surgical expertise.
A large patient pool, rising incidence of cardiovascular disease and government investment in tertiary care are the main growth factors. Australia contributes through research hospitals and device development, and Southeast Asian economies are adding advanced heart failure centers in major cities. Affordability and limited donor heart supply in several countries create demand for durable mechanical support, although price sensitivity favors lower-cost local devices. Government health insurance programs in Japan and South Korea support reimbursement for approved implantable pumps. Rising public awareness also helps.
MEA & Latin America Artificial Heart Market Insights
In Latin America, Brazil leads on the strength of its large public and private hospital network, followed by Mexico, Argentina and Chile, where advanced heart failure centers are adding implant programs. Donor heart shortages and rising cardiovascular disease burden drive interest in mechanical support, although reimbursement is limited and most devices are imported at high cost. Chile and Argentina operate some of the region's most experienced cardiac surgery centers and are early adopters of newer pumps. Colombia and Peru are building capacity in a few leading hospitals.
In the Middle East and Africa, Saudi Arabia and the United Arab Emirates lead through investment in specialized cardiac centers, while South Africa and Egypt hold regional expertise in cardiac surgery. Healthcare diversification programs in Gulf countries support imports of advanced devices, but limited trained staff and uneven reimbursement slow broader adoption across the wider region. Partnerships with international device makers and training programs for surgeons are helping to extend implant capability beyond a few leading hospitals. Public programs in the Gulf also fund overseas training for cardiac surgeons.
Market Dynamics
Growth Drivers: Rising Heart Failure Prevalence and Donor Heart Shortage
The rising prevalence of advanced heart failure is the primary driver of demand for mechanical circulatory support. Aging populations, increasing rates of diabetes and hypertension and improved survival after myocardial infarction are enlarging the group of patients who progress to end-stage disease. Many of these patients are not eligible for transplant, which makes permanent mechanical support the main long-term option and supports steady growth in implant volumes at advanced heart failure centers worldwide.
The persistent shortage of donor hearts reinforces this demand, because the number of transplants is limited by organ availability and waiting times often extend for months or years. Mechanical pumps keep patients alive and mobile during this period, and improved durability allows some to remain on support for many years. Technological advances, including magnetically levitated pumps and compact rotary total artificial hearts, are reducing complications and encouraging clinicians to refer patients earlier, which further expands the treated population.
Restraints: High Device Cost and Complication Risks
High device and procedure costs restrain adoption, particularly outside the main reimbursed markets. An implanted pump, controller, batteries and the associated surgical and intensive care costs can reach several hundred thousand dollars per patient, and lifelong follow-up adds to the total cost of care. In emerging economies with limited insurance coverage, only a small number of patients can afford these systems, and hospitals in cost-constrained health systems are cautious about establishing implant programs.
Clinical complications also limit adoption, as patients on mechanical support face risks of bleeding, infection, stroke, pump thrombosis and right heart failure. Strict anticoagulation regimens and driveline care require patient education and close follow-up, which burden both patients and clinics. Regulatory requirements demand lengthy clinical trials for novel devices, and the financial distress of developers, illustrated by CARMAT's receivership in July 2025, shows the commercial difficulty of bringing a total artificial heart to market.
Opportunities: Fully Implantable Total Artificial Hearts and Expanding Indications
Fully implantable total artificial hearts offer a significant opportunity because they can address patients with biventricular failure who currently have few options. Rotary designs with magnetic levitation promise greater durability and smaller size than earlier pulsatile devices, and early feasibility results for investigational systems are encouraging. A device approved for long-term use rather than only as a bridge would open a large patient pool, and manufacturers that reach this milestone first could secure a leading position.
Expanding indications create additional opportunity, including pediatric use, earlier intervention in less sick patients and use as a bridge to recovery. Remote monitoring, smaller controllers, wireless power transfer and data analytics can improve outcomes and lower follow-up costs, creating service revenue. Emerging markets in Asia and the Middle East are building cardiac infrastructure, and manufacturers that offer training, financing and locally adapted support can develop new customer bases over the forecast period.
Recent Developments:
- In July 2025, CARMAT was placed in receivership by the Versailles Economic Affairs Court after announcing it was insolvent. The company stated that operations would continue during the observation period and that it would seek to support patients using its Aeson artificial heart.
- As of its 2026 registration filing, Picard Medical, the parent of SynCardia Systems, reported that more than 2,100 SynCardia total artificial hearts have been implanted in 27 countries. The company, which is listed on NYSE American, plans to seek approval for implant durations of two years or longer.
- In May 2024, Sun Medical launched the EVAHEART 2 C03 left ventricular assist device in Japan and ended sales of the earlier C02 model. The launch refreshes the company's centrifugal pump line for Japanese hospitals.
- In December 2024, Abiomed expanded the FDA indications for its Impella 5.5 and Impella CP with SmartAssist to include certain pediatric patients. The change widens use of temporary percutaneous support in children with cardiogenic shock.
Artificial Heart Market Key Players are:
- Abbott Laboratories
- Abiomed, Inc. (Johnson & Johnson MedTech)
- Medtronic plc
- Getinge AB
- Terumo Corporation
- LivaNova PLC
- Berlin Heart GmbH
- Jarvik Heart, Inc.
- ReliantHeart, Inc.
- Evaheart, Inc.
- BiVACOR, Inc.
- SynCardia Systems, LLC (Picard Medical, Inc.)
- CorWave SA
- Calon Cardio-Technology Ltd.
- FineHeart SA
- Magenta Medical Ltd.
- Procyrion, Inc.
- Xenios AG (Fresenius Medical Care)
Artificial Heart Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.44 Billion |
| Market Size by 2035 | USD 9.42 Billion |
| CAGR | CAGR of 10.60% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Ventricular Assist Devices, Total Artificial Hearts, and Heart-Lung Machines and Others) • By Application (Destination Therapy, Bridge to Transplant, Bridge to Recovery, and Others) • By Technology (Continuous Flow and Pulsatile Flow) • By End User (Hospitals and Ambulatory Surgical Centers, Specialty Clinics, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Abbott Laboratories; Abiomed, Inc. (Johnson & Johnson MedTech); Medtronic plc; Getinge AB; Terumo Corporation; LivaNova PLC; Berlin Heart GmbH; Jarvik Heart, Inc.; ReliantHeart, Inc.; Evaheart, Inc.; BiVACOR, Inc.; SynCardia Systems, LLC (Picard Medical, Inc.); CorWave SA; Calon Cardio-Technology Ltd.; FineHeart SA; Magenta Medical Ltd.; Procyrion, Inc.; Xenios AG (Fresenius Medical Care) |

Frequently Asked Questions
Key players include Abbott, Abiomed (Johnson & Johnson MedTech), Medtronic, Getinge, Terumo, LivaNova, Berlin Heart, Jarvik Heart, ReliantHeart, Evaheart, BiVACOR and SynCardia (Picard Medical).
Key opportunities include fully implantable total artificial hearts approved for long-term use, pediatric and earlier-stage indications, remote monitoring services and expansion in Asia Pacific and the Middle East.
The major growth factor is the rising number of patients with advanced heart failure combined with a chronic shortage of donor hearts, which makes mechanical circulatory support a primary option.
By Product, the Ventricular Assist Devices segment dominated the market in 2025, supported by lower complication rates with magnetically levitated pumps and established reimbursement.
North America dominated the market with a share of 39.60% in 2025, driven by a high heart failure burden, a long donor heart waiting list and established coverage for destination therapy.
